 TaxTMI
Login
 TaxTMI

Login
Loading...
Press 'Enter' to add multiple search terms. Rules for Better Search

Press 'Enter' after typing page number.
Press 'Enter' after typing page number.


No Folders have been created
Are you sure you want to delete "My most important" ?
NOTE:
Press 'Enter' after typing page number.
Press 'Enter' after typing page number.

All TMI Notes
Press 'Enter' after typing page number.
Press 'Enter' after typing page number.
All TMI Notes

Note

Bookmark

Share


This is a neutral professional article. The judgment is analysed in the context of its factual background, issues framed, and conclusions reached by the Court.
2026 (8) TMI 566 - BOMBAY HIGH COURT
The central question is whether a co-operative bank must deduct tax at source from interest credited or paid on deposits maintained by a co-operative society that is not a member of the bank. The issue requires close attention to the language of Section 194A(3)(v), particularly because that clause addresses two different relationships: payment to a member, and payment from one co-operative society to another.
The general rule is contained in Section 194A(1). A person, other than an individual or Hindu undivided family, who is responsible for paying to a resident income by way of interest other than interest on securities must deduct income-tax at the rates in force at the time of credit to the payee's account or payment, whichever is earlier. The Explanation deems a credit to an account described as an "Interest payable account" or "Suspense account", or by any other name, to be credit to the account of the payee.
The controversy arose because co-operative banks conduct banking business, and specific provisions concerning banking deposits, thresholds and time deposits coexist with the exemption in Section 194A(3)(v). The statutory task is therefore not to treat every exemption in Section 194A(3) as operating identically, but to give effect to the particular language applicable to the identity of the payer, the recipient and the deposit relationship.
The decision in 2026 (8) TMI 566 - BOMBAY HIGH COURT resolves this question, for the assessment period involved, by separating the two limbs of Section 194A(3)(v) and applying the specific administrative clarification in paragraph 42.7 of Circular No. 19/2015.
Section 2(19) defines a "co-operative society" to mean "a co-operative society registered under the Co-operative Societies Act, 1912, or under any other law for the time being in force in any State for the registration of co-operative societies." This definition supplies the statutory context for construing the expression "co-operative society" in Section 194A(3)(v).
The operative exclusion in Section 194A(3)(v) is that Section 194A(1) shall not apply "to such income credited or paid by a co-operative society (other than a co-operative bank) to a member thereof or to such income credited or paid by a co-operative society to any other co-operative society." The accompanying Explanation states that "co-operative bank" shall have the meaning assigned in Part V of the Banking Regulation Act, 1949.
The first limb expressly excludes a co-operative bank where interest is paid to a member. The second limb, however, does not contain the words "other than a co-operative bank". Its language is directed to payments by "a co-operative society" to "any other co-operative society." That deliberate difference in drafting is the foundation of the distinction.
Section 194A(3)(viia)(a) separately excludes interest on deposits with a primary agricultural credit society, primary credit society, co-operative land mortgage bank or co-operative land development bank. Section 194A(3)(viia)(b) addresses deposits, other than specified time deposits, with a co-operative society engaged in banking. These provisions operate in their own defined fields. They do not warrant reading into the second limb of Section 194A(3)(v) an exclusion that the legislature did not enact.
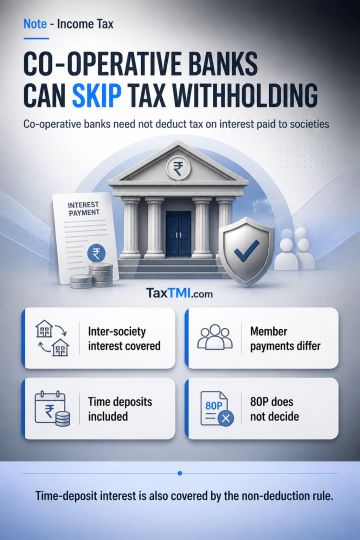
Circular No. 19/2015 distinguishes between member interest and inter co-operative society interest. Paragraph 42.5 explains that, from the stated prospective date, the exemption for interest paid by a co-operative society to its members does not apply to time-deposit interest paid by a co-operative bank to its members. Paragraph 42.7 separately provides: "the existing exemption provided under section 194A(3)(v) of the Income-tax Act from deduction of tax from interest paid by a co-operative society to another co-operative society shall continue to apply to the co-operative bank." It follows that "a co-operative bank shall not be required to deduct tax from the payment of interest on time deposit to a depositor, being a co-operative society."
Under Section 201(1), a person who is required to deduct tax but does not deduct or pay it is deemed to be an assessee in default. Section 201(1A) imposes simple interest at one per cent for every month or part of a month from the date tax was deductible until deduction, and at one and one-half per cent from deduction until actual payment. These consequences presuppose a subsisting statutory duty to deduct.
In 2026 (8) TMI 566 - BOMBAY HIGH COURT, the court held that Section 194A(3)(v) must be read as two independent components. The first component, "paid by a co-operative society (other than a co-operative bank) to a member thereof", denies the member-payment exemption to a co-operative bank. The second, "paid by a co-operative society to any other co-operative society", extends to the inter co-operative society transaction without excluding a co-operative bank.
The court reasoned that a co-operative bank does not cease to possess the legal character of a co-operative society merely because it is licensed to undertake banking business. If the legislature intended to deny the second-limb exemption to co-operative banks, it could have replicated the explicit exclusion used in the first limb. It did not do so. Reading such an exclusion into the second limb would add words to a taxing provision and alter its plain scope.
The resulting rule is transaction-specific. A co-operative bank paying interest to its member is governed by the first limb and does not receive the member-payment exclusion. In contrast, where it pays interest to a depositor that is another co-operative society, including a non-member co-operative society, the second limb applies. The co-operative bank is treated as a co-operative society for that purpose, and Section 194A(1) is excluded.
The court gave decisive relevance to paragraph 42.7 of Circular No. 19/2015. Paragraph 42.5 was confined to the amendment concerning interest on time deposits paid by co-operative banks to their members. It could not be used to decide a case involving interest paid to non-member co-operative societies.
Paragraph 42.7 is expressed in direct and unqualified terms. It preserves the exemption for interest paid by one co-operative society to another and confirms its application to a co-operative bank. Thus, the circular accords with the textual distinction between the two limbs and reinforces that time-deposit interest does not lose the inter co-operative society exemption merely because the payer is a co-operative bank.
The revenue position considered in the ruling treated the threshold and time-deposit provisions applicable to co-operative banks as controlling over the exemption in Section 194A(3)(v). That approach was rejected in relation to payments to another co-operative society. The court held that the second limb of clause (v) is not placed on the same footing as the first limb concerning member deposits. The specific statutory carve-out for payments between co-operative societies remains available because the legislature retained it and the circular expressly confirms it.
The supplied statutory text also contains a separate proviso to Section 194A(3) which imposes a deduction obligation on a co-operative society referred to in clause (v) or clause (viia), where both prescribed conditions are fulfilled: its total sales, gross receipts or turnover exceed fifty crore rupees in the immediately preceding financial year, and the annual interest credited or paid exceeds one lakh rupees for a senior-citizen payee or fifty thousand rupees in any other case. The applicability and effect of this proviso were not determined in the ruling under discussion. Its operation must therefore be examined independently where it is material to the relevant transaction and period.
The court also rejected the attempt to decide the withholding obligation through Section 80P. Section 80P(2)(d) addresses a payee co-operative society's deduction in respect of interest or dividend income derived from investments with another co-operative society. Section 80P(4) limits the application of that section to co-operative banks, subject to stated exceptions. Those provisions operate at the assessment stage in computing the recipient's taxable income.
Section 194A operates at the payment or credit stage and determines the payer's withholding obligation. Eligibility or ineligibility of a recipient for an assessment-stage deduction under Section 80P cannot be used to create a TDS duty where Section 194A(3)(v) itself excludes the transaction from Section 194A(1).
In 2019 (10) TMI 1640 - KERALA HIGH COURT, interest paid by a district co-operative bank to co-operative societies on fixed deposits was held not liable to TDS under Section 194A(3)(v). The conclusion followed the revenue's concession that the payment was from one co-operative society to another. The authority directly supports the inter co-operative society character of the exemption.
2019 (10) TMI 1639 - KERALA HIGH COURT reached the same result for interest paid by a district co-operative bank to a primary agricultural credit society. It treated the transaction as interest paid by one co-operative society to another, thereby taking it outside the TDS requirement. This authority is consistent with the later detailed analysis of the two limbs of Section 194A(3)(v).
2016 (1) TMI 370 - MADRAS HIGH COURT considered whether a meaningful distinction could be drawn between a co-operative bank and a co-operative society engaged in banking business. It found no substantive dichotomy in the connected statutory framework except where Section 194A itself expressly created one. Although that decision dealt with member-deposit issues for an earlier period, its reasoning supports the proposition that the character of a co-operative bank as a co-operative society is not extinguished for every purpose under Section 194A.
A different construction appears in 2015 (4) TMI 374 - BOMBAY HIGH COURT, which treated interest on time deposits with an urban co-operative bank as subject to TDS beyond the threshold considered there. That authority concerned the interaction of time-deposit rules and exemptions in a different setting. The supplied material does not indicate that it examined the distinct second limb of Section 194A(3)(v), paragraph 42.7 of Circular No. 19/2015, or a payment to a non-member co-operative society. The later ruling therefore turns on the specific inter co-operative society statutory language and cannot be reduced to a general time-deposit rule.
Once the second limb of Section 194A(3)(v) applies, no tax is deductible under Section 194A(1). The foundational requirement of Section 201(1), namely that the payer was "required to deduct" tax, is absent. In 2026 (8) TMI 566 - BOMBAY HIGH COURT, the court consequently held that the co-operative bank could not be treated as an assessee in default under Section 201(1) or be subjected to interest under Section 201(1A) for the interest paid to non-member co-operative societies.
Co-operative banks should classify interest payments by the legal status of the depositor rather than by deposit type alone. The first compliance question is whether the depositor is a co-operative society. The second is whether the payment falls within the inter co-operative society limb of Section 194A(3)(v). The depositor's membership or non-membership may be vital in establishing that the dispute concerns the second limb rather than the first, but the crucial statutory feature remains that the recipient is another co-operative society.
Documentation should establish the payer's status as a co-operative society carrying on banking business and the recipient's status as a co-operative society. Deposit records, registration materials, account-opening records and interest-credit schedules should consistently identify the recipient and the nature of the payment. The bank should also preserve a reasoned internal note identifying paragraph 42.7 of Circular No. 19/2015 as the basis for non-deduction, where applicable.
TDS systems should not automatically apply the member time-deposit rule in paragraph 42.5 to deposits held by co-operative societies. Such an approach overlooks the express continuation of the inter co-operative society exemption in paragraph 42.7. At the same time, the separate proviso reproduced in Section 194A(3), where applicable, requires independent verification of its turnover and interest-amount conditions.
In pending or proposed Section 201 proceedings, the defence should focus first on the absence of a duty under Section 194A(1) by reason of Section 194A(3)(v). Arguments concerning the recipient's ultimate tax liability, its eligibility under Section 80P, or its assessment treatment are analytically distinct and do not answer the withholding question.
Full Text:

