Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Benami Property
  • Bill
  • Central Excise
  • Companies Law
  • Customs
  • DGFT
  • FEMA
  • GST
  • GST - States
  • IBC
  • Income Tax
  • Indian Laws
  • Money Laundering
  • SEBI
  • SEZ
  • Service Tax
  • VAT / Sales Tax
Types:
---- All Types ---- ❯
  • ---- All Types ----
  • Act Rules
  • Case Laws
  • Circulars
  • Manuals
  • News
  • Notifications
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Consolidated Show Cause Notices under Sections 73 and 74 and Taxability of School Affiliation Servic...
    Fraudulent Input Tax Credit from Non-Existent Suppliers: Application of Sections 16, 74 and 155 of t...
    Case Laws Money Laundering
    Prolonged Pre-Trial Incarceration and Bail under Section 45 of the Prevention of Money-Laundering Ac...
    Case Laws Income Tax
    Prospective Operation of Section 56(2)(x)(b) in Stamp-Value Difference Cases Involving Immovable Pro...
    Seizure of Cash under Section 67 of the CGST Act and Interest on Illegal Retention
    Case Laws Income Tax
    Disallowance of Salary Expenditure for Allegedly Non-Genuine Services under Section 37
    Case Laws Income Tax
    Fair Market Value of Unquoted Equity Shares Under Section 56(2)(viib) and Rule 11UA
    Refund of Excess IGST Paid on Exports Following Clerical Error in FORM GSTR-3B
    Revocation of Cancellation of GST Registration for Non-Filing of Returns under Section 30 and Rule 2...
    Case Laws Income Tax
    TOLA, Section 149 and the Surviving-Time Test for Reassessment Proceedings
    Case Laws Customs
    Provisional Release of Unseized Imported Food Consignments under the Customs Act, 1962
    Case Laws Customs
    Recovery of Unpaid Anti-Dumping Duty After Self-Assessment Under Section 28 of the Customs Act, 1962
    Project-Wise Anti-Profiteering Methodology in Real Estate under Section 171 of the Central Goods and...
    Case Laws Income Tax
    Retirement Leave Encashment Exemption under Section 10(10AA)(ii) and Retrospective Application of No...
    Transit-State Jurisdiction under GST: Limits on Detention and Penalty in External Inter-State Suppli...
    Post-Facto Shareholder Ratification of Diversion of Preferential Issue Proceeds under the PFUTP Regu...
    Case Laws Income Tax
    Section 195 Withholding on Payments to Non-Residents: Royalty, Fees for Technical Services and Busin...
    Penalty: Scope of "Any Person" under Section 122(1A) of the Central Goods and Services Tax Act, 2017
    Recovery of Corporate Debtor Premises and Proof of Tenancy, Lease or Licence Rights under the Insolv...
    Service of GST Notices through the Common Portal: Statutory Validity and Practical Accessibility
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Notes
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
Case Laws GST
Show AI Summary
School affiliation services fall outside educational exemption without a direct nexus to admissions or examination conduct.
Consolidated show cause notices may combine financial years governed by Sections 73 and 74 where liabilities are segregated period-wise, each component independently meets limitation and notice requirements, the additional ingredients for fraud-based proceedings are satisfied, and no actual prejudice arises. School affiliation and affiliation-form processing charges are independent taxable supplies where they concern institutional eligibility and compliance, rather than directly and immediately relating to student admission or the conduct of examinations. A broad connection with education does not satisfy the educational-services exemption.
Case Laws GST
Show AI Summary
Fraudulent input tax credit requires proof of fictitious supplies, absent goods receipt, and fraud-linked self-assessment, not cancellation alone.
Input tax credit from allegedly non-existent suppliers depends on proof of genuine supply and actual receipt of goods or services, not merely invoices, accounting entries, or banking-channel payments. Section 155 places the burden of establishing ITC eligibility on the claimant. Section 74 requires more than ineligible credit: the wrongful availment must be linked to fraud, wilful misstatement, or suppression to evade tax. Retrospective supplier-registration cancellation is relevant evidence but is not conclusive. A fraud-based notice must disclose facts showing fictitious suppliers, absence of supply, and a basis for inferring the recipient's knowledge or participation.
Case Laws Money Laundering
Show AI Summary
Prolonged pre-trial incarceration may justify conditional PMLA bail when delayed trials make continued detention constitutionally disproportionate.
Section 45 of the Prevention of Money-Laundering Act remains the stringent ordinary bail threshold, requiring prosecutorial opportunity and, on opposition, reasonable grounds to believe that the accused is not guilty and unlikely to offend while on bail. Article 21 nevertheless requires a separate, fact-sensitive inquiry where prolonged pre-trial detention and an unrealistic trial timetable make custody disproportionate. Relevant factors include custody length, trial progress, remaining witnesses, secured documentary evidence, source of delay, predicate-case status, and risks of absconding or witness interference. Conditions such as passport surrender, attendance, non-contact directions, and residence disclosure may safeguard the trial.
Case Laws Income Tax
Show AI Summary
Prospective operation of stamp-value taxation prevents retrospective application where property agreements and substantial payments predate the charging provision.
Section 56(2)(x)(b) applies to immovable property received for inadequate consideration only where its temporal and valuation conditions are satisfied. A stamp-value difference alone does not establish taxability. Where consideration was fixed and substantial payments or contractual performance occurred before the charging provision commenced, later conveyance or registration does not by itself attract the later charge. Agreement-date valuation is available only for covered transactions where consideration was fixed and paid, wholly or partly, through prescribed banking or electronic modes on or before the agreement date. The tax authority must identify the correct statutory basis and provide a meaningful opportunity to respond.
Case Laws GST
Show AI Summary
GST cash seizure limits require statutory relevance and restitutionary interest for unlawfully retained currency following searches.
GST seizure powers cannot be used to take cash as a general investigative measure or security for a possible tax demand. Currency is excluded from goods, and "things" is confined contextually to articles useful or relevant as evidence in GST proceedings. Valid seizure and retention require recorded statutory reasons, procedural compliance and observance of return timelines. Unauthorised retention engages property protections; later return does not cure the deprivation, and accrued interest is restitutionary rather than delayed-refund interest.
Case Laws Income Tax
Show AI Summary
Salary expense genuineness requires proof of actual services, business purpose, and fair testing of adverse third-party statements.
Under Section 37(1), salary expenditure is deductible only where it is actually incurred wholly and exclusively for business purposes and is supported by proof of genuine employment, services rendered, business nexus, and payment. Bank transfers and accounting entries alone are not conclusive. Where a third-party statement is central to an allegation of non-genuine salary, the taxpayer should receive disclosure and a meaningful opportunity to rebut it, including cross-examination where appropriate. A retracted and uncorroborated statement is vulnerable as the sole basis for disallowance.
Case Laws Income Tax
Show AI Summary
Discounted cash flow valuation remains taxpayer-selected under prescribed rules, while tax scrutiny must identify specific valuation-date defects.
The taxpayer may elect a prescribed DCF valuation for unquoted equity shares, and scrutiny of that method does not permit substitution with Net Asset Value merely because it produces a lower fair market value. The Assessing Officer may examine projections, discount rates, terminal assumptions, computations and source data, but rejection requires demonstrably wrong facts, material errors, a wholly erroneous basis or objectively unsupported assumptions. Subsequent financial performance cannot alone invalidate a bona fide DCF valuation; the relevant inquiry remains the reasonableness of valuation-date information.
Case Laws GST
Show AI Summary
Excess IGST on exports remains refundable when later correction triggers automated refund and reconciliation proves duplicate payment.
Refund of excess IGST paid on zero-rated exports may arise where turnover and tax are mistakenly entered under non-zero-rated supplies in FORM GSTR-3B while export invoices and shipping bills are correctly reported in FORM GSTR-1. If the exporter then pays the same IGST in the correct zero-rated field and the automated refund is credited against that later payment, the earlier payment remains a separately identifiable potential excess; its claim is not a repeat request for the same export-tax refund.
Case Laws GST
Show AI Summary
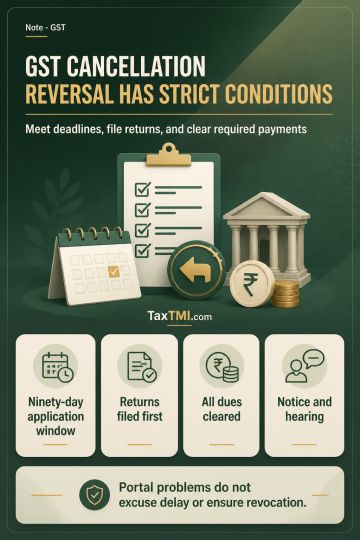
GST registration revocation requires timely application, return compliance, payment of dues, and a reasoned statutory decision.
GST registration revocation after cancellation for return default is a conditional, time-bound process. An application under Section 30 and Rule 23 must ordinarily be filed within ninety days, subject to prescribed extension, and cannot be made until pending returns are filed and tax, interest, penalty and late fee are paid. Portal non-acceptance may permit online or physical submission where technically unavailable, but does not condone delay or ensure revocation. The competent authority must assess statutory eligibility, sufficient grounds and compliance while following notice and hearing requirements before rejection.
Case Laws Income Tax
Show AI Summary
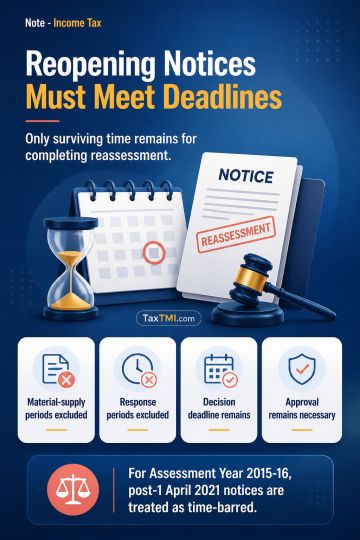
Reassessment limitation under TOLA requires final notices to issue within surviving time and satisfy statutory safeguards.
Reassessment limitation under TOLA is a jurisdictional restraint. Transitional notices issued between 1 April 2021 and 30 June 2021 are treated as Section 148A(b) show-cause notices, but only the surviving time remaining until 30 June 2021 is available for completing the reassessment process. Periods for supply of material and the assessee's response are excluded, but the Section 148A(d) decision, statutory approval and final Section 148 notice must issue within the remaining period. For Assessment Year 2015-16, post-1 April 2021 notices are treated as time-barred.
Case Laws Customs
Show AI Summary
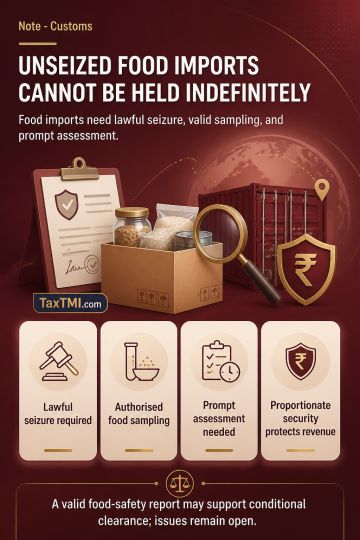
Unseized food consignments cannot face indefinite detention without lawful seizure, valid sampling, and prompt assessment.
Provisional release of an unseized imported food consignment is not mechanically governed by Section 110A, which applies to goods seized under Section 110. Customs may examine, test, verify and reassess imports, but indefinite retention without a seizure memorandum or disclosed reasons connecting the goods with confiscation is not justified. Food sampling should follow the specialised food-safety process through an authorised officer. A valid food-safety report may support conditional clearance, while classification, duty liability, confiscation and adjudication remain open. Revenue may be protected through proportionate security.
Case Laws Customs
Show AI Summary
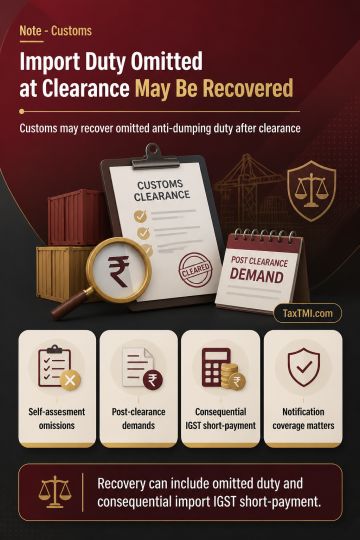
Anti-dumping duty recovery permits post-clearance demands and consequential import IGST where self-assessment omitted an applicable levy.
Unpaid anti-dumping duty omitted during self-assessment may be pursued through the customs recovery procedure without prior appellate modification of the self-assessment. The recovery framework applies to anti-dumping duty through statutory incorporation of provisions concerning assessment, non-levy, short-levy, interest and recovery. Where anti-dumping duty is chargeable, it forms part of the aggregate value used to compute IGST on imports, potentially creating a consequential IGST short-payment. Recovery requires accurate assessment of notification coverage, product, origin, rate, valuation, limitation and procedural safeguards.
Case Laws GST
Show AI Summary
Project-wise anti-profiteering requires actual input tax credit measurement and area-based allocation of benefits to real-estate purchasers.
Real-estate anti-profiteering under Section 171 requires project-level identification of additional input tax credit and allocation of the saving across total project area on a per-square-foot basis. Purchase value may quantify credit attributable to project expenditure, but turnover or collections cannot serve as the allocation basis. The comparison must use pre-GST credit actually availed rather than merely available credit. GST collected on consideration inflated by an undistributed benefit forms part of the amount not passed on and remains distinct from statutory interest.
Case Laws Income Tax
Show AI Summary
Retirement leave encashment exemption applies under the enhanced notified ceiling while preserving non-government employee classification and statutory conditions.
Section 10(10AA)(ii) governs retirement leave-encashment exemption for non-Government employees, subject to the ten-month earned-leave measure, average-salary computation, and the notified monetary ceiling. Notification No. 31/2023 specifies an enhanced ceiling of Rs. 25,00,000, is deemed effective from 1 April 2023, and certifies that retrospective effect causes no adverse effect. The enhanced ceiling is treated as a remedial rationalisation of an existing exemption and may govern pending earlier-period matters, while preserving the distinction between Government and non-Government employees.
Case Laws GST
Show AI Summary
Transit GST jurisdiction limits detention penalties for documented inter-State supplies lacking a local taxable nexus.
Transit-State jurisdiction under GST permits interception, document production, e-way bill verification and authorised physical inspection of goods moving through an intermediate State. It does not, in a pure transit movement, support detention-related penalty for an external inter-State supply where origin and destination lie outside the intercepting State, no tax is payable there, and there is no evidence of diversion, local supply, fictitious or mismatched documents, or mismatch of goods. Cross-empowerment is administrative and does not create an independent territorial taxable nexus.
Case Laws SEBI
Show AI Summary
Shareholder ratification cannot cure preferential-issue fund diversion when disclosed objectives are abandoned, triggering securities-market fraud and disclosure concerns.
Post-facto shareholder approval cannot retrospectively validate diversion of preferential-issue proceeds contrary to issue-specific objects disclosed to shareholders and the market. A special resolution authorises the issue but does not permit unrestricted use of proceeds. Periodic deviation reporting, audit-committee review and utilisation disclosures promote transparency; they do not enable diversion followed by later regularisation. Immediate diversion, inadequate commercial justification and missing documentation may indicate that disclosed objects were not genuinely intended to be performed. Later amendment of corporate objects or shareholder ratification cannot cure a completed securities-market disclosure breach.
Case Laws Income Tax
Show AI Summary
Cross-border software payments require copyright-right, technical-service, and permanent-establishment analysis before withholding obligations are determined under applicable treaties.
Section 195 requires withholding only from a remittance to a non-resident that includes income chargeable in India. For software, royalty depends on transfer of copyright rights, not merely the right to install, access, use, or distribute a copyrighted article under restrictive terms. Where a DTAA is more beneficial, its royalty and FTS definitions control; treaty FTS may require technology to be made available. Amounts that are neither royalty nor FTS require consideration as business profits, ordinarily taxable only where profits are attributable to a permanent establishment. Composite payments require component-wise allocation and analysis.
Case Laws GST
Show AI Summary
Personal GST penalty requires proof that the beneficiary retained benefit and directed a covered invoice or credit transaction.
Section 122(1A) may impose personal GST penalty on a registered or unregistered person only for a covered invoice or input tax credit transaction. Liability requires cumulative proof that the individual retained an identifiable personal benefit and that the transaction was conducted at that person's instance. Directorship, employment, registration, signature authority, or association with the taxable entity neither independently establishes nor excludes liability. Proceedings require transaction-specific and person-specific allegations and findings. The provision operates prospectively for underlying acts or transactions occurring on or after 01.01.2021.
Case Laws IBC
Show AI Summary
Proof of tenancy rights governs insolvency recovery of corporate-debtor premises from occupants lacking enforceable possessory interests.
Where premises form part of the corporate debtor's assets, Sections 18 and 25 of the Insolvency and Bankruptcy Code, 2016 require the resolution professional to take custody, control, preservation and protection measures. An occupant resisting recovery must prove a subsisting tenancy, leasehold interest or enforceable licence through reliable evidence of the parties' intended relationship and its essential terms. Permission to stock goods or conduct limited business activity, prolonged occupation, and business or utility records do not independently create rights in the premises. Section 60(5)(c) supports insolvency jurisdiction over asset-recovery measures connected with the insolvency estate.
Case Laws GST
Show AI Summary
GST portal service requires statutory validity and practical accessibility before ex parte adjudication can fairly proceed.
GST portal service is a statutory method under Section 169, but its use in an ex parte demand proceeding depends on effective accessibility and a meaningful opportunity to reply and be heard. Rule 142 requires electronic DRC-01 and DRC-07 summaries to operate alongside the underlying show-cause notice and reasoned order. Portal placement, complete communication, e-mail transmission, technical reliability and proof of actual access may determine whether service is effective, whether waiver applies, and whether appellate limitation begins.

TMI Notes

Back

All TMI Notes

Showing Results for :
Reset Filters
No Records Found

TMI Notes

Cheque Dishonour, Tax Compliance, and Judicial Reform: Legally Enforceable Debt and Procedural Innovation: Section 138 Jurisprudence

9 December, 2025

Contents
Acts
Plus +
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

Deciphering Legal Judgments: A Comprehensive Analysis of Judgment

Reported as:

2025 (9) TMI 1634 - Supreme Court

Introduction

This decision of the Supreme Court dated 25 September 2025 arises from a criminal appeal challenging an ex parte revisional judgment of a High Court that had acquitted an accused u/s 138 of the Negotiable Instruments Act, 1881 ("NI Act"), reversing concurrent convictions by the trial and appellate courts. The Supreme Court not only restores the conviction but also undertakes a wide-ranging doctrinal and institutional intervention in the law and practice relating to cheque dishonour cases.

The judgment operates on two interlinked planes: first, it clarifies and reinforces the statutory presumptions u/ss 118 and 139 of the NI Act and limits judicial discretion to dilute them; second, it issues far-reaching procedural and administrative directions aimed at addressing the systemic crisis of pendency in Section 138 matters, including revisiting the earlier compounding-cost guidelines in Damodar S. Prabhu. In doing so, it recalibrates the balance between criminal process, civil liability, and judicial efficiency within the specialised regime of cheque dishonour litigation.

Key Legal Issues

1. Scope and effect of presumptions u/ss 118 and 139 NI Act

The central substantive issue concerns whether, once execution of a cheque is admitted, courts are bound to draw presumptions of consideration (Section 118) and of a legally enforceable debt or liability (Section 139), and what is required to rebut those presumptions. This is predominantly an issue of statutory interpretation and proper application of settled precedent.

2. Impact of Section 269SS of the Income Tax Act, 1961 on "legally enforceable debt"

The judgment addresses whether a loan advanced in cash in violation of Section 269SS IT Act (which proscribes certain cash loans above Rs. 20,000) becomes an unenforceable or illegal transaction for the purposes of Section 138 NI Act, thus disabling the statutory presumption u/s 139.

3. Standard of interference in revisional jurisdiction

The Court considers whether a High Court, exercising revisional powers, can overturn concurrent findings of fact of the trial and appellate courts in the absence of perversity or jurisdictional error. This is essentially a procedural and jurisdictional question.

4. Treatment of defence of financial incapacity and "blank cheque" theory

The Court examines the evidentiary burden when the accused disputes the complainant's financial capacity or alleges that a signed blank cheque was given for some collateral purpose, and whether such assertions, without proof, suffice to rebut the presumptions.

5. Nature of Section 138 proceedings and entitlement to probation/compounding

The Court reiterates the quasi-criminal, victim-centric character of Section 138 proceedings and affirms the availability of compounding and the Probation of Offenders Act, 1958 in such cases, clarifying contrary High Court views.

6. Systemic reforms for disposal of Section 138 cases

The Court issues extensive directions on service of summons, online payment mechanisms, complaint formatting, use of digital and evening courts, dashboard monitoring, and modified compounding costs. These are primarily forward-looking procedural and administrative directions grounded in Article 142 jurisprudence.

Detailed Issue-wise Analysis

1. Presumptions u/ss 118 and 139 NI Act

The Court reiterates that once execution of the cheque is admitted, two statutory presumptions automatically arise:

  • u/s 118, that the cheque was drawn for consideration; and
  • u/s 139, that the holder received the cheque in discharge of a legally enforceable debt or liability.

Relying on the three-judge bench in Rangappa v. Sri Mohan 2010 (5) TMI 391 - Supreme Court, the Court notes that earlier restrictive observations in Krishna Janardhan Bhat v. Dattatraya G. Hegde 2008 (1) TMI 827 - Supreme Court have been expressly disapproved. The judgment emphasises that these presumptions are foundational to the legislative intent of Chapter XVII - "to restore the credibility of cheques as a trustworthy substitute for cash payment" and to promote financial discipline.

The presumption u/s 139 is, however, rebuttable. The Court cites Bir Singh v. Mukesh Kumar 2019 (2) TMI 547 - Supreme Court to affirm that the initial onus to rebut this presumption lies squarely on the accused. It clarifies that APS Forex Services (P) Ltd. v. Shakti International Fashion Linkers 2020 (2) TMI 629 - Supreme Court merely holds that where the accused raises a credible challenge to the complainant's financial capacity (particularly in cash loan cases), the burden may shift back to the complainant; it does not negate or dilute the initial presumption u/s 139 for cheques issued in respect of cash loans.

The Court further expresses concern that some trial courts and High Courts are "not giving effect" to these presumptions and are treating Section 138 proceedings "as another civil recovery proceeding" requiring full proof of antecedent debt ab initio. This is categorically labelled as contrary to the "mandate of Parliament." This articulation is aimed at re-aligning lower courts' approach with the statutory design.

2. Interaction with Section 269SS and 271D of the Income Tax Act

The decision specifically disapproves a judgment of the Kerala High Court in P.C. Hari v. Shine Varghese 2025 (7) TMI 1628 - KERALA HIGH COURT, which had held that a cash transaction above Rs. 20,000 in violation of Section 269SS IT Act is not a "legally enforceable debt" for purposes of Section 138 NI Act unless sufficiently explained, thereby denying the benefit of Section 139 presumption to such transactions.

The Supreme Court's reasoning is twofold:

  • Section 269SS, read with Section 271D IT Act, only prescribes a penalty for violation and does not declare such loans illegal, void, or unenforceable.
  • There is no statutory basis to infer that a transaction breaching Section 269SS is void for all purposes; consequently, such violation does not, by itself, render the debt non-enforceable for Section 138 NI Act.

The Court therefore holds that breach of Section 269SS does not rebut the presumptions u/ss 118 and 139. The payee may be exposed to income-tax penalty, but enforceability of the underlying debt through cheque dishonour prosecution remains intact. The conclusion of law in P.C. Hari is expressly set aside. This is a significant clarification that prevents tax-compliance provisions from being used as a shield against cheque dishonour liability.

3. Revisional interference with concurrent findings of fact

The Supreme Court underscores the limited scope of revisional jurisdiction. Relying again on Bir Singh and Southern Sales & Services v. Sauermilch Design 2008 (10) TMI 696 - Supreme Court, it reiterates that a revisional court does not sit as a second appellate forum to reappreciate evidence. Interference is warranted only where there is perversity, patent illegality, or jurisdictional error.

In the present case, both the trial court and the Sessions Court had returned concurrent findings that:

  • Signature on the cheque was admitted;
  • The accused failed to rebut presumptions u/ss 118 and 139;
  • The complainant's version of having arranged funds through personal borrowing and parental assistance was credible.

The High Court, acting in revision, reassessed the evidence, accepted a speculative defence of financial incapacity, and acquitted the accused. The Supreme Court holds that such re-analysis, in the absence of perversity, exceeded revisional limits and was impermissible. This reinforces the finality of concurrent factual findings in cheque dishonour cases subject only to narrow revisional scrutiny.

4. Financial incapacity and "blank cheque for bank loan" defence

The accused's principal defence was that the complainant, earning a modest salary and allegedly indebted, lacked financial capacity to lend Rs. 6 lakhs, and that a signed blank cheque had been given only to enable the complainant to obtain a bank loan.

The Court treats these assertions as wholly unsubstantiated:

  • No documents, no independent witnesses, and no official records (such as income tax or bank statements) were produced to prove the complainant's incapacity. The Court cites Rajaram v. Maruthachalam 2023 (1) TMI 794 - Supreme Court to emphasise that presumptions can indeed be rebutted by such positive evidence, but none was adduced here.
  • Reading the complainant's evidence "in its entirety", the Court finds his explanation - that he partly used funds borrowed himself and partly funds taken from his father, a businessman - sufficient to negate any inference of total incapacity.

On the "blank cheque" theory, the Court is particularly dismissive, describing the High Court's acceptance of it as "unbelievable and absurd." It endorses the Sessions Court's observation that it is "funny" to say a cheque drawn on an account without sufficient funds could be used to secure a bank loan. The Court thereby signals that unsupported, inherently implausible narratives cannot be treated as "probable defence" sufficient to dislodge statutory presumptions.

5. Effect of failure to reply to statutory notice

Invoking Tedhi Singh v. Narayan Dass Mahant 2022 (3) TMI 797 - Supreme Court and MMTC Ltd. v. Medchl Chemicals 2001 (11) TMI 837 - Supreme Court, the Court stresses that:

  • Section 138 proceedings are not civil suits; unless a defence such as lack of financial capacity is set up in the reply to the demand notice, the complainant is not required, at the outset, to prove his financial means.
  • Non-reply to a statutory notice can legitimately lead to an inference that the complainant's version is correct and that the cheque was issued towards discharge of liability.

In this case, the accused neither replied to the notice nor initiated any counter-proceedings to challenge alleged misuse of the cheque, reinforcing the conclusion that his later defences were afterthoughts.

6. Nature of Section 138 offence, compounding, and probation

Drawing from P. Mohanraj v. Shah Brothers Ispat 2021 (3) TMI 94 - Supreme Court, the Court reiterates that Section 138 is "a civil sheep in a criminal wolf's clothing" - formally criminal but substantively aimed at enforcing private civil obligations. It notes that Section 138 is quasi-criminal and compoundable, and refers to a recent decision recognising the primacy of voluntary compromise.

Crucially, the Court affirms that accused persons u/s 138 are entitled to the benefit of the Probation of Offenders Act, 1958, disapproving contrary observations by a Kerala High Court decision. This broadens the remedial and sentencing toolkit available to trial courts, underscoring that the primary object is securing payment and maintaining cheque credibility rather than retribution.

The Court then revisits the compounding guidelines first framed in Damodar S. Prabhu under Article 142, which imposed graded costs (10%, 15%, 20%) to deter delayed compounding. Citing persisting pendency and changed interest rate realities, it "revisits and tweaks" these guidelines by reducing the cost burdens and aligning them with procedural stages:

  • No costs if the cheque amount is paid before defence evidence is recorded;
  • 5% costs if paid after defence evidence but before trial court judgment;
  • 7.5% if paid at revisional/appellate stages before Sessions/High Court;
  • 10% if payment occurs before the Supreme Court.

These modifications seek to incentivise earlier settlements while recognising that excessive cost impositions may be counterproductive in an environment of large backlogs and lower interest rates.

7. Systemic and procedural directions to tackle backlog

Based on alarming pendency data from the National Judicial Data Grid, the Court issues extensive operational directions, many of which go beyond the facts of the instant case. Key aspects include:

  • Expanded modes of service: Mandatory additional service of summons "dasti" by the complainant; use of electronic service (email, mobile, WhatsApp or other messaging apps) under the Bhartiya Nagarik Suraksha Sanhita, 2023 (BNSS) and relevant High Court rules. Complainants must file affidavits verifying the contact details and service; false affidavits may attract sanctions.
  • Pre-structured complaint synopsis: Every Section 138 complaint must include a structured synopsis (party details, cheque particulars, dishonour details, notice particulars, cause of action, pending cases, and reliefs) immediately after the index, standardising pleadings and facilitating quick scrutiny.
  • Cognizance and summons under BNSS: Endorsing a Karnataka High Court view, the Court holds that there is no requirement to issue summons at the pre-cognizance stage u/s 223 BNSS for Section 138 complaints, recognising the NI Act as a special enactment.
  • Summary trial discipline: Reiterating In Re: Expeditious Trial of cases u/s 138 NI Act and drawing from Rajesh Agarwal v. State (2010 (7) TMI 279 - HIGH COURT OF DELHI), the Court directs Magistrates to record clear reasons before converting summary trials into summons trials and permits targeted questioning u/s 251 CrPC / Section 274 BNSS on crucial points (ownership of account, signature, issuance, liability, nature of defence, willingness to compound).
  • Interim compensation: Magistrates are encouraged to invoke Section 143A NI Act at the earliest to order interim deposits where appropriate.
  • Online payment infrastructure: District courts are directed to create secure online payment facilities (QR/UPI) so that accused may discharge the cheque amount at the summons stage itself, enabling immediate compounding/closure upon confirmation.
  • Physical vs digital court listing: Matters should move to physical courts after service of summons to facilitate direct interaction and settlement; digital courts may be used at pre-service stages. Personal appearance exemptions are to be sparingly granted.
  • Evening courts and pecuniary limits: High Courts are advised to fix realistic pecuniary limits for Section 138 cases heard in evening courts; the Delhi example of Rs. 25,000 is criticised as too low.
  • Dashboard monitoring and committees: Principal District Judges in Delhi, Mumbai, and Kolkata must maintain dashboards tracking pendency, disposal, settlements, adjournments, and stage-wise breakup, with monthly reviews and quarterly reports to the High Courts. Chief Justices are requested to constitute administrative committees to oversee Section 138 pendency, explore ADR mechanisms, and deploy experienced Magistrates.

These directions collectively reflect an assertive use of the Court's supervisory and Article 142 powers to engineer systemic reforms in a heavily burdened but relatively standardised category of cases.

Key Holdings and Reasoning

Ratio decidendi

The core binding principles emerging from the judgment include:

  • Once the execution of a cheque is admitted, presumptions u/ss 118 and 139 NI Act must be drawn; they are rebuttable, but the initial burden lies on the accused.
  • Violation of Section 269SS IT Act does not render the underlying cash loan illegal, void, or unenforceable, nor does it, by itself, negate the presumption of a legally enforceable debt u/s 139 NI Act.
  • In revisional jurisdiction, absent perversity or jurisdictional error, High Courts cannot reappreciate evidence to overturn concurrent factual findings in Section 138 cases.
  • An unsubstantiated plea of the complainant's financial incapacity or of a "blank cheque" issued for some collateral purpose is insufficient to rebut statutory presumptions, especially when no reply to the statutory notice is given and no contemporaneous challenge to cheque misuse is made.
  • Section 138 NI Act offences being quasi-criminal and primarily compensatory, the accused are eligible for benefits of the Probation of Offenders Act, 1958.
  • The earlier graded compounding cost scheme in Damodar S. Prabhu is modified in terms of timing and percentage of costs, as detailed in the directions.

Obiter dicta

Much of the systemic, administrative and practice-related guidance - on electronic service, online payment infrastructure, standardised synopses, dashboard monitoring, evening court thresholds, and High Court committees - is clearly prospective and institution-focused. While authoritative and binding under Article 142, these components function more as procedural policy directions than case-specific reasoning. Likewise, the elaboration on Section 138's "civil sheep in criminal wolf's clothing" character, and the broad encouragement of mediation and ADR, is largely obiter, though consistent with prior jurisprudence.

Disposition

The Court allows the appeal, sets aside the High Court's acquittal, and restores the trial and Sessions Court convictions. It restructures compliance by directing payment of Rs. 7,50,000 in fifteen equal monthly instalments of Rs. 50,000. It also mandates implementation of the new guidelines by High Courts and District Courts no later than 1 November 2025.

Conclusion

The judgment significantly strengthens the statutory presumption regime under the NI Act and curtails judicial tendencies to recharacterise Section 138 proceedings as ordinary civil recovery suits. By firmly rejecting the notion that mere breach of tax-compliance provisions, or speculative assertions of financial incapacity, can nullify the presumption of legally enforceable debt, the Court reaffirms the central legislative policy of preserving cheque credibility in commercial transactions.

Simultaneously, the decision acknowledges the "civil" nature of the right being enforced, embraces settlement and probation as legitimate end-points, and recalibrates compounding costs to reflect economic realities. The extensive procedural and administrative directives, especially around service of summons, online payments, summary trial discipline, and case management, are designed to make Section 138 litigation faster, more predictable, and more settlement-oriented.

Future developments are likely to focus on how effectively High Courts and District Courts implement these directions, and whether the combination of presumptive liability, facilitated compounding, and institutional monitoring will succeed in reducing the massive backlog of cheque dishonour cases while preserving due process and fairness for accused persons.

Suggested Alternative Titles

  1. "Reinforcing Presumptions and Recasting Procedure: The Supreme Court's 2025 Roadmap for Section 138 NI Act Litigation"
  2. "Cheque Dishonour, Tax Compliance, and Judicial Reform: A Comprehensive Reassessment of Section 138 Jurisprudence"
  3. "From Civil Sheep to Systemic Overhaul: Statutory Presumptions, Revisional Limits, and Backlog Management under the NI Act"
  4. "Legally Enforceable Debt and Procedural Innovation: The Supreme Court's Framework for Efficient Adjudication of Cheque Bouncing Cases"


Full Text:

2025 (9) TMI 1634 - Supreme Court

Topics

Acts Income Tax