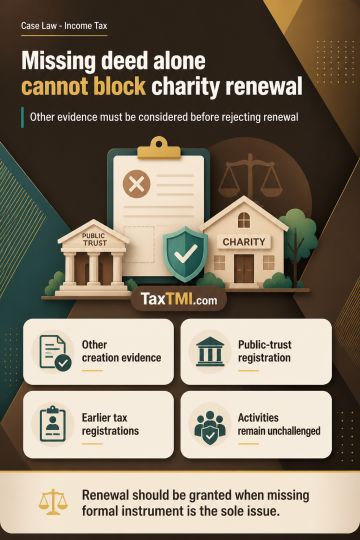
Rule 17A(2) distinguishes institutions created or established under a written instrument from those created otherwise than under an instrument. For the latter, absence of a formal trust deed or memorandum of association cannot alone justify rejecting renewal of charitable registration. The registration authority must assess alternative documentary material, including public-trust registration, the underlying application, prior income-tax registrations and other evidence, to establish the institution's creation and continuing existence. Where no adverse finding concerns charitable or religious objects or the genuineness of activities, rejecting renewal solely for want of a separate formal instrument is unjustified. Registration renewal under section 12AB should be granted in accordance with law.
Rule 17A(2) distinguishes institutions created or established under a written instrument from those created otherwise than under an instrument. For the latter, absence of a formal trust deed or memorandum of association cannot alone justify rejecting renewal of charitable registration. The registration authority must assess alternative documentary material, including public-trust registration, the underlying application, prior income-tax registrations and other evidence, to establish the institution's creation and continuing existence. Where no adverse finding concerns charitable or religious objects or the genuineness of activities, rejecting renewal solely for want of a separate formal instrument is unjustified. Registration renewal under section 12AB should be granted in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI