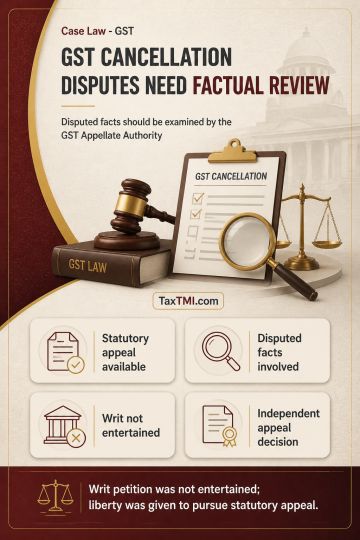
Availability of a statutory appeal against rejection of a GST registration-cancellation application does not bar writ jurisdiction under Article 226, but strongly informs its discretionary exercise. Where the challenge requires resolution of disputed facts and appraisal of the record, the statutory Appellate Authority is the appropriate forum. The writ petition was therefore not entertained, with liberty to pursue the statutory appeal; the Appellate Authority must decide it independently of observations made in the writ proceedings.
Availability of a statutory appeal against rejection of a GST registration-cancellation application does not bar writ jurisdiction under Article 226, but strongly informs its discretionary exercise. Where the challenge requires resolution of disputed facts and appraisal of the record, the statutory Appellate Authority is the appropriate forum. The writ petition was therefore not entertained, with liberty to pursue the statutory appeal; the Appellate Authority must decide it independently of observations made in the writ proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI