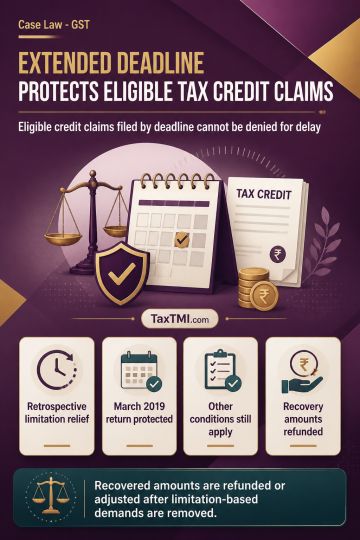
Retrospective extension of the input tax credit limitation under section 16(5) protects eligible registered persons whose belated claims were barred under section 16(4) but fall within the extended period. Input tax credit cannot be denied solely on limitation in such circumstances. The assessment disallowance was quashed to that extent, consequential recovery was restrained, and amounts already recovered were to be refunded or adjusted against future tax liabilities.
Retrospective extension of the input tax credit limitation under section 16(5) protects eligible registered persons whose belated claims were barred under section 16(4) but fall within the extended period. Input tax credit cannot be denied solely on limitation in such circumstances. The assessment disallowance was quashed to that extent, consequential recovery was restrained, and amounts already recovered were to be refunded or adjusted against future tax liabilities.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI