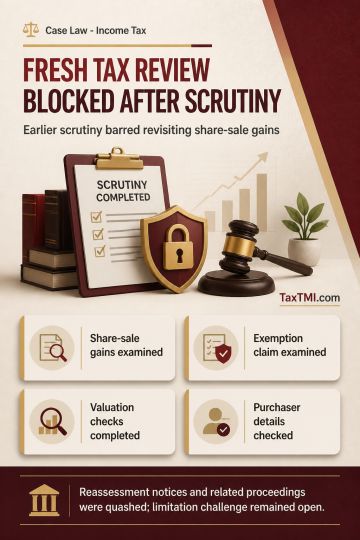
Reassessment cannot revisit capital-gains and share-sale exemption issues already examined and accepted in a scrutiny assessment on the same facts, as doing so amounts to a change of opinion. Detailed inquiries into share valuation, purchaser identity and creditworthiness, transaction genuineness, and the consequential exemption claim establish formation of an opinion even where the assessment order does not address every query. The change-of-opinion principle applies under the revised reassessment procedure, in which a show-cause notice under section 148A(b) performs the function of recorded reopening reasons. The reassessment notices and related proceedings were quashed; the limitation challenge remained open.
Reassessment cannot revisit capital-gains and share-sale exemption issues already examined and accepted in a scrutiny assessment on the same facts, as doing so amounts to a change of opinion. Detailed inquiries into share valuation, purchaser identity and creditworthiness, transaction genuineness, and the consequential exemption claim establish formation of an opinion even where the assessment order does not address every query. The change-of-opinion principle applies under the revised reassessment procedure, in which a show-cause notice under section 148A(b) performs the function of recorded reopening reasons. The reassessment notices and related proceedings were quashed; the limitation challenge remained open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI