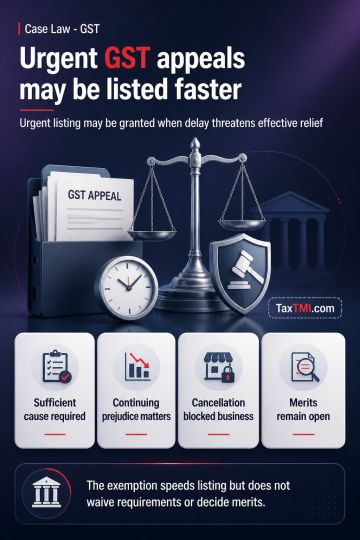
Urgent listing of an appeal against GST registration cancellation may be granted without awaiting ordinary Registry scrutiny where sufficient cause and continuing prejudice are shown. Procedural rules permit exemption from procedural requirements and directions necessary for substantial justice, reflecting the principle that procedure should facilitate adjudication rather than defeat substantive rights through technicality. Cancellation preventing the appellant from conducting its sole business justified limited urgent listing, as delay could make appellate relief ineffective. The exemption applies only to listing and does not waive statutory requirements or determine maintainability or merits, which remain open.
Urgent listing of an appeal against GST registration cancellation may be granted without awaiting ordinary Registry scrutiny where sufficient cause and continuing prejudice are shown. Procedural rules permit exemption from procedural requirements and directions necessary for substantial justice, reflecting the principle that procedure should facilitate adjudication rather than defeat substantive rights through technicality. Cancellation preventing the appellant from conducting its sole business justified limited urgent listing, as delay could make appellate relief ineffective. The exemption applies only to listing and does not waive statutory requirements or determine maintainability or merits, which remain open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI