 TaxTMI





 12 Nov 2026

A client has changed countries. The tax obligations may not have moved with them - or may now exist in two places at once.
Every July, practitioners take the same phone call: "I moved abroad last year, so I'm an NRI now - I only need to show Indian income, right?"
The honest answer is "possibly - let's count." Count the days, check the Indian income, look at the client's position in the new country and map where the family and business really sit. Residential status is a fact-by-fact conclusion for each year, not a label that comes with a new address.
The 2020 change many clients missed
The Finance Act, 2020 quietly but significantly altered the residency rules.
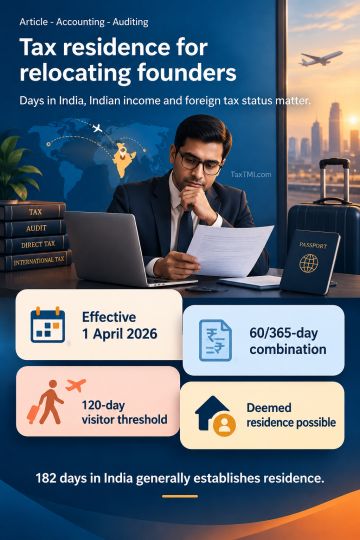
It introduced a provision under which an Indian citizen with substantial Indian income who is not liable to tax in any other country because of domicile or residence may be treated as resident in India. At the same time, for visiting Indian citizens with significant Indian income, the relevant threshold was cut from 182 days to 120 days, together with other conditions.
The intent was unmistakable: moving to a country without personal income tax no longer guarantees an exit from Indian tax. Many globally mobile clients still haven't absorbed it.
Three clients, three risky assumptions
- A founder sells part of her stake and relocates to Dubai, assuming Indian tax no longer touches her.
- A technology professional moves to Singapore but flies home frequently for family occasions and board meetings.
- A businessman returns to India after twenty years abroad, carrying foreign accounts, investments and property.
Each believes their position is clear. Each may have it wrong.
Why status matters so much
India, like many countries, generally taxes residents on worldwide income and non-residents mainly on income arising or received in India. Status therefore determines:
- Whether foreign salary, business income and investment gains are taxable here.
- Which foreign assets and income must be disclosed.
- Which country has the first right to tax under a treaty.
Lesson from history: what counts as home?
Lawmakers and philosophers have long debated what makes a place home - birth, family, property, work or simply where time is spent. Tax treaties settle it through a sequence any village elder would recognise: Where is your permanent home? Where are your family and economic interests? Where do you habitually live? What is your nationality?
A passport records where someone belongs. Tax residence follows where they actually live their life.
India's tests in outline
Under the framework carried into the Income-tax Act, 2025 (in force from 1 April 2026), the broad principles are:
- 182 days - presence in India for 182 days or more in a tax year generally makes an individual resident.
- 60 + 365 days - 60 days in the year plus 365 days across the preceding four years can also confer residence. For Indian citizens and persons of Indian origin visiting India, the 60-day figure is replaced by a higher one, with 120 days applying where Indian income exceeds a specified level.
- Deemed residency - an Indian citizen whose total Indian income exceeds a specified level and who is not liable to tax elsewhere by reason of domicile or residence may be treated as resident.
- RNOR - resident but not ordinarily resident, a transitional status for certain individuals, including many returning NRIs and deemed residents, under which foreign income is largely outside the Indian tax net.
Each test carries conditions that have changed over the years. Clients near any boundary need year-specific advice.
A handful of days can change how an entire year's global income is taxed.
The Residency Compass
Check four directions every year:
- North - Days. Physical presence in India this year and across the previous four.
- East - Indian income. How much arises in India, and does it cross the thresholds that trigger the stricter rules?
- South - The other country. Is the client genuinely liable to tax there by residence or domicile, and can they obtain a tax residency certificate?
- West - Ties. Where are the permanent home, family, business and economic interests - the treaty tie-breaker factors?
In a nutshell
Essence: status turns on days, Indian income, the position in the other country and real-life ties - review all four every single year.
Errors practitioners see most often
1. Treating departure as non-residence. Leaving midway through a year doesn't automatically change that year's status.
2. Too many trips home. Weddings, festivals, business reviews and board meetings push day counts over limits.
3. Moving to a no-tax jurisdiction without considering deemed residency.
4. Overlooking tie-breakers. Where both countries claim residence, the treaty decides - and treaty claims usually require a tax residency certificate.
5. Mixing up FEMA and income-tax status. Residence under foreign exchange law is determined differently; bank accounts and investments must follow FEMA status, for instance by redesignating resident accounts as NRO or opening NRE accounts.
6. Forgetting Indian-source income. Non-residents remain taxable on Indian rent, capital gains, interest and business income, often with TDS.
7. Returning without a plan. Returning residents may become taxable on worldwide income and must disclose foreign assets; the timing of asset sales and RNOR status matter.
8. Omitting foreign asset disclosure. Residents generally must report foreign assets and income in their returns, and non-disclosure can attract severe penalties under the black money law.
Points specific to founders
- Equity and ESOPs - taxation may depend on residence at grant, vesting, exercise and sale.
- Company control - if key decisions for a foreign company are effectively taken from India, the company's own residence may be challenged under place-of-effective-management rules.
- Director residency - certain company-law requirements depend on where directors reside.
- Exit timing - the year in which a large gain falls, and the founder's status that year, can change the outcome dramatically.
For practitioners: an annual residency file for each mobile client
- Day-count working for the current year and the previous four, backed by passport stamps, boarding passes and immigration records.
- Indian income summary by type to test the specified income threshold for the 120-day and deemed-residency rules.
- Foreign residence evidence - tax residency certificate, Form 10F where required and proof of liability to tax abroad.
- FEMA account review - confirm resident accounts have been redesignated and investments reported correctly.
- Disclosure check - for residents and returning residents, foreign assets and income captured in the appropriate schedules of the return.
Illustration
A founder moves to the UAE in August after spending 150 days in India between April and July. She continues to earn substantial Indian rental and dividend income and returns for another 45 days later in the year for board meetings and family events.
- Total days in India: about 195, above 182. She is likely resident for that year despite relocating.
- The following year: if she restricts visits she may become non-resident - but with substantial Indian income and no UAE personal income tax, the 120-day rule and deemed residency need careful testing, and a UAE tax residency certificate should be obtained.
- Actions: plan the timing of any large gains, update bank accounts under FEMA and preserve travel records.
The uncomfortable reality
Many clients take residency advice from friends, social media or a colleague who "did the same thing."
Status depends on exact facts - days, citizenship, income levels, family location, economic ties and the treaty involved. A rule of thumb is not a tax position.
Indicators of success
- Day counts are tracked each year and travel records are kept.
- Status is settled before returns are filed, not afterwards.
- Indian and foreign income are reported correctly for that status.
- Treaty benefits are claimed with proper documentation.
- No unexpected notices arrive about unreported income or foreign assets.
Outlook: the coming decade
More founders and professionals will split their lives between countries. Tax authorities exchange financial data automatically, and the Income-tax Act, 2025 carries forward detailed residency rules. Moving will be easier than ever - and so will detecting residency mistakes.
Immediate actions by role
- Client: list days spent in India for each of the last four years.
- Practitioner: confirm status and treaty position for the current year.
- Company CFO: check whether a founder's location affects where the company is managed.
- Family: keep records of property, bank accounts and investments in each country.
The objection we hear most - and our response
The objection: "I've moved abroad for good and pay tax there. Why should India still have any claim?"
The answer: If a client genuinely lives, works and pays tax abroad, treaties and residency rules usually recognise that - provided the conditions are met and can be proved. India taxes Indian-source income in any event, and the deemed-residency and visiting-citizen rules exist precisely because some people moved on paper while their lives and income stayed here. The protection is real; it just isn't automatic.
Practitioners' FAQ
"Do arrival and departure days count?"
Generally any part of a day spent in India can count. Keep boarding passes and passport records.
"What is a tax residency certificate?"
A certificate issued by the other country's tax authority confirming residence, normally needed to claim treaty benefits.
"How long does RNOR status last?"
It depends on the client's residence history; for many returning NRIs it covers a limited number of years. Plan significant foreign income events within that window, with advice.
Position as at October 2026: India's residency rules, including the 120-day test for certain visiting citizens and deemed residency for stateless-for-tax citizens with Indian income above the specified level, continue under the Income-tax Act, 2025. Foreign asset disclosure rules and the Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015 apply to residents. Thresholds can change - confirm for the specific year.
Pitfalls
- Concluding non-residence without working the day counts and special rules.
- Keeping resident bank accounts after becoming non-resident under FEMA.
- Selling major assets in the wrong year without planning.
- Skipping foreign asset disclosure after returning.
- Relying on generic advice found online.
Half-hour action exercise
Using the client's passport and travel records, fill in:
1. Days in India this tax year and in each of the four previous years.
2. Indian income this year, broken down by type.
3. The client's tax status in the other country, and whether a residency certificate is held.
4. Where the permanent home, family and main business interests are.
Mark every figure that sits close to a threshold. That is exactly where professional advice earns its fee.
Summary for busy professionals
- Residential status decides whether worldwide income is taxable in India and which disclosures apply.
- The tests centre on physical presence (including 182 days), with special rules for visiting citizens (120 days with high Indian income), deemed residency and RNOR.
- Run the Residency Compass every year: days, Indian income, status abroad and ties.
- Typical errors: assuming departure means non-residence, frequent visits, ignoring deemed residency and tie-breakers, confusing FEMA with tax status and missing foreign asset disclosure.
- Founders also need to plan ESOPs, company control and the timing of exits.
A passport shows where someone belongs. Tax residence follows where they actually spend their time and their life.
References
- Finance Act, 2020 (India) - amendments to residency rules (deemed residency and 120-day test).
- Income-tax Act, 2025 (India), provisions on residence. incometax.gov.in
- OECD, Model Tax Convention on Income and on Capital, Article 4 (Resident) and Commentary.
- Foreign Exchange Management Act, 1999 and RBI rules on NRO/NRE accounts. rbi.org.in
- Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015 (India).