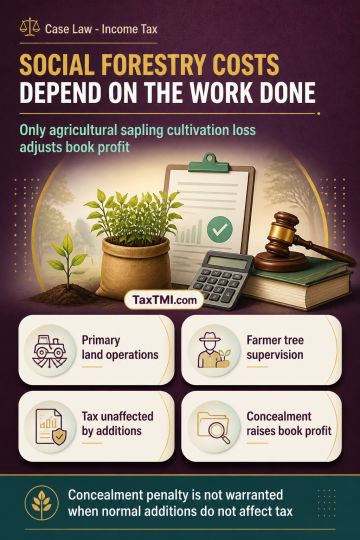
Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
Pre-existing dispute over an outcome-based professional fee may...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigation.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
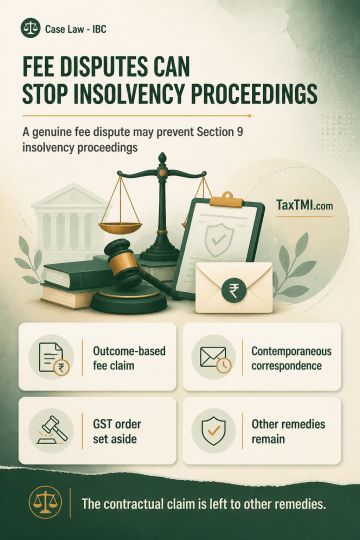
Pre-existing dispute over an outcome-based professional fee may prevent Section 9 insolvency proceedings where contemporaneous correspondence shows a substantive contest about contractual success, fee entitlement, and finality of the underlying GST proceedings. Setting aside of the GST order relevant to fee computation, questions about the capacity in which representation was provided, and the enforceability of relief-linked remuneration under the applicable professional framework may require adjudication outside the limited Section 9 process. A bona fide dispute, rather than a patently feeble defence or later-created contention, leaves the contractual claim to other remedies.
Pre-existing dispute over an outcome-based professional fee may prevent Section 9 insolvency proceedings where contemporaneous correspondence shows a substantive contest about contractual success, fee entitlement, and finality of the underlying GST proceedings. Setting aside of the GST order relevant to fee computation, questions about the capacity in which representation was provided, and the enforceability of relief-linked remuneration under the applicable professional framework may require adjudication outside the limited Section 9 process. A bona fide dispute, rather than a patently feeble defence or later-created contention, leaves the contractual claim to other remedies.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI