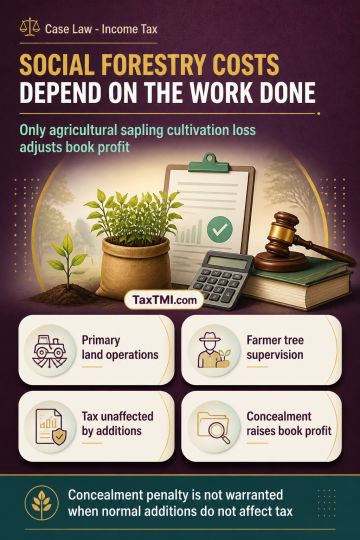
Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
Government recipients of works-contract services must bear and reimburse the differential GST liability caused by the VAT-to-GST transition during contract execution. Reimbursement is limited to the incremental tax attributable to GST, rather than the full tax burden, and depends on verification of the contractor's records and calculations. A writ of mandamus required consideration of the contractor's representation, determination of the verified differential amount, and reimbursement within the stipulated period.
Government recipients of works-contract services must bear and reimburse the differential GST liability caused by the VAT-to-GST transition during contract execution. Reimbursement is limited to the incremental tax attributable to GST, rather than the full tax burden, and depends on verification of the contractor's records and calculations. A writ of mandamus required consideration of the contractor's representation, determination of the verified differential amount, and reimbursement within the stipulated period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI