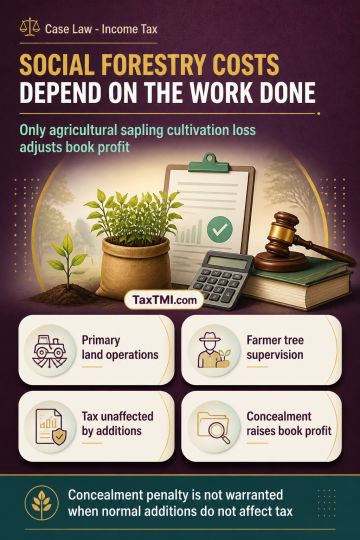
Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
MFN-based treaty benefits under the India-Netherlands DTAA require a notification under section 90(1) for domestic enforcement. Notification No. S.O. 693(E) reduced the Article 11(2) interest tax rate to 10 per cent for beneficial owners but did not incorporate the nil-rate exemptions available under the India-USA or India-Italy DTAAs. Interest on income-tax refunds under section 244A therefore remained taxable at the notified treaty rate, and the nil-rate claim was rejected. Eligible tax deducted at source credit remained available against the refund-interest income.
MFN-based treaty benefits under the India-Netherlands DTAA require a notification under section 90(1) for domestic enforcement. Notification No. S.O. 693(E) reduced the Article 11(2) interest tax rate to 10 per cent for beneficial owners but did not incorporate the nil-rate exemptions available under the India-USA or India-Italy DTAAs. Interest on income-tax refunds under section 244A therefore remained taxable at the notified treaty rate, and the nil-rate claim was rejected. Eligible tax deducted at source credit remained available against the refund-interest income.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI