Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
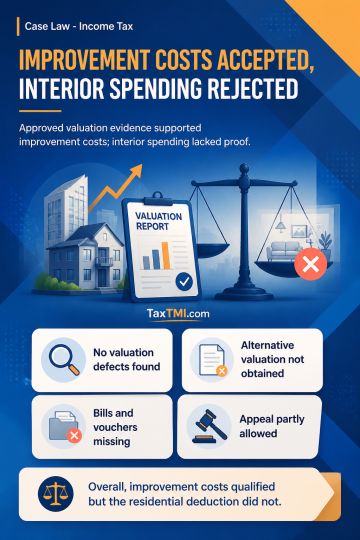
Government-approved Engineer's valuation report on a transferred property's improvement cost required acceptance where the tax authorities accepted the construction year but identified neither defects nor adverse material and did not obtain an alternative valuation under the Act. The claimed cost of improvement was therefore accepted. Interior expenditure on the new residential property remained ineligible for deduction under section 54F because no bills, vouchers, or other evidence substantiated the claim; the disallowance was sustained. The appeal was partly allowed.
Government-approved Engineer's valuation report on a transferred property's improvement cost required acceptance where the tax authorities accepted the construction year but identified neither defects nor adverse material and did not obtain an alternative valuation under the Act. The claimed cost of improvement was therefore accepted. Interior expenditure on the new residential property remained ineligible for deduction under section 54F because no bills, vouchers, or other evidence substantiated the claim; the disallowance was sustained. The appeal was partly allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI