Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
Page of 4868
Press 'Enter' after typing page number.
1 to 20 of 97343 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
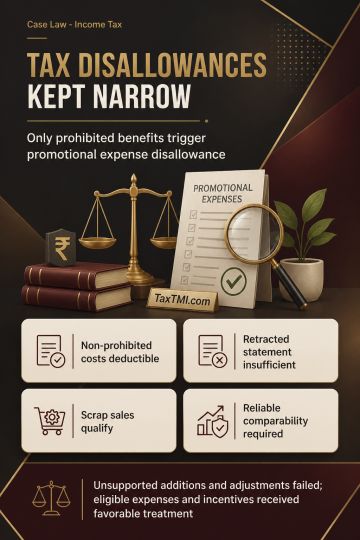
Pharmaceutical sales-promotion expenditure is disallowable only where it directly provides prohibited benefits, such as travel or hotel facilities, to medical practitioners; patient education, professional events and other non-prohibited promotional costs remain deductible. A retracted search statement without independent corroboration cannot support an over-invoicing addition. Manufacturing scrap and empty-container sales qualify for profit-linked deductions, while the industrial excise-refund incentive described is a capital receipt excluded from taxable income and book profit. Transfer-pricing analysis requires reliable functional, temporal and economic comparability; unsupported adjustments for domestic transactions, export pricing, guarantees and genuine intra-group services were rejected. The note also addresses exempt-income expenditure, foreign tax credit attribution, and independent examination of approved in-house research expenditure.
Pharmaceutical sales-promotion expenditure is disallowable only where it directly provides prohibited benefits, such as travel or hotel facilities, to medical practitioners; patient education, professional events and other non-prohibited promotional costs remain deductible. A retracted search statement without independent corroboration cannot support an over-invoicing addition. Manufacturing scrap and empty-container sales qualify for profit-linked deductions, while the industrial excise-refund incentive described is a capital receipt excluded from taxable income and book profit. Transfer-pricing analysis requires reliable functional, temporal and economic comparability; unsupported adjustments for domestic transactions, export pricing, guarantees and genuine intra-group services were rejected. The note also addresses exempt-income expenditure, foreign tax credit attribution, and independent examination of approved in-house research expenditure.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI