Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Bail for alleged fraudulent GST credits depends on trial delay, completed investigation and risks justifying continued detention
    Separate GST penalties against partners may face interim restraint where firms already face proceedings over the same input tax credit.
    GST appeal limitation runs in calendar months, not a fixed day count, when calculating statutory deadlines.
    GST registration cancellation for non-deposit of input tax credit is unjustified where returns are regularly filed; recovery procedures apply.
    Transitional CENVAT credit carried forward through TRAN-1 does not by itself permit CGST recovery proceedings to determine pre-GST admissibility.
    Transitional tax credit for eligible dealers survives incorrect form entries, while previously available eligibility objections cannot be raised on ap...
    Input tax credit allocated to the wrong tax head may be a technical error where no revenue loss arises.
    Reassessment after company-to-LLP conversion requires valid information, not an erroneous non-filer flag or unsupported dividend verification.
    Reassessment after corporate dissolution cannot proceed on the basis of an official website still showing the company as active.
    Brought-forward business losses may offset gains on depreciable business assets despite their treatment as short-term capital gains.
    Partner remuneration from an LLP falls outside presumptive professional taxation and is taxable as business income
    Belated returns and new employee deductions: first-year filing default receives lenient treatment, subject to verification of statutory conditions.
    Reassessment sanction based on the wrong limitation clause and escaped-income threshold is mechanical and invalidates consequential reassessment.
    Reassessment sanction after the extended deadline requires approval from the competent authority and cannot be cured as procedural error.
    Expired TDS default limitation cannot be revived by the extended period, and consequential interest falls with the default order.
    Statutory bonus paid to non-shareholder workers remains deductible when it is not a disguised profit or dividend distribution.
    Penalty notices must identify the applicable concealment or inaccurate particulars charge; an unspecified charge invalidates the penalty.
    Deemed income on agricultural land purchases below stamp duty value does not automatically trigger penalties for income concealment.
    Customs agent penalties for misdeclared imports depend on evidence of involvement and fair consideration of requested cross-examination.
    Circular time limits cannot justify refusal to convert free shipping bills when they exceed statutory authority.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Telegram Get Daily Updates

Reasoned appellate orders are required by natural justice:...

Reasoned GST appellate orders required as unaddressed grounds and procedural objections require fresh adjudication in full.

Contents
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

GST September 26, 2026 Case Laws AT
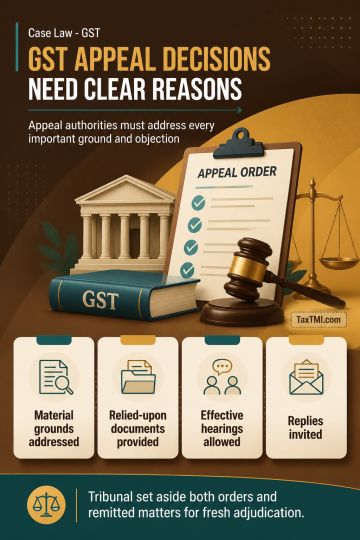
Reasoned appellate orders are required by natural justice: common GST appellate orders confirming demands were invalid because they gave only a general conclusion without addressing material appeal grounds, cited judicial authorities, or each appellant's distinct contentions. The failure to give cogent reasons constituted a failure to exercise appellate jurisdiction. Objections concerning show cause notices, availability of relied-upon documents, and effective personal hearing in original proceedings also required consideration. The Tribunal set aside the appellate and original orders and remitted the matters for fresh adjudication after providing relied-upon documents, allowing replies and effective hearings, and issuing reasoned orders.

Topics

Acts Income Tax