Transitional tax credit for eligible dealers survives incorrect form entries, while previously available eligibility objections cannot be raised on ap...
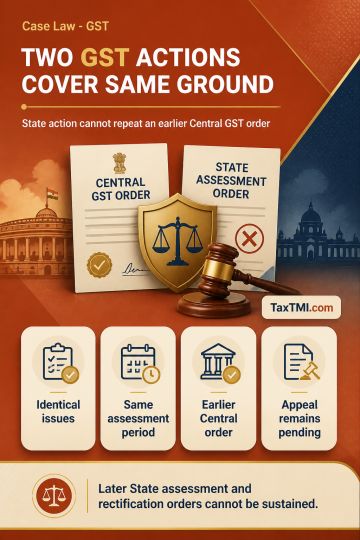
Parallel Central and State GST proceedings concerning identical issues for the same assessment period require avoidance of duplicate adjudication. Where Central GST authorities issue an earlier adjudication order and an appeal against it remains pending, subsequent State GST assessment and rectification orders addressing the same issues and period cannot be sustained. The overlap between the two proceedings makes the later State GST action duplicative of the prior Central GST adjudication.
Parallel Central and State GST proceedings concerning identical issues for the same assessment period require avoidance of duplicate adjudication. Where Central GST authorities issue an earlier adjudication order and an appeal against it remains pending, subsequent State GST assessment and rectification orders addressing the same issues and period cannot be sustained. The overlap between the two proceedings makes the later State GST action duplicative of the prior Central GST adjudication.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI


 Get Daily Updates