Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Benami Property
  • Bill
  • Central Excise
  • Companies Law
  • Customs
  • DGFT
  • FEMA
  • GST
  • GST - States
  • IBC
  • Income Tax
  • Indian Laws
  • Money Laundering
  • SEBI
  • SEZ
  • Service Tax
  • VAT / Sales Tax
Types:
---- All Types ---- ❯
  • ---- All Types ----
  • Act Rules
  • Case Laws
  • Circulars
  • Manuals
  • News
  • Notifications
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Case Laws Income Tax
    TDS on Interest Paid by Co-operative Banks to Non-Member Co-operative Societies under Section 194A(3...
    Input Tax Credit and Supplier Non-Payment: Statutory Limits on Mechanical Reversal Under Section 16(...
    Case Laws Customs
    Appellate Jurisdiction over Goods Imported as Baggage under Sections 129A and 129DD of the Customs A...
    Monetary Limits for Departmental GST Appeals under Section 120 and Circular No. 207/1/2024-GST
    Alleged Re-use of E-Way Bills under Section 129: Evidentiary Burden in Detention Proceedings
    Turnover of Zero-Rated Supply Under Rule 89(4): Invoice Period and Subsequent Physical Export
    Case Laws Income Tax
    Reassessment Proceedings: Speaking Disposal of Objections Before Scrutiny Under Sections 143(2) and ...
    Suppression of Facts under Explanation 2 to Section 74 of the CGST Act in Cases of Ineligible Input ...
    Case Laws Customs
    Classification of Low-Ethoxylated Non-Ionic Fatty Alcohol Ethoxylates under Headings 3402 and 3824
    Case Laws Customs
    Seizure and Detention of Imported Cars under Sections 110, 110A and 124 of the Customs Act, 1962
    Case Laws Companies Law
    Lifting the Corporate Veil Where Promoter Shareholding Is Allegedly Dissipated Despite Judicial Assu...
    Consolidated Show Cause Notices under Sections 73 and 74 and Taxability of School Affiliation Servic...
    Fraudulent Input Tax Credit from Non-Existent Suppliers: Application of Sections 16, 74 and 155 of t...
    Case Laws Money Laundering
    Prolonged Pre-Trial Incarceration and Bail under Section 45 of the Prevention of Money-Laundering Ac...
    Case Laws Income Tax
    Prospective Operation of Section 56(2)(x)(b) in Stamp-Value Difference Cases Involving Immovable Pro...
    Seizure of Cash under Section 67 of the CGST Act and Interest on Illegal Retention
    Case Laws Income Tax
    Disallowance of Salary Expenditure for Allegedly Non-Genuine Services under Section 37
    Case Laws Income Tax
    Fair Market Value of Unquoted Equity Shares Under Section 56(2)(viib) and Rule 11UA
    Refund of Excess IGST Paid on Exports Following Clerical Error in FORM GSTR-3B
    Revocation of Cancellation of GST Registration for Non-Filing of Returns under Section 30 and Rule 2...
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Notes
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
Case Laws Income Tax
Show AI Summary
Inter-co-operative society interest exemption preserves non-deduction by co-operative banks when depositors are co-operative societies under the statutory withholding framework.
Section 194A(3)(v) separately addresses interest paid by a co-operative bank to a member and interest paid by a co-operative society to another co-operative society. The exclusion of co-operative banks is confined to the member-payment limb; a co-operative bank remains a co-operative society for the inter-co-operative society limb. Paragraph 42.7 of Circular No. 19/2015 preserves non-deduction, including time-deposit interest, where the depositor is a co-operative society. Section 80P does not determine this withholding obligation.
Case Laws GST
Show AI Summary
Input tax credit reversal requires evidence linking supplier non-payment to recipient ineligibility and a reasoned statutory inquiry.
Input tax credit under Section 16(2)(c) remains conditional on actual payment of tax to Government, but supplier non-payment or retrospective cancellation cannot by itself justify reversal. The recipient must establish eligibility through transactional evidence, while the proper officer must investigate the particular supply, disclose supplier-default and recovery material, apply the law applicable to the relevant period, and issue a reasoned, notice-bound determination. Supplier recovery status and protection against duplicate collection are material considerations.
Case Laws Customs
Show AI Summary
Baggage-related customs appeals proceed through statutory revision when the jurisdictional exclusion applies to passenger imports.
The first proviso to section 129A(1) excludes Appellate Tribunal jurisdiction over an order under section 128A relating to goods imported or exported as baggage. The decisive issue is the order's connection with baggage, not disputes concerning confiscation, declaration, duty, personal effects, concealment, concession, or penalty. Articles carried by an international passenger in luggage or on the person may constitute baggage. Section 129DD provides revision before the Central Government, ordinarily within three months, subject to a further period on sufficient cause.
Case Laws GST
Show AI Summary
Departmental GST appeal monetary limits regulate officers, while composite orders and proven recurring issues may permit appeals.
Sections 120 and 168 of the Central Goods and Services Tax Act, 2017 make monetary-limit directions binding within the Central tax hierarchy, while they regulate the executive decision to file rather than create an inflexible jurisdictional bar before the Tribunal. In a composite order disposing of multiple appeals or demand notices, the relevant amount is the total disputed tax, interest, penalty or late fee, as applicable. The recurring or interpretative-issue exclusion requires a reasoned, case-specific basis, and Commissioner authorisation does not itself establish compliance with the litigation policy.
Case Laws GST
Show AI Summary
E-way bill re-use allegations require corroborated proof identifying the same goods; vehicle movement alone cannot establish contravention.
Alleged re-use of invoices and e-way bills requires the seizing authority to establish through positive, corroborated evidence that the intercepted goods are the same consignment previously transported under those documents. Toll data, vehicle movements and photographs may justify inquiry but do not alone prove prior delivery, identity of goods or re-use. Where invoices and e-way bills accompany the goods and physical verification shows no discrepancy, the authority must investigate and address any explanation of a different earlier consignment. Cases involving absent or expired transport documents remain factually distinct.
Case Laws GST
Show AI Summary
Zero-rated supply turnover includes export invoices from the refund period when actual export is subsequently established under bond or LUT.
Under Rule 89(4), invoice values for goods invoiced before or at removal for export under bond or Letter of Undertaking may be included in zero-rated turnover for the relevant refund period, although physical export occurs later. The invoice and removal determine period-wise attribution for the refund formula, while actual export remains essential to sustain the claim. Shipping bills, bills of export and related export records must correlate with the export invoices to establish that the goods were ultimately exported. Compliance with valuation, input tax credit eligibility and bond or Letter of Undertaking conditions remains necessary.
Case Laws Income Tax
Show AI Summary
Reassessment objections require speaking disposal and a four-week pause before scrutiny or information requests can begin.
Under the pre-amendment Section 148 framework, reassessment jurisdiction must be resolved before merits-stage scrutiny begins. The Assessing Officer must furnish recorded reasons when requested, permit objections, and decide them through a separate speaking order. A Section 143(2) notice commences scrutiny, while a Section 142(1) notice is a substantive inquiry step; neither may issue before objections are decided. Following rejection, a four-week period from service of the speaking order must be allowed before further reassessment action, preserving an effective opportunity to challenge reopening.
Case Laws GST
Show AI Summary
Suppression of facts requires proof of deliberate tax evasion; ineligible input tax credit alone cannot support enhanced proceedings.
Section 74 permits enhanced tax determination for wrongly availed or utilised input tax credit only where fraud, wilful misstatement, or suppression of facts to evade tax is established. Wrong or ineligible credit is distinct from substantive credit eligibility and cannot, without evidence of deliberate conduct and intent, amount to suppression. Under historical Explanation 2, suppression required either omitted information legally required in prescribed filings or failure to provide information sought in writing; both operate subject to the statutory evasion requirement. Disclosed reconciliations and portal records materially weaken a bare allegation of non-declaration.
Case Laws Customs
Show AI Summary
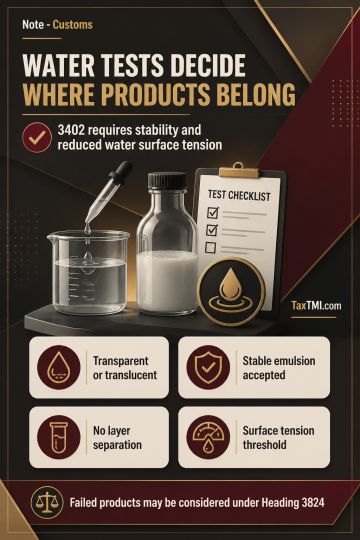
Organic surface-active agent classification requires water solubility and stability; phase-separating low-ethoxylated products fall outside Heading 3402.
Classification of low-ethoxylated non-ionic fatty alcohol ethoxylates under Heading 3402 requires satisfaction of the cumulative water test in Chapter Note 3. At the prescribed concentration, temperature, and standing period, the product must both remain a transparent or translucent liquid, or stable emulsion, without phase separation and reduce water surface tension to the stated threshold. Non-ionic character or surface activity alone is insufficient. Where a low-ethoxylated product separates into layers and fails the solubility and stability requirement, Heading 3824 may be considered after exclusion from Heading 3402.
Case Laws Customs
Show AI Summary
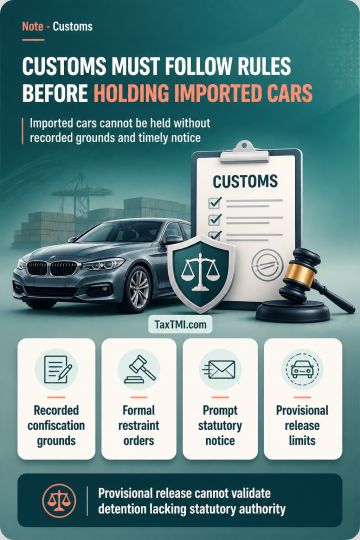
Lawful customs seizure requires recorded confiscation grounds, formal restraint where needed, and timely notice; detention cannot bypass safeguards.
Customs seizure of an imported car requires recorded reason to believe that it is liable to confiscation. A panchnama restraint cannot replace a lawful seizure order, an undertaking where seized goods remain in custody, or a served non-dealing order where seizure is impracticable. Section 110(2) requires prompt notice under Section 124, subject only to the prescribed extension mechanism. Prolonged effective detention cannot postpone those safeguards. Provisional release under Section 110A applies only to goods lawfully seized and cannot validate an earlier detention without statutory authority.
Case Laws Companies Law
Show AI Summary
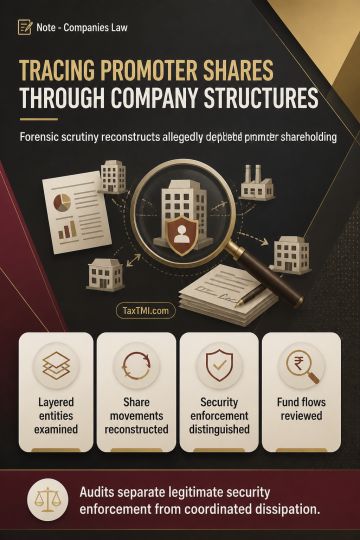
Corporate veil-piercing permits forensic scrutiny in execution where promoter-controlled entities may dissipate shareholding despite judicial assurances.
Corporate veil-piercing in execution is an exceptional response where promoters allegedly use layered entities and securities transactions to deplete shareholding represented as security through judicial assurances. Separate personality remains the rule, and control or ownership alone does not suffice; there must be a nexus between control, misuse of the corporate form, and frustration of enforcement. A forensic audit reconstructs share movements, pledges, sales, financing, approvals, disclosures, and fund flows, distinguishing legitimate enforcement of pre-existing security from coordinated asset dissipation.
Case Laws GST
Show AI Summary
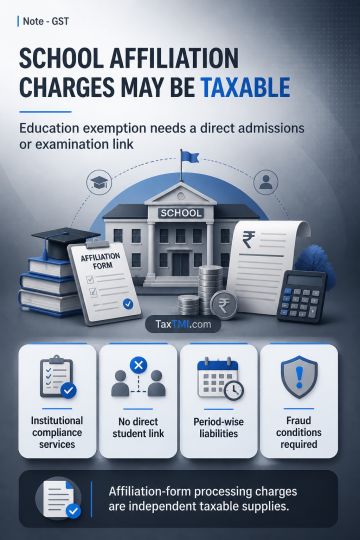
School affiliation services fall outside educational exemption without a direct nexus to admissions or examination conduct.
Consolidated show cause notices may combine financial years governed by Sections 73 and 74 where liabilities are segregated period-wise, each component independently meets limitation and notice requirements, the additional ingredients for fraud-based proceedings are satisfied, and no actual prejudice arises. School affiliation and affiliation-form processing charges are independent taxable supplies where they concern institutional eligibility and compliance, rather than directly and immediately relating to student admission or the conduct of examinations. A broad connection with education does not satisfy the educational-services exemption.
Case Laws GST
Show AI Summary
Fraudulent input tax credit requires proof of fictitious supplies, absent goods receipt, and fraud-linked self-assessment, not cancellation alone.
Input tax credit from allegedly non-existent suppliers depends on proof of genuine supply and actual receipt of goods or services, not merely invoices, accounting entries, or banking-channel payments. Section 155 places the burden of establishing ITC eligibility on the claimant. Section 74 requires more than ineligible credit: the wrongful availment must be linked to fraud, wilful misstatement, or suppression to evade tax. Retrospective supplier-registration cancellation is relevant evidence but is not conclusive. A fraud-based notice must disclose facts showing fictitious suppliers, absence of supply, and a basis for inferring the recipient's knowledge or participation.
Case Laws Money Laundering
Show AI Summary
Prolonged pre-trial incarceration may justify conditional PMLA bail when delayed trials make continued detention constitutionally disproportionate.
Section 45 of the Prevention of Money-Laundering Act remains the stringent ordinary bail threshold, requiring prosecutorial opportunity and, on opposition, reasonable grounds to believe that the accused is not guilty and unlikely to offend while on bail. Article 21 nevertheless requires a separate, fact-sensitive inquiry where prolonged pre-trial detention and an unrealistic trial timetable make custody disproportionate. Relevant factors include custody length, trial progress, remaining witnesses, secured documentary evidence, source of delay, predicate-case status, and risks of absconding or witness interference. Conditions such as passport surrender, attendance, non-contact directions, and residence disclosure may safeguard the trial.
Case Laws Income Tax
Show AI Summary
Prospective operation of stamp-value taxation prevents retrospective application where property agreements and substantial payments predate the charging provision.
Section 56(2)(x)(b) applies to immovable property received for inadequate consideration only where its temporal and valuation conditions are satisfied. A stamp-value difference alone does not establish taxability. Where consideration was fixed and substantial payments or contractual performance occurred before the charging provision commenced, later conveyance or registration does not by itself attract the later charge. Agreement-date valuation is available only for covered transactions where consideration was fixed and paid, wholly or partly, through prescribed banking or electronic modes on or before the agreement date. The tax authority must identify the correct statutory basis and provide a meaningful opportunity to respond.
Case Laws GST
Show AI Summary
GST cash seizure limits require statutory relevance and restitutionary interest for unlawfully retained currency following searches.
GST seizure powers cannot be used to take cash as a general investigative measure or security for a possible tax demand. Currency is excluded from goods, and "things" is confined contextually to articles useful or relevant as evidence in GST proceedings. Valid seizure and retention require recorded statutory reasons, procedural compliance and observance of return timelines. Unauthorised retention engages property protections; later return does not cure the deprivation, and accrued interest is restitutionary rather than delayed-refund interest.
Case Laws Income Tax
Show AI Summary
Salary expense genuineness requires proof of actual services, business purpose, and fair testing of adverse third-party statements.
Under Section 37(1), salary expenditure is deductible only where it is actually incurred wholly and exclusively for business purposes and is supported by proof of genuine employment, services rendered, business nexus, and payment. Bank transfers and accounting entries alone are not conclusive. Where a third-party statement is central to an allegation of non-genuine salary, the taxpayer should receive disclosure and a meaningful opportunity to rebut it, including cross-examination where appropriate. A retracted and uncorroborated statement is vulnerable as the sole basis for disallowance.
Case Laws Income Tax
Show AI Summary
Discounted cash flow valuation remains taxpayer-selected under prescribed rules, while tax scrutiny must identify specific valuation-date defects.
The taxpayer may elect a prescribed DCF valuation for unquoted equity shares, and scrutiny of that method does not permit substitution with Net Asset Value merely because it produces a lower fair market value. The Assessing Officer may examine projections, discount rates, terminal assumptions, computations and source data, but rejection requires demonstrably wrong facts, material errors, a wholly erroneous basis or objectively unsupported assumptions. Subsequent financial performance cannot alone invalidate a bona fide DCF valuation; the relevant inquiry remains the reasonableness of valuation-date information.
Case Laws GST
Show AI Summary
Excess IGST on exports remains refundable when later correction triggers automated refund and reconciliation proves duplicate payment.
Refund of excess IGST paid on zero-rated exports may arise where turnover and tax are mistakenly entered under non-zero-rated supplies in FORM GSTR-3B while export invoices and shipping bills are correctly reported in FORM GSTR-1. If the exporter then pays the same IGST in the correct zero-rated field and the automated refund is credited against that later payment, the earlier payment remains a separately identifiable potential excess; its claim is not a repeat request for the same export-tax refund.
Case Laws GST
Show AI Summary
GST registration revocation requires timely application, return compliance, payment of dues, and a reasoned statutory decision.
GST registration revocation after cancellation for return default is a conditional, time-bound process. An application under Section 30 and Rule 23 must ordinarily be filed within ninety days, subject to prescribed extension, and cannot be made until pending returns are filed and tax, interest, penalty and late fee are paid. Portal non-acceptance may permit online or physical submission where technically unavailable, but does not condone delay or ensure revocation. The competent authority must assess statutory eligibility, sufficient grounds and compliance while following notice and hearing requirements before rejection.

TMI Notes

Back

All TMI Notes

Showing Results for :
Reset Filters
No Records Found

TMI Notes

Back

All TMI Notes

Actionable Claims, Contingent Winnings and Gross Valuation in GST on Gaming Transactions

16 September, 2026

Contents
Notifications
Acts
Rules & Regulations
Plus +
Summary
Note

Note

-

Bookmark

Print

Print

This commentary provides doctrinal analysis and practical insights on the legal issue discussed below. The judgment is analysed in the context of its factual background, issues framed, and conclusions reached by the Court.

2026 (5) TMI 1822 - Supreme Court

Introduction

The GST treatment of stake-based gaming turns on the legal character of the transaction rather than the label applied to the underlying game or the technological form through which it is conducted. The central question is whether a participant who commits money or money's worth to an uncertain outcome acquires an actionable-claim interest within an organised betting and gambling arrangement, and whether the platform operating that arrangement makes a taxable supply.

In 2026 (5) TMI 1822 - Supreme Court, the Supreme Court has held that, for the GST framework, staking upon uncertain outcomes is the defining attribute of betting and gambling. The presence of substantial skill in the underlying activity does not displace that conclusion. The resulting supply of actionable claims is taxable; the stake or statutorily identified deposit forms the valuation base; and the 2023 framework concerning online money gaming and casinos is clarificatory and retrospective in the manner determined by the Court.

This conclusion has consequences well beyond the classification of a platform's retained fee. It addresses the meaning of actionable claim, the scope of the negative-list treatment in Schedule III, the distinction between a deposit and consideration, the identity of the supplier, the validity of Rule 31A, and the effect of the later statutory and valuation provisions on pending matters.

Legal & Statutory Context

The constitutional source of legislative competence is Article 246A. Article 246A(1), notwithstanding Articles 246 and 254, empowers Parliament and State Legislatures to make laws with respect to GST. Clause (2) confers exclusive power on Parliament where the supply occurs in the course of inter-State trade or commerce. The levy under consideration is not characterised as a direct tax on betting or gambling simpliciter. It is a tax on the supply of goods in the form of actionable claims arising from betting and gambling.

The relevant definitions in Section 2 of the CGST Act operate together. Section 2(1) adopts the meaning of "actionable claim" from Section 3 of the Transfer of Property Act, 1882. Section 2(52) defines "goods" as every kind of movable property other than money and securities, but expressly "includes actionable claim". Section 2(31) gives consideration a broad meaning: it includes payment made "in respect of, in response to, or for the inducement of" a supply. Its proviso preserves the character of a deposit only until the supplier applies that deposit as consideration for the supply.

Under Section 7, "supply" includes "all forms of supply of goods or services or both" for consideration in the course or furtherance of business. The words "includes", "all forms of supply" and "such as" are deliberately expansive. The taxable event is therefore supply and is not restricted to a conventional sale or a transfer of title in a pre-existing asset.

Section 9(1) is the charging provision. It levies CGST on all intra-State supplies of goods or services or both, on the value determined under Section 15, at rates notified on the Council's recommendation. The statutory exclusion is contained in Schedule III. Entry 6 treats "actionable claims, other than specified actionable claims" as neither a supply of goods nor a supply of services. Before its substitution, Entry 6 read: "Actionable claims, other than lottery, betting and gambling." Thus, the provision is a negative-list exclusion, not an exemption available to every actionable claim. Claims arising from betting and gambling were expressly outside that exclusion.

The valuation rule in Section 15 begins with transaction value: "the price actually paid or payable" where supplier and recipient are unrelated and price is the sole consideration. Section 15(4) allows valuation to be prescribed where value cannot be determined under Section 15(1), while Section 15(5) authorises prescribed valuation for notified supplies notwithstanding sub-sections (1) and (4).

Interpretative Issues

Skill, chance and the meaning of betting and gambling

The principal interpretative contest was whether a game predominantly involving skill can become betting and gambling merely because it is played for stakes. The Court rejected the proposition that only a game of chance can produce a taxable betting-and-gambling actionable claim. Its test is transactional: a person stakes money or money's worth upon an uncertain future outcome in the expectation of gain. Skill may affect a participant's prospects, but it does not remove the uncertainty inherent in the outcome or the stake-based character of the transaction.

The phrase "chance to win" in Rule 31A(3) was construed accordingly. It does not mean that the Rule is limited to a game of chance in the jurisprudential skill-versus-chance sense. It describes the contingent opportunity acquired on committing a stake to the organised arrangement.

Whether an actionable claim exists

Section 3 of the Transfer of Property Act defines an actionable claim, insofar as material, as a claim to a debt or to a beneficial interest in movable property not in the claimant's actual or constructive possession, which civil courts recognise as affording grounds for relief; the interest may be "existent, accruing, conditional or contingent". The Court applied the beneficial-interest limb to pooled stakes and contingent winnings.

Three consequences follow. First, pooled funds are movable property. Secondly, on staking, each participant acquires a contingent beneficial interest in the pool; gameplay identifies whose contingent interest matures. Thirdly, the participant's lack of actual or constructive possession is established where the platform controls participation, pooling, gameplay, outcome declaration, withdrawals and payout. The right is not a mere expectation detached from property; it is a conditional interest in an identifiable winnings structure.

Deposit, entrustment and consideration

A payment may initially be a deposit, but the statutory proviso to Section 2(31) ceases to protect that character once it is appropriated as consideration. The relevant point is the commitment of funds to gameplay. Once money is appropriated towards participation, the participant cannot treat it as an unrestricted and freely reclaimable balance. The Court therefore rejected characterisation of committed stake amounts as a mere entrustment or continuing refundable deposit.

As participation is conditional on the stake, the stake has the direct nexus required by Section 2(31): it is paid "in respect of", "in response to" and "for the inducement of" the actionable-claim supply. The value question cannot consequently be answered by looking only at the platform's eventual retained commission.

Detailed Commentary & Analysis

Taxability and the limited negative-list exclusion

The statutory architecture produces a direct chain of analysis. An actionable claim is included in goods by Section 2(52). Supply is broadly defined by Section 7. Section 9(1) charges tax on the value determined under Section 15. Entry 6 of Schedule III withholds the non-supply treatment from betting and gambling claims. The combined effect is that actionable claims arising from betting and gambling remain within the taxable field.

The Court also held that a supply need not be an assignment or transfer of a pre-existing actionable claim. In an organised gaming structure, the platform creates and administers the conditions under which contingent actionable-claim interests arise. GST's supply-based design does not require importing transfer formalities applicable to assignment of actionable claims under property law.

Platform as supplier

A platform is not treated as a neutral intermediary merely because participants compete with one another. Where it sets the rules, receives and pools funds, algorithmically matches participants, governs access, controls the transactional architecture, determines the outcome under its framework and administers payouts, it creates and supplies the actionable-claim interest. There is no independently negotiated supply inter se between anonymous participants. The platform is therefore the supplier for purposes of the charging framework.

The later proviso to Section 2(105) reinforces this conclusion by deeming a person who organises or arranges supply of specified actionable claims, including the owner, operator or manager of a digital platform, to be the supplier. The Court held that this later deeming provision did not create the original taxable event; it gave specificity to an already taxable structure.

Valuation: gross stake and not net retained revenue

The Court distinguished a tax on supply from a tax on income or profit. The fact that winnings are later distributed, or that the operator retains only a platform fee, does not by itself reduce the value of the supply. Section 15 contains specified exclusions, including qualifying discounts under Section 15(3), but contains no exclusion for prize pools, winnings or payouts. Gross valuation is thus the statutory norm unless the Act or applicable Rules authorise a deduction.

For the earlier framework, Rule 31A states that the value of supply of an actionable claim in the form of a chance to win in betting, gambling or horse racing in a race club "shall be 100% of the face value of the bet or the amount paid into the totalizator." The disjunctive word "or" separates betting, gambling and horse racing in a race club; the Rule is not confined to race-club transactions. It is a machinery provision that standardises valuation and does not create a new levy.

For online gaming, Rule 31B provides that value is "the total amount paid or payable to or deposited with the supplier" by or for the player, in money, money's worth or virtual digital assets. The proviso denies a deduction merely because an amount is returned or refunded. The explanatory treatment, as recognised in the judgment, prevents redeployed winnings from being treated as a fresh deposit where they are reused without withdrawal. Thus, the measure attaches to funds entering the gaming ecosystem, rather than repeatedly taxing every subsequent deployment of the same winnings.

Rates and the relevant statutory periods

For the period considered from 1 July 2017 to 24 January 2018, the Court held that the residuary entry in Notification No. 1/2017-Central Tax (Rate) applied: Entry 453 covered goods not specified in the other schedules and prescribed 9% CGST. From 25 January 2018, Notification No. 6/2018-Central Tax (Rate) inserted Entry 229 in Schedule IV, prescribing 14% CGST for an "Actionable claim in the form of chance to win in betting, gambling, or horse racing in race club." The absence of a distinct HSN entry was held not to defeat the levy, since classification mechanics cannot override a taxability and rate prescription otherwise validly made under the Act.

Judicial / Administrative Perspective

The judgment draws doctrinal support from a Constitution Bench authority which recognised lottery tickets as actionable claims, movable property and goods in the wider sense. That authority is significant because it confirms that a contingent right to a prize can be proprietary even though it is incorporeal and conditional.

A separate GST authority concerning lottery taxation was applied to sustain Parliament's inclusion of actionable claims within "goods" under Section 2(52). Its relevance lies in the conclusion that the inclusive constitutional meaning of goods does not prevent statutory inclusion of actionable claims for GST purposes.

The Court also relied on the established supply-centric understanding of GST: the regime marks a departure from the earlier sale-and-transfer model and permits taxation of modern commercial arrangements not reducible to a traditional sale of goods. This answers the objection that there was no transfer of a pre-existing claim.

On valuation, the judgment applies the settled distinction between the subject of a levy and its measure. A measure need not replicate the taxable event in every respect; it must bear a reasonable nexus to it. The full stake or deposit validly bears that nexus because entry into the actionable-claim arrangement depends upon it.

Two further doctrinal lines are material. First, dismissal of a special leave petition by an unreasoned order does not itself create a binding declaration of law. Earlier non-speaking dismissals involving skill-based games therefore did not foreclose determination of the GST issue. Secondly, a subsequent amendment may operate retrospectively where, in substance, it clarifies, explains or standardises the pre-existing law rather than imposes a new burden. Applying that doctrine, the Court treated the 2023 changes as explanatory and clarificatory.

Administrative classification under service-rate material cannot alter the statutory character of a transaction. A service classification may apply where a platform merely offers access to a game without stake-based contingent rights. It cannot prevail where the transaction, in substance, is a supply of actionable claims arising from betting and gambling.

Implications & Observations

The 2023 definitions expressly cover "online money gaming" where players pay or deposit money or money's worth, including virtual digital assets, in the expectation of winning money or money's worth, "whether or not" outcome or performance is based on skill, chance or both, and whether permissible under any other law. The amendment correspondingly defines "specified actionable claim" to include betting, casinos, gambling, horse racing, lottery and online money gaming.

The Court's conclusion on retrospectivity is consequential. The amendments to Entry 6 of Schedule III and the insertion of Rules 31B and 31C do not, in the Court's view, create a fresh levy or a new taxable event. They provide a more detailed valuation and collection mechanism for an existing taxable supply. Pending show-cause notices, adjudication proceedings and consequential demands concerning online gaming and fantasy sports are therefore to be determined under Rule 31B in accordance with that conclusion.

Notification No. 49/2023-Central Tax identifies, under Section 15(5), supply of online money gaming, online gaming other than online money gaming, and actionable claims in casinos for special valuation treatment. Its operative commencement is 1 October 2023. The judgment nevertheless holds the relevant 2023 statutory and Rule changes clarificatory in operation, while retaining the statutory distinction between the general Rule 31A framework and the later specialised machinery.

For casinos, the Court rejected gross gaming revenue or net retained revenue as the sole taxable base. Rule 31C governs the ultimate valuation measure, linked to amounts paid for chips, tokens, coins, tickets or participation. Where assessments had been reconstructed through best-judgment methods because reliable contemporaneous records were unavailable, the factual correctness of computation, assumptions and allocations remains open before the adjudicating authority, but must be tested against Rule 31C.

From a compliance and litigation perspective, operators must preserve an auditable trail of deposits, appropriation towards gameplay, withdrawals, refunds, winnings redeployed without withdrawal, platform terms, game-entry records and payout data. The character of a sum before and after appropriation is central. A mere description as wallet balance, deposit, prize pool or platform fee will not control the legal analysis.

The judgment restored the challenged notices in the appeals before it and directed that affected taxpayers be permitted to submit replies within eight weeks of receipt of the judgment, followed by adjudication within twelve weeks. It also preserved factual and legal submissions before the competent authority. The broader lesson is that constitutional challenges to the levy do not eliminate the need for fact-specific contest on valuation, deposit flows, computation and record-based quantification.

Concluding Remarks

The governing proposition is that GST applies to the supply of actionable claims arising from betting and gambling, not to the abstract act of playing a game. Yet, where monetary stakes are committed to uncertain outcomes, an otherwise skill-based format does not remain outside the taxable conception of betting and gambling for GST purposes. Participants obtain contingent beneficial interests in pooled movable property; the platform that creates and controls that organised structure supplies the actionable claim; and stake-based consideration enters the statutory valuation mechanism.

Schedule III does not exempt such claims. Rather, it excludes from non-supply treatment the claims arising from betting and gambling. Rule 31A validly prescribed full face-value valuation in the earlier framework, while Rules 31B and 31C supply specialised mechanisms for online gaming and casinos. The 2023 amendments, having been held clarificatory and retrospective, govern pending matters in the manner laid down by 2026 (5) TMI 1822 - Supreme Court.


Full Text:

2026 (5) TMI 1822 - Supreme Court

Topics

Acts Income Tax