Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Benami Property
  • Bill
  • Central Excise
  • Companies Law
  • Customs
  • DGFT
  • FEMA
  • GST
  • GST - States
  • IBC
  • Income Tax
  • Indian Laws
  • Money Laundering
  • SEBI
  • SEZ
  • Service Tax
  • VAT / Sales Tax
Types:
---- All Types ---- ❯
  • ---- All Types ----
  • Act Rules
  • Case Laws
  • Circulars
  • Manuals
  • News
  • Notifications
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Suppression of Facts under Explanation 2 to Section 74 of the CGST Act in Cases of Ineligible Input ...
    Case Laws Customs
    Classification of Low-Ethoxylated Non-Ionic Fatty Alcohol Ethoxylates under Headings 3402 and 3824
    Case Laws Customs
    Seizure and Detention of Imported Cars under Sections 110, 110A and 124 of the Customs Act, 1962
    Case Laws Companies Law
    Lifting the Corporate Veil Where Promoter Shareholding Is Allegedly Dissipated Despite Judicial Assu...
    Consolidated Show Cause Notices under Sections 73 and 74 and Taxability of School Affiliation Servic...
    Fraudulent Input Tax Credit from Non-Existent Suppliers: Application of Sections 16, 74 and 155 of t...
    Case Laws Money Laundering
    Prolonged Pre-Trial Incarceration and Bail under Section 45 of the Prevention of Money-Laundering Ac...
    Case Laws Income Tax
    Prospective Operation of Section 56(2)(x)(b) in Stamp-Value Difference Cases Involving Immovable Pro...
    Seizure of Cash under Section 67 of the CGST Act and Interest on Illegal Retention
    Case Laws Income Tax
    Disallowance of Salary Expenditure for Allegedly Non-Genuine Services under Section 37
    Case Laws Income Tax
    Fair Market Value of Unquoted Equity Shares Under Section 56(2)(viib) and Rule 11UA
    Refund of Excess IGST Paid on Exports Following Clerical Error in FORM GSTR-3B
    Revocation of Cancellation of GST Registration for Non-Filing of Returns under Section 30 and Rule 2...
    Case Laws Income Tax
    TOLA, Section 149 and the Surviving-Time Test for Reassessment Proceedings
    Case Laws Customs
    Provisional Release of Unseized Imported Food Consignments under the Customs Act, 1962
    Case Laws Customs
    Recovery of Unpaid Anti-Dumping Duty After Self-Assessment Under Section 28 of the Customs Act, 1962
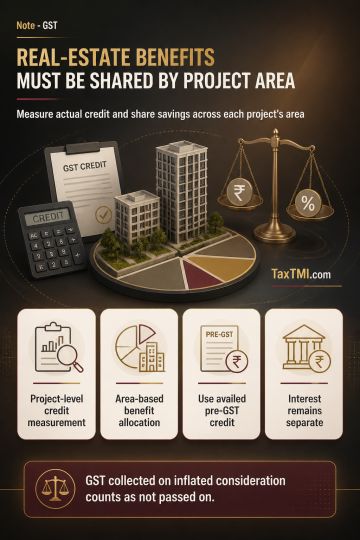
    Project-Wise Anti-Profiteering Methodology in Real Estate under Section 171 of the Central Goods and...
    Case Laws Income Tax
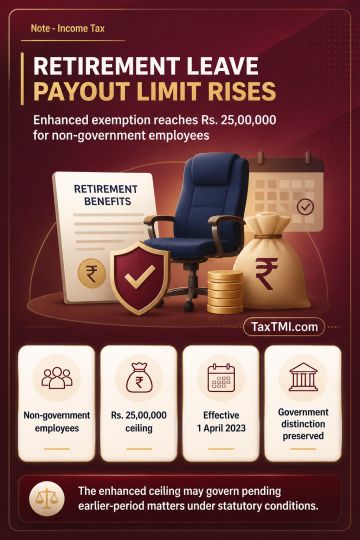
    Retirement Leave Encashment Exemption under Section 10(10AA)(ii) and Retrospective Application of No...
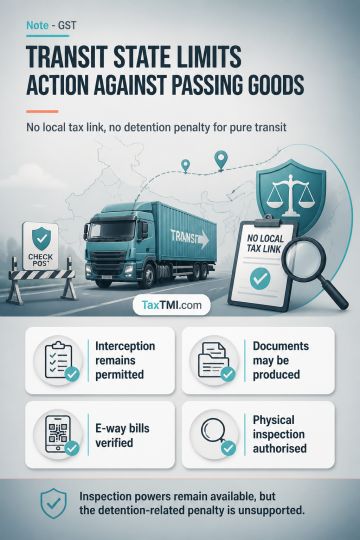
    Transit-State Jurisdiction under GST: Limits on Detention and Penalty in External Inter-State Suppli...
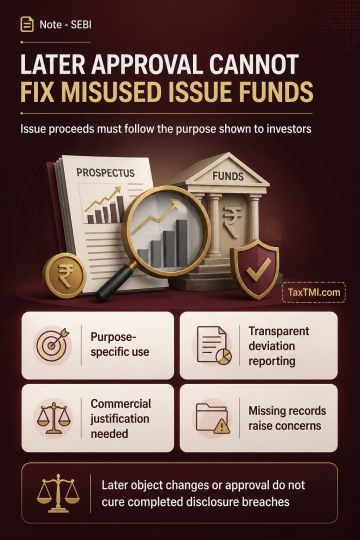
    Post-Facto Shareholder Ratification of Diversion of Preferential Issue Proceeds under the PFUTP Regu...
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Notes
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
Case Laws GST
Show AI Summary
Suppression of facts requires proof of deliberate tax evasion; ineligible input tax credit alone cannot support enhanced proceedings.
Section 74 permits enhanced tax determination for wrongly availed or utilised input tax credit only where fraud, wilful misstatement, or suppression of facts to evade tax is established. Wrong or ineligible credit is distinct from substantive credit eligibility and cannot, without evidence of deliberate conduct and intent, amount to suppression. Under historical Explanation 2, suppression required either omitted information legally required in prescribed filings or failure to provide information sought in writing; both operate subject to the statutory evasion requirement. Disclosed reconciliations and portal records materially weaken a bare allegation of non-declaration.
Case Laws Customs
Show AI Summary
Organic surface-active agent classification requires water solubility and stability; phase-separating low-ethoxylated products fall outside Heading 3402.
Classification of low-ethoxylated non-ionic fatty alcohol ethoxylates under Heading 3402 requires satisfaction of the cumulative water test in Chapter Note 3. At the prescribed concentration, temperature, and standing period, the product must both remain a transparent or translucent liquid, or stable emulsion, without phase separation and reduce water surface tension to the stated threshold. Non-ionic character or surface activity alone is insufficient. Where a low-ethoxylated product separates into layers and fails the solubility and stability requirement, Heading 3824 may be considered after exclusion from Heading 3402.
Case Laws Customs
Show AI Summary
Lawful customs seizure requires recorded confiscation grounds, formal restraint where needed, and timely notice; detention cannot bypass safeguards.
Customs seizure of an imported car requires recorded reason to believe that it is liable to confiscation. A panchnama restraint cannot replace a lawful seizure order, an undertaking where seized goods remain in custody, or a served non-dealing order where seizure is impracticable. Section 110(2) requires prompt notice under Section 124, subject only to the prescribed extension mechanism. Prolonged effective detention cannot postpone those safeguards. Provisional release under Section 110A applies only to goods lawfully seized and cannot validate an earlier detention without statutory authority.
Case Laws Companies Law
Show AI Summary
Corporate veil-piercing permits forensic scrutiny in execution where promoter-controlled entities may dissipate shareholding despite judicial assurances.
Corporate veil-piercing in execution is an exceptional response where promoters allegedly use layered entities and securities transactions to deplete shareholding represented as security through judicial assurances. Separate personality remains the rule, and control or ownership alone does not suffice; there must be a nexus between control, misuse of the corporate form, and frustration of enforcement. A forensic audit reconstructs share movements, pledges, sales, financing, approvals, disclosures, and fund flows, distinguishing legitimate enforcement of pre-existing security from coordinated asset dissipation.
Case Laws GST
Show AI Summary
School affiliation services fall outside educational exemption without a direct nexus to admissions or examination conduct.
Consolidated show cause notices may combine financial years governed by Sections 73 and 74 where liabilities are segregated period-wise, each component independently meets limitation and notice requirements, the additional ingredients for fraud-based proceedings are satisfied, and no actual prejudice arises. School affiliation and affiliation-form processing charges are independent taxable supplies where they concern institutional eligibility and compliance, rather than directly and immediately relating to student admission or the conduct of examinations. A broad connection with education does not satisfy the educational-services exemption.
Case Laws GST
Show AI Summary
Fraudulent input tax credit requires proof of fictitious supplies, absent goods receipt, and fraud-linked self-assessment, not cancellation alone.
Input tax credit from allegedly non-existent suppliers depends on proof of genuine supply and actual receipt of goods or services, not merely invoices, accounting entries, or banking-channel payments. Section 155 places the burden of establishing ITC eligibility on the claimant. Section 74 requires more than ineligible credit: the wrongful availment must be linked to fraud, wilful misstatement, or suppression to evade tax. Retrospective supplier-registration cancellation is relevant evidence but is not conclusive. A fraud-based notice must disclose facts showing fictitious suppliers, absence of supply, and a basis for inferring the recipient's knowledge or participation.
Case Laws Money Laundering
Show AI Summary
Prolonged pre-trial incarceration may justify conditional PMLA bail when delayed trials make continued detention constitutionally disproportionate.
Section 45 of the Prevention of Money-Laundering Act remains the stringent ordinary bail threshold, requiring prosecutorial opportunity and, on opposition, reasonable grounds to believe that the accused is not guilty and unlikely to offend while on bail. Article 21 nevertheless requires a separate, fact-sensitive inquiry where prolonged pre-trial detention and an unrealistic trial timetable make custody disproportionate. Relevant factors include custody length, trial progress, remaining witnesses, secured documentary evidence, source of delay, predicate-case status, and risks of absconding or witness interference. Conditions such as passport surrender, attendance, non-contact directions, and residence disclosure may safeguard the trial.
Case Laws Income Tax
Show AI Summary
Prospective operation of stamp-value taxation prevents retrospective application where property agreements and substantial payments predate the charging provision.
Section 56(2)(x)(b) applies to immovable property received for inadequate consideration only where its temporal and valuation conditions are satisfied. A stamp-value difference alone does not establish taxability. Where consideration was fixed and substantial payments or contractual performance occurred before the charging provision commenced, later conveyance or registration does not by itself attract the later charge. Agreement-date valuation is available only for covered transactions where consideration was fixed and paid, wholly or partly, through prescribed banking or electronic modes on or before the agreement date. The tax authority must identify the correct statutory basis and provide a meaningful opportunity to respond.
Case Laws GST
Show AI Summary
GST cash seizure limits require statutory relevance and restitutionary interest for unlawfully retained currency following searches.
GST seizure powers cannot be used to take cash as a general investigative measure or security for a possible tax demand. Currency is excluded from goods, and "things" is confined contextually to articles useful or relevant as evidence in GST proceedings. Valid seizure and retention require recorded statutory reasons, procedural compliance and observance of return timelines. Unauthorised retention engages property protections; later return does not cure the deprivation, and accrued interest is restitutionary rather than delayed-refund interest.
Case Laws Income Tax
Show AI Summary
Salary expense genuineness requires proof of actual services, business purpose, and fair testing of adverse third-party statements.
Under Section 37(1), salary expenditure is deductible only where it is actually incurred wholly and exclusively for business purposes and is supported by proof of genuine employment, services rendered, business nexus, and payment. Bank transfers and accounting entries alone are not conclusive. Where a third-party statement is central to an allegation of non-genuine salary, the taxpayer should receive disclosure and a meaningful opportunity to rebut it, including cross-examination where appropriate. A retracted and uncorroborated statement is vulnerable as the sole basis for disallowance.
Case Laws Income Tax
Show AI Summary
Discounted cash flow valuation remains taxpayer-selected under prescribed rules, while tax scrutiny must identify specific valuation-date defects.
The taxpayer may elect a prescribed DCF valuation for unquoted equity shares, and scrutiny of that method does not permit substitution with Net Asset Value merely because it produces a lower fair market value. The Assessing Officer may examine projections, discount rates, terminal assumptions, computations and source data, but rejection requires demonstrably wrong facts, material errors, a wholly erroneous basis or objectively unsupported assumptions. Subsequent financial performance cannot alone invalidate a bona fide DCF valuation; the relevant inquiry remains the reasonableness of valuation-date information.
Case Laws GST
Show AI Summary
Excess IGST on exports remains refundable when later correction triggers automated refund and reconciliation proves duplicate payment.
Refund of excess IGST paid on zero-rated exports may arise where turnover and tax are mistakenly entered under non-zero-rated supplies in FORM GSTR-3B while export invoices and shipping bills are correctly reported in FORM GSTR-1. If the exporter then pays the same IGST in the correct zero-rated field and the automated refund is credited against that later payment, the earlier payment remains a separately identifiable potential excess; its claim is not a repeat request for the same export-tax refund.
Case Laws GST
Show AI Summary
GST registration revocation requires timely application, return compliance, payment of dues, and a reasoned statutory decision.
GST registration revocation after cancellation for return default is a conditional, time-bound process. An application under Section 30 and Rule 23 must ordinarily be filed within ninety days, subject to prescribed extension, and cannot be made until pending returns are filed and tax, interest, penalty and late fee are paid. Portal non-acceptance may permit online or physical submission where technically unavailable, but does not condone delay or ensure revocation. The competent authority must assess statutory eligibility, sufficient grounds and compliance while following notice and hearing requirements before rejection.
Case Laws Income Tax
Show AI Summary
Reassessment limitation under TOLA requires final notices to issue within surviving time and satisfy statutory safeguards.
Reassessment limitation under TOLA is a jurisdictional restraint. Transitional notices issued between 1 April 2021 and 30 June 2021 are treated as Section 148A(b) show-cause notices, but only the surviving time remaining until 30 June 2021 is available for completing the reassessment process. Periods for supply of material and the assessee's response are excluded, but the Section 148A(d) decision, statutory approval and final Section 148 notice must issue within the remaining period. For Assessment Year 2015-16, post-1 April 2021 notices are treated as time-barred.
Case Laws Customs
Show AI Summary
Unseized food consignments cannot face indefinite detention without lawful seizure, valid sampling, and prompt assessment.
Provisional release of an unseized imported food consignment is not mechanically governed by Section 110A, which applies to goods seized under Section 110. Customs may examine, test, verify and reassess imports, but indefinite retention without a seizure memorandum or disclosed reasons connecting the goods with confiscation is not justified. Food sampling should follow the specialised food-safety process through an authorised officer. A valid food-safety report may support conditional clearance, while classification, duty liability, confiscation and adjudication remain open. Revenue may be protected through proportionate security.
Case Laws Customs
Show AI Summary
Anti-dumping duty recovery permits post-clearance demands and consequential import IGST where self-assessment omitted an applicable levy.
Unpaid anti-dumping duty omitted during self-assessment may be pursued through the customs recovery procedure without prior appellate modification of the self-assessment. The recovery framework applies to anti-dumping duty through statutory incorporation of provisions concerning assessment, non-levy, short-levy, interest and recovery. Where anti-dumping duty is chargeable, it forms part of the aggregate value used to compute IGST on imports, potentially creating a consequential IGST short-payment. Recovery requires accurate assessment of notification coverage, product, origin, rate, valuation, limitation and procedural safeguards.
Case Laws GST
Show AI Summary
Project-wise anti-profiteering requires actual input tax credit measurement and area-based allocation of benefits to real-estate purchasers.
Real-estate anti-profiteering under Section 171 requires project-level identification of additional input tax credit and allocation of the saving across total project area on a per-square-foot basis. Purchase value may quantify credit attributable to project expenditure, but turnover or collections cannot serve as the allocation basis. The comparison must use pre-GST credit actually availed rather than merely available credit. GST collected on consideration inflated by an undistributed benefit forms part of the amount not passed on and remains distinct from statutory interest.
Case Laws Income Tax
Show AI Summary
Retirement leave encashment exemption applies under the enhanced notified ceiling while preserving non-government employee classification and statutory conditions.
Section 10(10AA)(ii) governs retirement leave-encashment exemption for non-Government employees, subject to the ten-month earned-leave measure, average-salary computation, and the notified monetary ceiling. Notification No. 31/2023 specifies an enhanced ceiling of Rs. 25,00,000, is deemed effective from 1 April 2023, and certifies that retrospective effect causes no adverse effect. The enhanced ceiling is treated as a remedial rationalisation of an existing exemption and may govern pending earlier-period matters, while preserving the distinction between Government and non-Government employees.
Case Laws GST
Show AI Summary
Transit GST jurisdiction limits detention penalties for documented inter-State supplies lacking a local taxable nexus.
Transit-State jurisdiction under GST permits interception, document production, e-way bill verification and authorised physical inspection of goods moving through an intermediate State. It does not, in a pure transit movement, support detention-related penalty for an external inter-State supply where origin and destination lie outside the intercepting State, no tax is payable there, and there is no evidence of diversion, local supply, fictitious or mismatched documents, or mismatch of goods. Cross-empowerment is administrative and does not create an independent territorial taxable nexus.
Case Laws SEBI
Show AI Summary
Shareholder ratification cannot cure preferential-issue fund diversion when disclosed objectives are abandoned, triggering securities-market fraud and disclosure concerns.
Post-facto shareholder approval cannot retrospectively validate diversion of preferential-issue proceeds contrary to issue-specific objects disclosed to shareholders and the market. A special resolution authorises the issue but does not permit unrestricted use of proceeds. Periodic deviation reporting, audit-committee review and utilisation disclosures promote transparency; they do not enable diversion followed by later regularisation. Immediate diversion, inadequate commercial justification and missing documentation may indicate that disclosed objects were not genuinely intended to be performed. Later amendment of corporate objects or shareholder ratification cannot cure a completed securities-market disclosure breach.

TMI Notes

Back

All TMI Notes

Showing Results for :
Reset Filters
No Records Found

TMI Notes

Back

All TMI Notes

Suppression of Facts under Explanation 2 to Section 74 of the CGST Act in Cases of Ineligible Input Tax Credit

26 October, 2026

Contents
Acts
Plus +
Summary
Note

Note

-

Bookmark

Print

Print

This is a neutral professional article. The judgment is analysed in the context of its factual background, issues framed, and conclusions reached by the Court.

2026 (8) TMI 1363 - GSTAT THIRUVANANTHAPURAM

At a Glance

  • Section 74 of the Central Goods and Services Tax Act, 2017, for the periods to which it applies, is attracted where tax has not been paid, short paid, erroneously refunded, or input tax credit has been wrongly availed or utilised "by reason of fraud, or any wilful-misstatement or suppression of facts to evade tax". Wrong availment is therefore not, without more, equivalent to suppression.
  • For the period in which Explanation 2 formed part of Section 74, "suppression" included non-declaration of information required in a return, statement, report or other document, or failure to furnish written information sought by the proper officer. The definition did not dispense with the statutory requirement that the conduct be connected with evasion of tax.
  • The Tribunal held in 2026 (8) TMI 1363 - GSTAT THIRUVANANTHAPURAM that mere availment of ineligible self-assessed ITC in the electronic credit ledger, absent contrary evidence, does not establish suppression under Section 74(1).
  • Where reconciliation and underlying information have been furnished in statutory filings and are available on the common portal, an allegation of non-declaration requires careful evidentiary substantiation. A mere mismatch or an assertion of ineligible credit cannot substitute proof of fraud, wilful misstatement, or suppression with intent to evade tax.
  • A demand cannot be sustained at the appellate stage on a materially new allegation, such as failure to answer an audit enquiry, where that allegation did not form part of the show cause notice.

Background & Context

Input tax credit is available only subject to the eligibility conditions and restrictions under Section 16 of the Central Goods and Services Tax Act, 2017. Section 16(1) permits a registered person, subject to prescribed conditions and restrictions, to take credit of input tax charged on supplies used or intended to be used in the course or furtherance of business. Section 16(2) imposes further conditions, including possession of the prescribed tax document, receipt of goods or services, payment of tax to the Government, and furnishing of the return.

The fact that credit may ultimately be found ineligible under Section 16, or may require restriction or reversal under Section 17 of the Central Goods and Services Tax Act, 2017, does not by itself answer the separate question whether the enhanced consequences under Section 74 can be invoked. Section 17 restricts credit to the business or taxable-supply attribution where inputs or input services have mixed use, and Section 17(5) identifies specified blocked credits. Eligibility is thus a substantive ITC issue; fraud, wilful misstatement and suppression concern the statutory basis for a Section 74 proceeding.

In 2026 (8) TMI 1363 - GSTAT THIRUVANANTHAPURAM, the controversy arose from an audit-based allegation of excess ITC. The notice treated the taking of allegedly ineligible self-assessed credit, referred to as being under Section 42(1), as suppression of facts and invoked Section 74. The adjudicating authority found that the relevant reconciliation had already been disclosed through annual-return filings and that the notice did not establish fraud, wilful misstatement, or suppression. The appellate authority reversed that conclusion by relying, among other matters, on an alleged non-response to audit communications. The Tribunal set aside the appellate order.

The decision is significant because it separates an allegation of erroneous or ineligible ITC from the distinct and more exacting statutory ingredients necessary to invoke Section 74. It also addresses the evidentiary importance of disclosures in returns, statements and reconciliations, and the limits imposed by the show cause notice on subsequent adjudication and appellate review.

Key Issues / Provisions

Section 74: the operative threshold and consequences

Section 74 of the Central Goods and Services Tax Act, 2017 applies to determination of tax pertaining to periods up to Financial Year 2023-24. The material part of Section 74(1) provides that where it appears to the proper officer that tax has not been paid, short paid or erroneously refunded, or ITC has been wrongly availed or utilised, "by reason of fraud, or any wilful-misstatement or suppression of facts to evade tax", the officer shall issue a notice requiring the noticee to show cause against payment of the specified amount, interest under Section 50, and penalty equivalent to the tax specified in the notice.

The provision carries a distinct procedural and penal framework. Section 74(2) requires notice to be issued at least six months before the deadline for the order. Under Section 74(10), the order must be issued within five years from the due date for furnishing the annual return for the relevant financial year, or within five years from the date of an erroneous refund. Section 74(5), Section 74(8) and Section 74(11) prescribe payment-based closure mechanisms with penalties of fifteen per cent before notice, twenty-five per cent within thirty days of notice, and fifty per cent within thirty days of communication of the order, respectively.

Accordingly, the statutory words connecting wrongful ITC with "fraud", "wilful-misstatement" or "suppression of facts to evade tax" are not surplusage. They define the foundation on which the Section 74 route, its extended determination period and its enhanced penalty structure may be adopted.

Explanation 2 and the meaning of suppression

For the period in which Explanation 2 was in force, it stated that "suppression" meant "non-declaration of facts or information which a taxable person is required to declare in the return, statement, report or any other document furnished under this Act or the rules made thereunder, or failure to furnish any information on being asked for, in writing, by the proper officer." The supplied statutory text records that Explanation 2 has since been omitted. The decision under discussion applies the definition as it operated for the proceedings concerned.

The two limbs of the historical definition require precision. The first turns on an identifiable fact or information that the taxable person was legally required to declare in a prescribed return, statement, report or other document. The second turns on a written requisition by the proper officer and a failure to furnish the information so sought. In either event, the definition operates within Section 74(1), whose text requires fraud, wilful misstatement or suppression "to evade tax".

Section 42(1): historical matching framework

Section 42 of the Central Goods and Services Tax Act, 2017 now stands omitted. Its erstwhile Section 42(1) provided for matching of details of every inward supply furnished by the recipient with corresponding outward-supply details furnished by the supplier, import IGST data, and duplicate ITC claims. The mere reference to Section 42(1) in an ITC dispute cannot, by itself, create a presumption that an erroneous claim was knowingly made or that facts were suppressed. The statutory requirements of Section 74 remain independently required.

Detailed Analysis

Mere ineligible ITC availment is not suppression

The central holding in 2026 (8) TMI 1363 - GSTAT THIRUVANANTHAPURAM is carefully qualified but clear: in the absence of other contrary evidence, mere taking of ineligible self-assessed ITC in the electronic credit ledger does not amount to suppression within Section 74(1). The Tribunal found that the show cause notice was founded on bare propositions that excess or ineligible credit itself amounted to suppression and that it was availed with mala fide intent. It contained no material establishing that the taxpayer knew the credit was ineligible and nevertheless took it in a contumacious act.

The Tribunal treated the burden as resting on the department to allege and establish the relevant statutory ingredients with evidence. Every transgression of Section 16(2) or the erstwhile Section 42(1) cannot be elevated into Section 74 action. There must be clear and categorical material that the transgression resulted from fraud, wilful misstatement, or suppression of facts with intent to evade tax. The Tribunal also noted the applicable departmental instruction placed before it: Section 74(1) cannot be invoked merely because GST was not paid, and material evidence of fraud, wilful misstatement or suppression to evade tax must both exist and form part of the show cause notice.

Disclosures in statutory filings negate a bare allegation of non-declaration

The Tribunal gave substantial weight to the factual finding that invoice-wise reconciliation concerning the alleged ITC difference had been uploaded with annual-return and GSTR-9C filings and was available on the common portal. Where the reconciliation is part of the statutory record, an allegation that the taxpayer failed to declare the very information must identify what required disclosure was absent and why the filed material did not meet that requirement. The appellate authority had not displaced the finding that the reconciliation was already disclosed.

This approach is consistent with 2013 (3) TMI 44 - CESTAT KOLKATA. There, disclosure of the quantum of credit in periodic returns, coupled with the absence of a prescribed requirement to furnish service-wise particulars in those returns, was held insufficient to establish suppression. The department could call for particulars and scrutinise the declaration; failure to include information not required by the return did not, without a positive act and intent to evade, justify the extended period.

Likewise, 2016 (9) TMI 89 - CESTAT CHENNAI distinguished the merits of credit eligibility from limitation. Although the credit was held ineligible, the extended period was rejected because the availment was reflected in returns and there was no demonstration of deliberate suppression or mala fide intent. The authority confirms that ineligibility of credit and suppression are legally distinct conclusions.

In 2019 (5) TMI 129 - CESTAT CHENNAI, the extended period was similarly held unavailable where credit availment had been disclosed in returns and the taxpayer had made an advance intimation of its intended credit position. The case illustrates that disclosure and the absence of material showing intent may independently defeat an allegation of suppression, even if the department disputes entitlement to credit.

Audit, self-assessment and response to departmental enquiry

The decision in 2026 (8) TMI 1363 - GSTAT THIRUVANANTHAPURAM also rejects the proposition that a mere failure to reply to an audit enquiry or final audit report necessarily constitutes suppression. First, the Tribunal held that this allegation was not part of the show cause notice. Secondly, the appellate order did not identify the information sought, the time at which it was sought, or the statutory provision under which it was sought. Thirdly, the statutory records and reconciliation were already available on the portal. On those facts, a non-response could not, without more, establish suppression.

2023 (8) TMI 995 - CESTAT NEW DELHI reinforces the proposition that a self-assessment regime does not itself convert an ordinary omission, interpretative disagreement or audit detection into wilful suppression. The authority emphasised that suppression must be deliberate and intentional, and that shortcomings in scrutiny do not relieve the department of its obligation to establish the mens rea necessary for extended limitation.

2017 (10) TMI 786 - CESTAT BANGALORE also held that regular return filing and departmental awareness during audit negated suppression with intent. Its relevance lies in the distinction between a demand arising after audit and proof that the taxpayer intentionally concealed material facts. Audit detection alone is not proof of the latter.

The contrary factual pattern: silence may still be material where intent is established

The principle is not that return disclosure invariably immunises a taxpayer from Section 74 or extended-period action. 2021 (8) TMI 127 - CESTAT NEW DELHI represents a materially different factual conclusion. The Tribunal found that the taxpayer had not disclosed the impugned credit until the departmental audit raised the issue, reversed the credit only after the query, and admitted that the credit was wrongly taken. On that factual foundation, the conduct was treated as suppression with intent to evade duty, and the extended period and penalty were sustained.

This authority demonstrates the evidentiary distinction. A finding of suppression cannot be based solely on the legal conclusion that credit was ineligible. But it may be sustained where the record establishes non-disclosure of material facts, post-detection reversal or admission, and facts from which deliberate concealment and intent can properly be inferred.

Natural justice and the confines of the show cause notice

In 2026 (8) TMI 1363 - GSTAT THIRUVANANTHAPURAM, the Tribunal found that the appellate order impermissibly adopted a new foundation: alleged failure to supply information during audit. As the show cause notice had rested on the alleged act of taking ineligible ITC, the taxpayer was not put to notice of a separate case based on written requisitions and audit non-compliance. The appellate authority could not cure the evidentiary and pleading deficiencies of the notice by introducing a new basis for Section 74.

2015 (2) TMI 1297 - CESTAT MUMBAI is also relevant on the consequences of an interpretative credit dispute. Credit on the disputed items was held inadmissible on merits, but extended-period demands were set aside because periodic returns and audits did not show fraud, collusion, wilful misstatement or suppression with intent. Thus, even an adverse decision on ITC eligibility does not eliminate the requirement to prove the special statutory ingredients for the extended route.

2025 (4) TMI 565 - CESTAT BANGALORE similarly held that transactions recorded in returns and books, and subjected to audit, did not support invocation of the extended period in the absence of misstatement or wilful suppression with intent. The authority confirms that regular documentation and disclosure are probative on the issue of intent, although their effect will necessarily depend on the complete factual record.

Practical Implications

  • Show cause notices under Section 74 should identify the precise statutory disclosure obligation allegedly breached, the specific information not declared or not furnished, the written requisition where reliance is placed on the second limb of the historical Explanation 2, and evidence connecting the conduct with intent to evade tax.
  • Taxpayers should preserve return acknowledgements, GSTR-9C reconciliations, invoice-level workings, reversal workings, audit correspondence and portal-upload records. These documents may be central to showing that information was disclosed rather than suppressed.
  • Where an audit objection is received, a reasoned response should identify disclosures already made, explain the reconciliation, and state the legal and factual basis for the credit. While non-response alone did not establish suppression on the facts of the principal decision, a contemporaneous response reduces factual uncertainty.
  • In adjudication, the defence should keep separate: first, whether ITC is eligible under Sections 16 and 17; secondly, whether Section 74 is legally invocable; and thirdly, whether the notice is barred if the special ingredients of Section 74 are not established.
  • At appellate stages, both sides must remain within the case set out in the show cause notice. A new charge of audit non-compliance, non-furnishing of information or concealed facts requires an appropriate pleaded foundation and an effective opportunity to answer it.

Key Takeaways

  • Wrong or ineligible ITC is not synonymous with suppression of facts.
  • For proceedings governed by the historical Explanation 2 to Section 74, the department must establish either non-declaration of information required by law or failure to furnish information requested in writing, while also satisfying the Section 74(1) requirement of fraud, wilful misstatement or suppression to evade tax.
  • Information already disclosed in statutory returns, annual reconciliations and portal filings materially weakens a bare allegation of non-declaration.
  • Mere non-response to audit communications, particularly where the allegation was absent from the show cause notice and the requested information is not identified, does not by itself establish suppression.
  • The decisive enquiry is evidence of deliberate conduct and intent to evade, not the eventual conclusion on ITC eligibility alone.


Full Text:

2026 (8) TMI 1363 - GSTAT THIRUVANANTHAPURAM

Topics

Acts Income Tax