

Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Category: ?
Categorized by AI
---- All Categories ---- ❯
  • ---- All Categories ----
  • Income Tax
  • GST
  • Customs, DGFT & SEZ
  • FEMA & RBI
  • Corp. Laws, SEBI & IBC
  • PMLA, Black Money & ED
  • Budget
  • News and Press Release
  • PTI News
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
    Appeal to Employees of Public Sector Banks and Regional Rural Banks for Ensuring Uninterrupted Banking Services.
    Central Bureau of Narcotics and Brahma Kumaris sign MoU to strengthen preventive drug awareness, youth empowerment and community outreach.
    PROVISIONAL ESTIMATES OF INDEX OF CORE INDUSTRIES FOR THE MONTH OF AUGUST 2026, AND FINAL INDEX FOR THE MONTH OF JULY 2026 WITH BASE YEAR 2022-23.
    India-New Zealand FTA to Enter into Force from 20 October 2026
    Bengaluru customs arrest passengers for smuggling ganja, gold at airport
    Third-country goods routed via New Zealand into India won't get FTA duty benefits
    Govt urges bank employees to refrain from strikes, resolve issues through dialogue
    Ex-Punjab DIG Bhullar case: ED arrests 'middleman' Kirshanu Sharda for corruption
    RBI revises foreign currency deposit inflows under FCNR(B) upward to USD 133 bn
    CBI arrests 'absconding' IRS officer in Rs 40-lakh bribery case
    Haryana plans Rs 2,295-crore rural infra push
    IPL betting syndicate: ED arrests 'principal bookie' in Guwahati money-laundering case
    ED chargesheets EaseMyTrip promoter Nishant Pitti in Mahadev betting app case
    “Sources and Methods for Compilation of National Accounts Statistics”
    Nearly 5 lakh Nagaland voters to receive notices over SIR mapping discrepancies
    India, Canada to hold next round of talks from Oct 5 for proposed trade pact: Goyal
    India's Semiconductor Market Projected to Grow Threefold to USD 200 billion by 2035: EY-IESA Report
    VKDL NPA Advisory Council Chairman V. K. Dubey Felicitated by Uttar Pradesh Women Commission Chairperson Babita Singh Chauhan
    Rupee rises 15 paise to close at 95.81 against US dollar
    Xi to visit US from Sept 23 to 25 for talks with Trump; China calls it ‘milestone of historic significance’
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

News
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
September 22, 2026
Show AI Summary
Five-day banking demand prompts continued dialogue as employees are urged to avoid strikes and maintain uninterrupted services.
Industrial-relations engagement addresses strike action seeking a five-day banking week and withdrawal of the Performance Linked Incentive scheme. The scheme has been kept in abeyance, while conciliation continues on the five-day workweek demand. Employees are urged to resolve issues through dialogue and maintain uninterrupted banking services. Workforce measures include revised pay scales, welfare benefits, streamlined recruitment and promotions, improved transfers, pension-related benefits, medical insurance, disability-related allowances, and early negotiations for the next Bipartite Settlement.
September 22, 2026
Show AI Summary
Preventive Drug Awareness Partnership establishes voluntary youth education, community outreach, and wellness activities without enforcement or policing functions.
The cooperative framework supports preventive drug-awareness campaigns, youth-empowerment initiatives and community outreach programmes through value-based education, awareness of harms associated with narcotic drugs and psychotropic substances, and information on counselling, recovery and treatment avenues. Activities include seminars, workshops, exhibitions, rallies, competitions and digital awareness initiatives, with focus on educational institutions, rural communities and youth. Activities remain voluntary, educational, inclusive and non-regulatory, and participating volunteers cannot perform enforcement, investigation or policing functions.
September 22, 2026
Show AI Summary
Core industry index growth is driven by electricity, cement, and iron ore despite contraction across coal, natural gas, and fertilizers.
The Index of Core Industries (ICI), using base year 2022-23, records a provisional overall index of 119.2 for August 2026, representing year-on-year growth of 4.8 per cent against August 2025. The July 2026 overall index has been finalised at 120.8 in place of its provisional value of 121.2, with the associated year-on-year growth revised from 5.4 per cent to 5.0 per cent. August 2026 data remain provisional.
September 22, 2026
Show AI Summary
Tariff liberalisation under the India-New Zealand FTA grants Indian exports duty-free access while protecting sensitive agricultural products.
From 20 October 2026, the India-New Zealand Free Trade Agreement applies duty-free treatment to all tariff lines covering Indian exports to New Zealand, while preserving exclusions for sensitive Indian agricultural products. Market access for New Zealand apples, kiwifruit, and Manuka honey remains subject to tariff rate quotas, minimum import prices, seasonal windows, and safeguards. Services commitments, mobility routes, investment facilitation, agricultural cooperation, and recognition of specified international inspection approvals form further components.
September 21, 2026
Show AI Summary
Airport smuggling enforcement targets concealed ganja and gold, leading to passenger interceptions and arrests under customs law.
Customs enforcement at Bengaluru airport involved interception and arrest of passengers allegedly attempting to smuggle hydroponic ganja and gold by concealing the goods in cabin baggage, other baggage, undergarments, or on the body. Cases involved arrivals from Vietnam, Bangkok, Kuala Lumpur, and Abu Dhabi. The Abu Dhabi gold-ornament case involved an arrest under the Customs Act.
September 21, 2026
Show AI Summary
Rules of origin prevent third-country transshipment from receiving preferential tariffs under bilateral trade arrangements between partner economies.
India-New Zealand free trade preferences apply only to goods satisfying Rules of Origin. Third-country goods routed through New Zealand cannot receive preferential Indian tariff treatment, as bilateral cumulation is confined to originating materials and goods of India and New Zealand. Sensitive sectors receive no duty concessions, while a bilateral safeguard mechanism addresses sudden import surges after duty elimination or reduction. Temporary Employment Entry, student mobility commitments, post-study work opportunities, and exemption from directly funded social-security contributions for temporary Indian residents form part of the services framework.
September 21, 2026
Show AI Summary
Banking service continuity is prioritised through dialogue as employee welfare measures and wage negotiations address outstanding demands.
Banking-sector industrial relations are addressed through an appeal to bank employees to avoid strike action and pursue outstanding demands through dialogue, in order to keep banking services uninterrupted. Most union concerns are considered substantially addressed, while a remaining demand continues to be examined. The demand for withdrawal of the Performance Linked Incentive scheme had been addressed by placing that scheme in abeyance following detailed discussions. Employee welfare measures, wage revisions, and negotiations for the forthcoming Bipartite Settlement are intended to support workforce welfare and banking-sector efficiency.
September 21, 2026
Show AI Summary
Money-laundering investigation addresses alleged use of a middleman to demand, receive, move and conceal corruption proceeds.
Money-laundering proceedings were initiated from corruption FIRs alleging that a middleman was used to demand and receive illegal gratification. Investigation concerns the alleged facilitation of receipt and movement of funds, supported by searches yielding cash seizure and freezing of financial accounts. Financial records and digital devices allegedly indicated unexplained deposits, investments, transactions involving the officer, and possible involvement of other public servants. The inquiry is tracing alleged proceeds of crime and the role of associated persons and entities.
September 21, 2026
Show AI Summary
FCNR(B) foreign-currency deposits use a swap facility to mobilise non-resident funds without direct rupee exchange-rate risk.
RBI's special USD-INR foreign-exchange swap facility mobilised foreign-currency inflows through FCNR(B) deposits, Overseas Foreign Currency Borrowings and External Commercial Borrowings. The FCNR(B) deposit window closed on 31 August 2026 after its mobilisation objective was achieved, while the facility remained available for the other two channels until 31 December 2026. FCNR(B) collections were revised upward to approximately USD 133 billion. Such deposits are fixed-term foreign-currency deposits with principal and interest repayable in the same currency, avoiding direct rupee exchange-rate risk for non-resident depositors.
September 21, 2026
Show AI Summary
GST bribery investigation concerns alleged illegal gratification sought to resolve quarry firm's tax and royalty proceedings.
GST-related corruption allegations concern an alleged demand for illegal gratification from a stone-quarrying firm to resolve GST and royalty proceedings. A Customs House Agent was apprehended in a trap operation while allegedly accepting the negotiated amount on behalf of a CGST Superintendent and an Additional Commissioner. Custody proceedings involved written communication of arrest grounds and intimation to relevant family members and advocates.
September 21, 2026
Show AI Summary
Rural infrastructure financing supports irrigation, roads, water supply, warehousing and micro-irrigation through structured lending and implementation oversight.
Haryana's 2026-27 rural infrastructure financing plan comprises six proposals for irrigation, roads, drinking-water supply and warehousing, with loan assistance proposed under the Rural Infrastructure Development Fund. Infrastructure Development Assistance has been sanctioned for the India International Horticulture Market, while further micro-irrigation proposals have been recommended under the Micro Irrigation Fund. Implementation oversight emphasises faster project execution and timely drawal claims, alongside borrowing approval and prospective support for water security, groundwater recharge, efficient irrigation and treated-wastewater reuse.
September 21, 2026
Show AI Summary
Money laundering allegations in illegal cricket betting prompted investigative custody and examination of suspected routing of betting proceeds.
Money-laundering investigation into an organised illegal cricket-betting syndicate concerns the alleged use of online platforms, encrypted messaging channels, and a principal bookie to solicit, accept, and settle bets. Betting-derived funds were allegedly routed through a partnership firm represented as non-operational, whose account recorded substantial corresponding credits and debits. Property and vehicle records, digital data, and statements under the PMLA are relied upon to allege the acquisition, possession, use, transfer, and projection of proceeds of crime as untainted property.
September 21, 2026
Show AI Summary
Money laundering allegations concern foreign portfolio investments, alleged share-price manipulation, attachment, and proposed confiscation of betting proceeds.
PMLA proceedings name Nishant Pitti in relation to allegations that proceeds from illegal online betting were introduced into Indian equity markets as foreign portfolio investments. The allegations attribute to him a role in facilitating and layering such proceeds through pre-arranged share-price manipulation involving Easy Trip Planners Ltd. Property action includes provisional attachment of his DEMAT shares, described as proceeds of crime, and a request for confiscation.
September 21, 2026
Show AI Summary
National accounts modernisation adopts updated data sources, revised sector methods, and proportional Denton benchmarking for improved GDP estimates.
National Accounts Statistics in the new series use base year 2022-23, replacing the 2011-12 series. The series was updated to reflect changes flowing from the new Producer Price Index and Index of Industrial Production series. Methodological modernization expands corporate and financial-sector data coverage, refines general-government treatment, and adopts direct household-sector estimation from the Annual Survey of Unincorporated Sector Enterprises and the Periodic Labour Force Survey. Private Final Consumption Expenditure adopts COICOP 2018, while Quarterly National Accounts use the Proportional Denton approach and greater Goods and Services Tax and administrative-data use.
September 21, 2026
Show AI Summary
Electoral roll verification requires unmapped voters to establish linkage or submit prescribed documents before final enrolment.
Special Intensive Revision of Nagaland's electoral roll applies a mapping and verification process by reference to the 2005 electoral roll. Electors recorded under no-mapping or mapping-anomaly categories, including persons unable to establish linkage to an elector in the 2005 roll, are to receive notices from Electoral Registration Officers or Assistant Electoral Registration Officers. They must furnish prescribed supporting documents, calibrated to their date or year of birth, for verification. Non-registration in the 2005 roll does not itself cause automatic exclusion.
September 21, 2026
Show AI Summary
Trade pact negotiations and Russian energy tariffs shape market-access commitments and potential import-duty exposure for exporters.
India and Canada have accelerated negotiations for a Comprehensive Economic Partnership Agreement to establish a bilateral trade framework for goods and services. A United States law concerning sanctions on Russia and Iran authorises tariffs of up to 100 per cent on imports from leading purchasers of Russian crude oil or natural gas, creating potential tariff exposure for Indian exports. The India-European Union trade pact contemplates immediate duty elimination on 90 per cent of Indian goods and phased elimination on a further three per cent over seven years, subject to ratification.
September 21, 2026
Show AI Summary
Semiconductor ecosystem policy requires predictable regulation, integrated clusters, and coordinated support to convert domestic demand into local value creation.
Semiconductor ecosystem development in India is centred on converting expanding domestic demand into local manufacturing, innovation and supply-chain resilience. A predictable fiscal and regulatory environment, alignment of central and state semiconductor policies, integrated manufacturing clusters and talent-certification programmes are important to project viability and commercialisation. Advanced packaging, compound semiconductors, photonics and chip-to-system integration offer high-potential areas, requiring policy certainty, streamlined approvals and long-term support for research, talent and supplier development.
September 21, 2026
Show AI Summary
Legal and NPA advisory services receive recognition for social welfare, women's employment, legal awareness, and financial dispute-resolution work.
Felicitation of Advocate V. K. Dubey recognised his stated work in women's employment, public welfare, banking, NPA resolution, legal awareness, and social service. His profile encompasses civil, criminal, non-performing asset, banking, corporate, and settlement matters; leadership of bodies engaged in financial-dispute resolution; and legal assistance and public awareness intended to improve access to justice for marginalised persons. Associated initiatives include education and support for disadvantaged communities and wider social empowerment.
September 21, 2026
Show AI Summary
Rupee appreciation reflected lower crude oil prices, stronger domestic equities, and improved risk sentiment amid diplomatic expectations.
Rupee appreciation against the US dollar followed lower crude oil prices, improved global risk sentiment, positive domestic equity markets, and softer US Treasury yields. Dollar index strength, geopolitical developments, and possible increases in oil supplies remained relevant to currency movements. Market commentary anticipated a slight positive rupee bias if crude oil prices continued to ease, while renewed geopolitical tensions could weaken risk sentiment. Net foreign institutional investment and a decline in foreign exchange reserves also formed part of the market context.
September 21, 2026
Show AI Summary
Reciprocal tariffs and AI incident notifications frame bilateral talks on trade, security, technology and arms sales.
US sanctions legislation authorises the President to impose tariffs, including up to 100 per cent, on countries purchasing Russian oil and gas. China rejects tariffs directed at its Russian energy purchases and opposes unilateral sanctions and long-arm jurisdiction absent an international-law basis or a UN Security Council mandate. Washington and Beijing are also negotiating a reciprocal tariff-reduction framework covering products from both sides.

News

Back

All News

Showing Results for :
Reset Filters
No Records Found

News

Back

All News

Recommendations of 47th GST Council Meeting

June 29, 2022

Contents
Circulars
Plus +
Summary
Note

Note

-

Bookmark

Print

Print

Recommendations of 47th GST Council Meeting

GoM on Casino, Race Course and Online Gaming to re-examine the issues based on further inputs from States and submit its report within a short duration

GoM to be constituted to address various concerns raised by the States on GST Appellate Tribunal and amendments in CGST Act

GoM on IT Reforms, inter alia, recommended that the GSTN should put in place the AI/ML based mechanism

All rate changes recommended by the 47th GST Council will be made effective from 18th July, 2022

The 47th GST Council met under the Chairmanship of Union Minister for Finance & Corporate Affairs Smt. Nirmala Sitharaman here in Chandigarh today. The meeting was also attended by Union Minister of State for Finance Shri Pankaj Choudhary besides Finance Ministers of States & UTs and senior officers of the Ministry of Finance & States/ UTs.
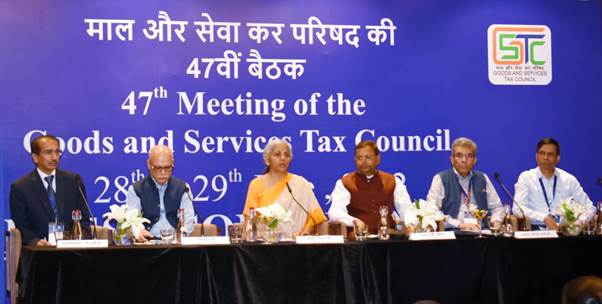
The GST Council has inter-alia made the following recommendations relating to changes in GST rates on supply of goods and services and changes related to GST law and procedure:

 I. Recommendations relating to GST rates on goods and services

A. Rate Rationalization to remove inverted duty structure [Approval of recommendations made by GoM on rate rationalization]

S. No.

Description

From

To

GOODS

  1.  

Printing, writing or drawing ink

12%

18%

  1.  

Knives with cutting blades, Paper knives, Pencil sharpeners and blades therefor, Spoons, forks, ladles, skimmers, cake-servers etc

12%

18%

  1.  

Power driven pumps primarily designed for handling water such as centrifugal pumps, deep tube-well turbine pumps, submersible pumps; Bicycle pumps

12%

18%

  1.  

Machines for cleaning, sorting or grading, seed, grain pulses; Machinery used in milling industry or for the working of cereals etc; Pawan Chakki that is Air Based Atta Chakki; Wet grinder;

5%

18%

  1.  

Machines for cleaning, sorting or grading eggs, fruit or other agricultural produce and its parts, Milking machines and dairy machinery

12%

18%

  1.  

LED Lamps, lights and fixture, their metal printed circuits board; 

12%

18%

  1.  

Drawing and marking out instruments

12%

18%

  1.  

Solar Water Heater and system;

5%

12%

  1.  

Prepared/finished leather/chamois leather / composition leathers;

5%

12%

  1.  

Refund of accumulated ITC not to be allowed on flowing goods:

  1. Edible oils
  2. Coal


Services

  1.  

Services supplied by foreman to chit fund

12%

18%

  1.  

Job work in relation to processing of hides, skins and leather

5%

12%

  1.  

Job work in relation to manufacture of leather goods and footwear

5%

12%

  1.  

Job work in relation to manufacture of clay bricks

5%

12%

  1.  

Works contract for roads, bridges, railways, metro, effluent treatment plant, crematorium etc.

12%

18%

  1.  

Works contract supplied to central and state governments, local authorities for historical monuments, canals, dams, pipelines, plants for water supply, educational institutions, hospitals etc. & sub-contractor thereof 

12%

18%

  1.  

Works contract supplied to central and state governments, union territories & local authorities involving predominantly earthwork and sub-contracts thereof

5%

12%

 B.    Other GST rate changes recommended by the Council

S. No.

Description

From

To

Goods

  1.  

Ostomy Appliances

12%

5%

  1.  

Orthopedic appliance- Splints and other fracture appliances; artificial parts of the body; other appliances which are worn or carried, or implanted in the body, to compensate for a defect or disability; intraocular lens

12%

5%

  1.  

Tetra Pak (Aseptic Packaging Paper)

12%

18%

  1.  

Tar (whether from coal, coal gasification plants, producer Gas plants and Coke Oven Plants.

5%/18%

18%

  1.  

IGST on import of Diethylcarbamazine (DEC) tablets supplied free of cost for National Filariasis Elimination Programme

5%

Nil

  1.  

Cut and Polished diamonds

0.25%

1.5%

  1.  

IGST on specified defence items imported by private entities/vendors, when end-user is the Defence forces.

Applicable rate

Nil

Services

1.

Transport of goods and passengers by ropeways.

18%

5% (with ITC of services)

2

Renting of truck/goods carriage where cost of fuel is included

18%

12%

 C Withdrawal of exemptions [Approval of recommendations made by GoM on rate rationalization]

C1.     Hitherto, GST was exempted on specified food items, grains etc when not branded, or right on the brand has been foregone. It has been recommended to revise the scope of exemption to exclude from it prepackaged and pre-labelled retail pack in terms of Legal Metrology Act, including pre-packed, pre-labelled curd, lassi and butter milk.

 C.2    In case of the following goods, exemption from GST will be withdrawn: 

S. No.

Description of goods

From

To

GST rate changes

  1.  

Cheques, lose or in book form

Nil

18%

  1.  

Maps and hydrographic or similar charts of all kinds, including atlases, wall maps, topographical plans and globes, printed

Nil

12%

  1.  

Parts of goods of heading 8801

Nil

18%

 C.3    In case of the following goods, the exemption in form of a concessional rate of GST is being rationalized: 

S. No.

Description of goods

From

To

GST rate changes

  1.  

Petroleum/ Coal bed methane

5%

12%

  1.  

Scientific and technical instruments supplied to public funded research institutes

5%

Applicable rate

  1.  

E-waste

5%

18%

 C4.   In case of Services, following exemptions are being rationalized: 

S. No.

Description


1.

Exemption on transport of passengers by air to and from NE states & Bagdogra is being restricted to economy class

2

Exemption on following services is being withdrawn.

  1. Transportation by rail or a vessel of railway equipment and material.
  2. storage or warehousing of commodities which attract tax (nuts, spices, copra, jaggery, cotton etc.)
  3. Fumigation in a warehouse of agricultural produce.
  4. Services by RBI,IRDA,SEBI,FSSAI,
  5. GSTN.
  6. Renting of residential dwelling to business entities (registered persons).
  7. Services provided by the cord blood banks by way of preservation of stem cells

3.

Like CETPs, common bio-medical waste treatment facilities for treatment or disposal of biomedical waste shall be taxed at 12% so as to allow them ITC

4.

Hotel accommodation priced upto Rs. 1000/day shall be taxed at 12%

5.

Room rent (excluding ICU) exceeding Rs 5000 per day per patient charged by a hospital shall be taxed to the extent of amount charged for the room at 5% without ITC.

6.

Tax exemption on training or coaching in recreational activities relating to arts or culture, or sports is being restricted to such services when supplied by an individual.

D.  GST on casinos, race course and online gaming

The Council directed that the Group of Ministers on Casino, Race Course and Online Gaming re-examine the issues in its terms of reference based on further inputs from States and submit its report within a short duration.

E.  Clarification on GST rate 

E1.  Goods

  1. Electric vehicles whether or not fitted with a battery pack, are eligible for the concessional GST rate of 5%.
  2. All fly ash bricks attract same concessional rate irrespective of fly ash content
  3. Stones covered in S. No.123 of Schedule-I (such as Napa stones), even if they are ready to use and polished in minor ways [not mirror polished], attract concessional GST rate of 5%.
  4. The GST rate on all forms of mango under CTH 0804, including mango pulp (other than mangoes sliced, dried) attract GST at the 12%. Entry is also being amended to make this amply clear. Raw or fresh mangoes continue to be exempt.
  5. Sewage treated water is exempted from GST and is not the same as purified water provided in S. No. 99 of notification 2/2017-CT(Rate). The word 'purified' is being omitted to make this amply clear.
  6. Nicotine Polarilex Gum attracts a GST rate of 18%.
  7. The condition of 90% fly ash content with respect to fly ash bricks applies only to fly ash aggregate, and not fly ash bricks. As a simplification measure, the condition of 90% content is being omitted.

E2 .Clarification in relation to GST rate on Services 

1. Due to ambiguity in GST rates on supply of ice-cream by ice-cream parlours, GST charged @ 5% without ITC on the same during the period 1.07.2017 to 5.10.2021 shall be regularized to avoid unnecessary litigation.

2. Application fee charged for entrance or for issuance of eligibility certificate for admission or issuance of migration certificate by universities is exempt from GST.

3.  Ginned or baled fibre is covered in entry 24B of notification No. 12/2017- Central Tax (Rate) dated 28.06.2017 in the category of raw vegetable fibres. The exemption under this entry is being rationalized

4. Services associated with transit cargo both to and from Nepal and Bhutan are covered by exemption under entry 9B of notification No. 12/2017-CT(R) dated 28.06.2017.

5. Activity of selling of space for advertisement in souvenirs published in the form of books is eligible for concessional GST at 5%.

7. Renting of vehicle with operator for transportation of goods on time basis is classifiable under Heading 9966 (rental services of transport vehicles with operators) and attracts GST at 18%.GST on such renting where cost of fuel is included in the consideration charged is being prescribed at 12%.

8. Allowing choice of location of a plot is part of supply of long term lease of plot of land. Therefore, location charge or preferential location charges (PLC) are part of consideration charged for long term lease of land and shall get the same treatment under GST.

9. Services provided by the guest anchors to TV channels in lieu of honorarium attract GST.

10. Additional fee collected in the form of higher toll charges from vehicles not having Fastag is essentially payment of toll for allowing access to roads or bridges to such vehicles and shall be given the same tax treatment as given to toll charges.

11. Services in form of Assisted Reproductive Technology (ART)/ In vitro fertilization (IVF) are covered under the definition of health care services for the purpose of exemption under GST.

12. Sale of land after leveling, laying down of drainage lines etc. is sale of land and does not attract GST.

13. Renting of motor vehicles for transport of passengers to a body corporate for a period (time) is taxable in the hands of body corporate under RCM.

14. The expression ‘public transport’ used in the exemption entry at SI No. 17(d) of notification No. 12/2017-CT(R), which exempts transport of passengers by public transport other than predominantly for tourism purpose, in a vessel between places located in India, means that such transport should be open to public for point to point transport [e.g. such transport in Andaman and Nicobar islands].

Other miscellaneous changes 

1. All taxable service of Department of Posts would be subject to forward charge. Hitherto certain taxable services of Department of post were taxed on reverse charge basis.

2. Goods transport agency (GTA) is being given option to pay GST at 5% or 12% under forward charge; option to be exercised at the beginning of Financial Year. RCM option to continue.

3.  Service provided by Indian Tour operator to a foreign resident for a tour partially in India and partially outside India is to be subject to tax proportionate to the tour conducted in India for such foreign tourist subject to conditions that this concession does not exceed half of tour duration.

The rate changes recommended by the 47th GST Council will be made effective from 18th July, 2022.

II. Further, the GST Council has inter-alia made the following recommendations relating to GST law and procedure:

 A.Measures for Trade facilitation: 

  1. In-principal approval for relaxation in the provisions for suppliers making supplies through E-Commerce Operators (ECOs)


  1. Waiver of requirement of mandatory registration under section 24(ix) of CGST Act for person supplying goods through ECOs, subject to certain conditions, such as-
    1.  the aggregate turnover on all India basis does not exceed the turnover specified under sub-section (1) of section 22 of the CGST Act and notifications issued thereunder.
    2.  the person is not making any inter-State taxable supply
  1. Composition taxpayers would be allowed to make intra-State supply through e-commerce operators subject to certain conditions.

 The details of the scheme will be worked out by the Law Committee of the Council. The scheme would be tentatively implemented with effect from 01.01.2023, subject to preparedness on the portal as well as by ECOs.

  1. Amendment in formula prescribed in sub-rule (5) of rule 89 of CGST Rules, 2017 for calculation of refund of unutilized Input Tax Credit on account of inverted rated structure
  1. Change in formula for calculation of refund under rule 89(5) to take into account utilization of ITC on account of inputs and input services for payment of output tax on inverted rated supplies in the same ratio in which ITC has been availed on inputs and input services during the said tax period. This would help those taxpayers who are availing ITC on input services also.
  1. Amendment in CGST Rules for handling of pending IGST refund claims: In some cases where the exporter is identified as risky exporter requiring verification by GST officers, or where there is a violation of provisions of Customs Act, the refund claims in respect of export of goods are suspended/withheld.

Amendment in rule 96 of the CGST Rules has been recommended to provide for transmission of such IGST refund claims on the portal in a system generated FORM GST RFD-01 to the jurisdictional GST authorities for processing. This would result in expeditious disposal of such IGST refund claims, after due verification by GST officers, thus benefitting such exporters.

  1. Re-credit of amount in electronic credit ledger to be provided in those cases where erroneous refund amount sanctioned to a taxpayer on account of accumulated ITC or on account of IGST paid on zero rated supply of goods or services, in contravention of rule 96(10) of the CGST Rules, is deposited by him along with interest and penalty, wherever applicable. A new FORM GST PMT-03Ais introduced for the same.

This will enable the taxpayers to get re-credit of the amount of erroneous refund, paid back by them, in their electronic credit ledger.

  1. Clause (c) of section 110 and section 111 of the Finance Act, 2022 to be notified by Central Government at the earliest. These provisions relate to-
  1. retrospective amendment in section 50(3) of CGST Act, with effect from 01.07.2017,to provide that interest will be payable on the wrongly availed ITC only when the same is utilized;
  2. amendment in sub-section (10) of section 49 of CGST Act to provide for transfer of balance in electronic cash ledger of a registered person to electronic cash ledger of CGST and IGST of a distinct person.

 The rules providing for the manner of calculation of interest under section 50 of CGST Act have also been recommended for more clarity. This will remove ambiguities regarding manner of calculation of interest and will also provide for transfer of balance in CGST and IGST cash ledgers between distinct persons, thereby improving liquidity and cash flows of such taxpayers. 

  1. Waiver of late fee for delay in filing FORM GSTR-4 for FY 2021-22 and extension of due date for filing FORM GST CMP-08 for Q1 of FY 2022-23:
  1. To extend the waiver of late fee under section 47 for delay in filing FORM GSTR-4 for FY 2021-22 by approximately four more weeks, i.e. till 28.07.2022 (The existing waiver is for the period from 01.05.2022 till 30.06.2022)
  2. To extend the due date of filing of FORM GST CMP-08 for the 1st quarter of FY 2022-23 from 18.07.2022 to 31.07.2022.

GSTN has also been asked to expeditiously resolve the issue of negative balance in Electronic Cash Ledger being faced by some of the composition taxpayers. 

  1. Present exemption of IGST on import of goods under AA/EPCG/EOU scheme to be continued and E-wallet scheme not to be pursued further. 
  2. Issuance of the following circulars in order to remove ambiguity and legal disputes on various issues, thus benefiting taxpayers at large:
  3. Clarification on issue of claiming refund under inverted duty structure where the supplier is supplying goods under some concessional notification.
  4. Clarification on various issues relating to applicability of demand and penalty provisions under the CGST Act in respect of transactions involving fake invoices.
  5. Clarification on mandatory furnishing of correct and proper information of inter-State supplies and amount of ineligible/blocked Input Tax Credit and reversal thereof in return in FORM GSTR-3B.
  6. Clarification in respect of certain GST related issues:
    1. Clarification on the issues pertaining to refund claimed by the recipients of supplies regarded as deemed export;
    2. Clarification on various issues relating to interpretation of section 17(5) of the CGST Act;
    3. Clarification on the issue of perquisites provided by employer to the employees as per contractual agreement;
    4. Clarification on utilization of the amounts available in the electronic credit ledger and the electronic cash ledger for payment of tax and other liabilities. 
  7. Exemption from filing annual return in FORM GSTR-9/9A for FY 2021-22 to be provided to taxpayers having AATO upto Rs. 2 crores. 
  8. Explanation 1 after rule 43 of CGST Rules to be amended to provide that there is no requirement of reversal of input tax credit for exempted supply of Duty Credit Scrips by the exporters. 
  9. UPI & IMPS to be provided as an additional mode for payment of Goods and Services Tax to taxpayers under Rule 87(3) of CGST Rules. 
  10. In respect of refunds pertaining to supplies to SEZ Developer/Unit, an Explanation to be inserted in sub-rule (1) of rule 89 of CGST Rules to clarify that “specified officer” under the said sub-rule shall mean the “specified officer” or “authorized officer”, as defined under SEZ Rules, 2006. 
  11. Amendment in CGST Rules to provide for refund of unutilized Input Tax Credit on account of Export of Electricity. This would facilitate the exporters of electricity in claiming refund of utilized ITC on zero rated supplies. 
  12. Supplies from Duty Free Shops (DFS) at international terminal to outgoing international passengers to be treated as exports by DFS and consequential refund benefit to be available to them on such supplies. Rule 95A of the CGST Rules, Circular No. 106/25/2019-GST dated 29.06.2019 and related notifications to be rescinded accordingly. 

B. Measures for streamlining compliances in GST 

  1. Provision for automatic revocation of suspension of registration in cases where suspension of registration was done by the system under Rule 21A(2A) of CGST Rules, for non-compliance in terms of clause (b) or clause (c) of sub-section (2) of section 29[continuous non-filing of specified number of returns], once all the pending returns are filed on the portal by the taxpayer. (Amendment in rule 21A) 
  2. Proposal for comprehensive changes in FORM GSTR-3B to be placed in public domain for seeking inputs/suggestions of the stakeholders. 
  3. Time period from 01.03.2020 to 28.02.2022 to be excluded from calculation of the limitation period for filing refund claim by an applicant under section 54 and 55 of CGST Act, as well as for issuance of demand/ order (by proper officer) in respect of erroneous refunds under section 73 of CGST Act. Further, limitation under section 73 for FY 2017-18 for issuance of order in respect of other demands linked with due date of annual return, to be extended till 30th September, 2023. 

C. The Council has decided to constitute a Group of Ministers to address various concerns raised by the States in relation to constitution of GST Appellate Tribunal and make recommendations for appropriate amendments in CGST Act. 

D. The GST Council approved ad-hoc apportionment of IGST to the extent of Rs. 27,000 crores and release of 50% of this amount, i.e. Rs. 13,500 crore to the States. 

E.   The GoM on IT Reforms, inter alia, recommended that the GSTN should put in place the AI/ML based mechanism to verify the antecedents of the registration applicants and an improved risk-based monitoring of their behavior post registration so that non-compliant tax payers could be identified in their infancy and appropriate action be taken so as to minimize risk to exchequer. 

Note: The recommendations of the GST Council have been presented in this release containing major item of decisions in simple language for information of all stakeholders. The same would be given effect through relevant Circulars/ Notifications/ Law amendments which alone shall have the force of law. 

Topics

Acts Income Tax