

Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Category: ?
Categorized by AI
---- All Categories ---- ❯
  • ---- All Categories ----
  • Income Tax
  • GST
  • Customs, DGFT & SEZ
  • FEMA & RBI
  • Corp. Laws, SEBI & IBC
  • PMLA, Black Money & ED
  • Budget
  • News and Press Release
  • PTI News
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
    Advisory on “Multistate Registration” Facility for GST Registration
    Forward-Looking Survey on Private Corporate Sector CAPEX Investment Intentions (Survey period: October–December 2026)
    CRIT and IIFT Organise Three-Day Orientation Course on Trade Negotiations
    Union Minister of Commerce and Industry Shri Piyush Goyal Participates in Opening Day of G20 Trade Ministers’ Meeting in Milwauke, U.S
    Insolvency and Bankruptcy Code has strengthened credit discipline, improved recovery climate and contributed to ease of doing business: Harsh Malhotra...
    Central Bureau of Narcotics, DNC office, conducts drug abuse and addiction awareness campaign under Operation Jagriti in Lucknow
    Commerce and Industry Minister Piyush Goyal Calls for WTO-Compliant Approach to Correcting Global Trade Distortions at the Concluding Day of G20 Trade...
    APEDA Facilitates Export of Bihar’s Makhana from Purnea to Greece
    APEDA Facilitates FPO-led Export of Frozen Food Products from Haryana to Canada
    Government Extends Operational Timelines of RELIEF (Resilience & Logistics Intervention for Export Facilitation) Intervention to Support Exporters Ami...
    Government Extends Remission of Duties and Taxes on Exported Products ( RoDTEP) Scheme upto 31st December 2026
    DRI cracks down on illegal wildlife trafficking; elephant ivory, leopard skin, live pangolins and tiger parts seized; 11 persons arrested
    DRI busts two-way gold-diamond smuggling syndicate at Mumbai airport
    CBN Madhya Pradesh Unit destroys over 10.84 tonnes of seized narcotic drugs and deposits 154.375 kg of seized opium at GOAW, Neemuch
    CBN Rajasthan Unit seizes 1.080 kg hydroponic weed (ganja) concealed in international parcel from Thailand
    CBN Madhya Pradesh Unit seizes 4.240 kg opium; one person arrested
    Gross and Net GST revenue collections for the month of September, 2026
    Release of the Annual Survey of Industries (2024-25) results
    5th Kautilya Economic Conclave to be held in New Delhi from 3 to 5 October 2026 under the theme “Resilience in an Age of Flux”
    CCI approves the acquisition of certain equity share capital in IndiaFirst Life Insurance Co. Ltd. by BNP Paribas Cardif
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

News
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
October 3, 2026
Show AI Summary
Multistate GST registration enables normal taxpayers to submit common information once for simultaneous State and UT applications.
Multistate Registration enables normal taxpayers seeking GST registration under the same PAN in more than one State or Union Territory to apply simultaneously. A Master TRN is generated after selection of the intended jurisdictions and must be submitted with Common Registration Information. Individual TRNs are then generated for each selected jurisdiction, with common information auto-populated and editable. Applicants must provide principal and additional places of business, State-specific information, and Aadhaar authentication.
October 3, 2026
Show AI Summary
Private corporate CAPEX survey collects forward investment data through secure self-reporting while protecting enterprise-level confidentiality.
CAPEX 2026 collects information from selected large private corporate enterprises on past, provisional and intended capital expenditure across asset groups and sectors, including investment strategies, financing, green energy and robotics. Responses are self-compiled through a secure portal with bilingual and digital assistance. Complete, accurate and timely reporting supports validation and aggregate investment indicators. Individual enterprise information is protected through confidentiality safeguards, and unit-level CAPEX data are not disseminated.
October 3, 2026
Show AI Summary
International trade negotiations training addressed WTO rules, dispute settlement, sustainability, trade remedies, digital trade, and services.
Trade-negotiation capacity-building introduced foundational trade theory and the WTO framework, followed by instruction on treaty interpretation, trade data and dispute settlement. Specialised sessions addressed trade remedies, rules of origin, non-tariff measures, intellectual property rights, digital trade and services. It also considered labour, environmental and sustainability issues, including carbon border adjustment and deforestation requirements, within an increasingly complex global trade environment.
October 3, 2026
Show AI Summary
Food security safeguards distinguish transparent public stockholding measures from coercive trade actions within multilateral trade cooperation.
India maintains public stockholding, procures food from small and marginal farmers, and may adopt temporary, transparent measures during harvest shortfalls to preserve food availability and affordability. These food-security measures are identified as recognised within the WTO framework. A distinction is advanced between legitimate food-security interventions and coercive trade actions used to exert pressure on other countries. G20 Trade Ministers reached consensus on a statement addressing the weaponization of food through coercive trade actions and committed to continued cooperation.
October 3, 2026
Show AI Summary
Insolvency resolution reform prioritises timely, value-maximising outcomes through technology adoption, mediation, and legislative responsiveness across the insolvency ecosystem.
The Insolvency and Bankruptcy Code seeks faster, value-maximising resolutions through legislative responsiveness, technology adoption and adherence to prescribed timelines. Reform priorities include reducing case-disposal delays, speeding consideration of resolution plans, revising admission thresholds, mediation and sector-specific carveouts. The framework is associated with creditor recoveries, rescue of viable businesses and changed debtor-creditor behaviour.
October 3, 2026
Show AI Summary
Drug abuse prevention awareness promotes student education, peer outreach, and youth responsibility for a drug-free society.
Operation Jagriti promotes drug abuse and addiction awareness among students by addressing the harmful effects of substance use and practical prevention measures. Students are encouraged to avoid drugs, spread prevention awareness among peers and communities, and contribute responsibly to the Nasha Mukt Bharat objective of a drug-free India.
October 3, 2026
Show AI Summary
Forced-labour border measures require verifiable evidence, due process and WTO consistency while preserving cooperation without unilateral trade action.
Global trade distortions should be addressed through WTO-consistent, evidence-based anti-dumping and countervailing measures, without restricting developing countries' policy space for industrialisation. Most-Favoured-Nation treatment, consensus decision-making, special and differential treatment, and a two-tier dispute-settlement system remain central to multilateral trade governance. Imports produced using forced labour are prohibited, while border measures must rely on specific, verifiable evidence, observe due process and WTO rules, and avoid presumptions concerning entire countries, regions or sectors.
October 3, 2026
Show AI Summary
Export-led market access for Makhana expands overseas buyer linkages, supports higher producer returns, and promotes European market diversification.
Export-oriented market access for Bihar's Makhana is being expanded through a facilitated shipment of popped Makhana from Purnea to Greece. APEDA's support connects producers and exporters with international buyers and strengthens the export value chain. Higher price realisation than domestic selling prices indicates scope for improved producer returns, wider farmer and producer-group participation, and diversification into European markets. Export promotion is linked to a proposed Agri Export Policy and packhouse development.
October 3, 2026
Show AI Summary
FPO-led export market access links processed food producers with global buyers and strengthens agricultural value-chain participation.
APEDA facilitated an FPO-led export of frozen food products to Canada by Aterna Foods Producer Company Limited, with support under its Financial Assistance Scheme. The export included frozen vegetables, sweet corn, samosa and other processed food products. Market-linkage initiatives connect Farmer Producer Organisations and Farmer Producer Companies with exporters and global buyers, promoting export-oriented value chains and integrating agricultural produce with processing and international markets.
October 3, 2026
Show AI Summary
RELIEF timeline extension preserves credit-insurance support and premium protection for exporters facing West Asia maritime disruptions.
Component II of the RELIEF intervention extends operational timelines for exporters affected by West Asia maritime-logistics disruptions. It encourages eligible exporters to obtain ECGC cover for upcoming shipments to specified regions with 95% risk coverage. Benefits apply to qualifying Stand Alone Policies and Whole Turnover Policies, covering full container load, less than container load, and reefer containers, but excluding energy shipments. Eligible exporters' insurance premium cannot increase beyond the pre-disruption level during the relevant period.
October 3, 2026
Show AI Summary
RoDTEP duty remission continues for eligible exporters, preserving existing rates and value caps through the extended period.
RoDTEP Scheme continuation is extended until 31 December 2026 for exports made by Domestic Tariff Area units, Advance Authorisation holders, Special Economic Zone units and Export Oriented Units. The scheme remits embedded, un-rebated Central, State and local duties, taxes and levies borne on exported products. Existing RoDTEP rates and value caps remain unchanged throughout the extension.
October 3, 2026
Show AI Summary
Wildlife trafficking enforcement targeted unlawful possession, transport and proposed sale of ivory, leopard skin, pangolins and tiger parts.
Illegal wildlife trafficking operations addressed alleged possession, transportation, and attempted sale of elephant ivory, leopard skin, live pangolins, and tiger parts. Possession without licence and trade in elephant ivory or ivory articles are prohibited under the Wild Life (Protection) Act, 1972. Leopards, pangolins, tigers, and their body parts receive Schedule I protection, while pangolins are also listed in CITES Appendix I, prohibiting international trade. Recovered wildlife articles, live animals, and vehicles were transferred or seized for action by forest and specialised wildlife enforcement agencies.
October 3, 2026
Show AI Summary
Two-way airport smuggling: airport staff allegedly facilitated clandestine gold entry and illicit diamond export through transit and outbound passengers.
An alleged two-way smuggling arrangement involved airport staff receiving foreign-origin gold dust in wax capsules from transit passengers for clandestine removal into India and transferring diamonds to an outbound passenger for illicit export to Dubai. Seizure included 23 capsules of 24-carat foreign-origin gold dust in wax form and natural and lab-grown diamonds. The modus operandi used the same airport employee to facilitate import-side gold smuggling and export-side diamond smuggling.
October 3, 2026
Show AI Summary
Seized narcotic-drug disposal prevents contraband re-entry through supervised destruction, lawful opium deposit, and environmentally safe incineration.
Authorised disposal of seized narcotic drugs under the Narcotic Drugs and Psychotropic Substances Act, 1985 involved destruction of 10,842.150 kg of contraband through an approved process supervised by the Drug Disposal Committee and attended by a pollution-control representative. Seized opium was separately deposited with the Government Opium and Alkaloid Works as part of the disposal process, aimed at preventing contraband from returning to illicit drug trafficking and ensuring environmentally safe incineration.
October 3, 2026
Show AI Summary
International postal narcotics trafficking: hydroponic ganja concealed in cake pouches was seized under NDPS procedures.
Seizure under the relevant provisions of the Narcotic Drugs and Psychotropic Substances Act, 1985, covered hydroponic weed (ganja) recovered from an international parcel received from Thailand. The contraband was concealed in cake pouches placed among other packets and articles to camouflage its presence. Specific intelligence prompted examination, recovery, weighing and seizure following due legal procedure, with further investigation in progress.
October 3, 2026
Show AI Summary
NDPS enforcement enabled opium and vehicle seizure, with arrest after an intelligence-led roadside interception operation.
Intelligence-based enforcement under the Narcotic Drugs and Psychotropic Substances Act, 1985, resulted in the interception of a motorcycle and recovery of 4.240 kg of opium. The opium and motorcycle used for transportation were seized after legal formalities, and one person was arrested. Investigation continues to trace the contraband's source and intended destination and identify other persons connected with the suspected trafficking network.
October 1, 2026
Show AI Summary
GST revenue accounting distinguishes gross collections, refunds, net domestic and customs revenue, and SGST-IGST settlement reporting.
Gross GST revenue for September 2026 distinguishes domestic collections and IGST on imports; after domestic and ICEGATE refund adjustments, net revenue is calculated separately for domestic and customs GST. Cumulative collections through September similarly distinguish gross receipts, refunds and net revenue. SGST reporting compares pre-settlement receipts with post-settlement amounts that include the SGST portion of IGST settled to States and Union Territories. State and Union Territory revenue comparisons exclude GST on imported goods, while April-September domestic collections are split between Central and State formations.
October 1, 2026
Show AI Summary
Annual Survey of Industries results record broad manufacturing growth and define survey coverage, enumeration, digital data collection, and reliability limits.
ASI 2024-25 records broad-based growth in registered manufacturing, including establishments, output, Gross Value Added, employment, emoluments, fixed capital, invested capital, net income and net profit. The survey covers specified registered factories, bidi and cigar establishments, certain electricity undertakings, and qualifying large units in State-maintained business registers. Data are collected electronically under the statutory framework for collection of statistics using an establishment-based approach, with quality checks and caution required because the estimates arise from a sample survey.
October 1, 2026
Show AI Summary
Economic resilience policy dialogue examines financial stability, digital governance, trade fragmentation, and investment priorities amid global uncertainty.
The fifth Kautilya Economic Conclave will examine economic resilience amid global shocks through discussions on macroeconomic stability, monetary policy, financial stability, investment, fiscal federalism and capital-market development. Its agenda also covers digital economy governance, artificial intelligence, trade fragmentation, strategic autonomy, climate resilience, food systems, demographic change and global health security. Plenaries, parallel sessions and closed-door roundtables will consider policy responses and mobilisation of domestic and foreign capital for long-term investment.
September 30, 2026
Show AI Summary
Equity acquisition in a life insurer receives competition clearance for BNP Paribas Cardif's proposed investment.
Competition Commission of India approval covers a proposed combination under which BNP Paribas Cardif will acquire certain equity share capital in IndiaFirst Life Insurance Company Limited. The transaction is an acquisition of an ownership interest in an Indian life insurer. IndiaFirst Life Insurance Company Limited is incorporated in India, is an IRDAI-licensed insurer, and provides life insurance in India.

News

Back

All News

Showing Results for :
Reset Filters
No Records Found

News

Back

All News

Recommendations of 47th GST Council Meeting

June 29, 2022

Contents
Circulars
Plus +
Summary
Note

Note

-

Bookmark

Print

Print

Recommendations of 47th GST Council Meeting

GoM on Casino, Race Course and Online Gaming to re-examine the issues based on further inputs from States and submit its report within a short duration

GoM to be constituted to address various concerns raised by the States on GST Appellate Tribunal and amendments in CGST Act

GoM on IT Reforms, inter alia, recommended that the GSTN should put in place the AI/ML based mechanism

All rate changes recommended by the 47th GST Council will be made effective from 18th July, 2022

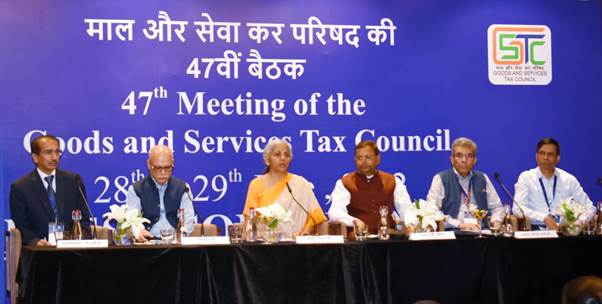
The 47th GST Council met under the Chairmanship of Union Minister for Finance & Corporate Affairs Smt. Nirmala Sitharaman here in Chandigarh today. The meeting was also attended by Union Minister of State for Finance Shri Pankaj Choudhary besides Finance Ministers of States & UTs and senior officers of the Ministry of Finance & States/ UTs.
The GST Council has inter-alia made the following recommendations relating to changes in GST rates on supply of goods and services and changes related to GST law and procedure:

 I. Recommendations relating to GST rates on goods and services

A. Rate Rationalization to remove inverted duty structure [Approval of recommendations made by GoM on rate rationalization]

S. No.

Description

From

To

GOODS

  1.  

Printing, writing or drawing ink

12%

18%

  1.  

Knives with cutting blades, Paper knives, Pencil sharpeners and blades therefor, Spoons, forks, ladles, skimmers, cake-servers etc

12%

18%

  1.  

Power driven pumps primarily designed for handling water such as centrifugal pumps, deep tube-well turbine pumps, submersible pumps; Bicycle pumps

12%

18%

  1.  

Machines for cleaning, sorting or grading, seed, grain pulses; Machinery used in milling industry or for the working of cereals etc; Pawan Chakki that is Air Based Atta Chakki; Wet grinder;

5%

18%

  1.  

Machines for cleaning, sorting or grading eggs, fruit or other agricultural produce and its parts, Milking machines and dairy machinery

12%

18%

  1.  

LED Lamps, lights and fixture, their metal printed circuits board; 

12%

18%

  1.  

Drawing and marking out instruments

12%

18%

  1.  

Solar Water Heater and system;

5%

12%

  1.  

Prepared/finished leather/chamois leather / composition leathers;

5%

12%

  1.  

Refund of accumulated ITC not to be allowed on flowing goods:

  1. Edible oils
  2. Coal


Services

  1.  

Services supplied by foreman to chit fund

12%

18%

  1.  

Job work in relation to processing of hides, skins and leather

5%

12%

  1.  

Job work in relation to manufacture of leather goods and footwear

5%

12%

  1.  

Job work in relation to manufacture of clay bricks

5%

12%

  1.  

Works contract for roads, bridges, railways, metro, effluent treatment plant, crematorium etc.

12%

18%

  1.  

Works contract supplied to central and state governments, local authorities for historical monuments, canals, dams, pipelines, plants for water supply, educational institutions, hospitals etc. & sub-contractor thereof 

12%

18%

  1.  

Works contract supplied to central and state governments, union territories & local authorities involving predominantly earthwork and sub-contracts thereof

5%

12%

 B.    Other GST rate changes recommended by the Council

S. No.

Description

From

To

Goods

  1.  

Ostomy Appliances

12%

5%

  1.  

Orthopedic appliance- Splints and other fracture appliances; artificial parts of the body; other appliances which are worn or carried, or implanted in the body, to compensate for a defect or disability; intraocular lens

12%

5%

  1.  

Tetra Pak (Aseptic Packaging Paper)

12%

18%

  1.  

Tar (whether from coal, coal gasification plants, producer Gas plants and Coke Oven Plants.

5%/18%

18%

  1.  

IGST on import of Diethylcarbamazine (DEC) tablets supplied free of cost for National Filariasis Elimination Programme

5%

Nil

  1.  

Cut and Polished diamonds

0.25%

1.5%

  1.  

IGST on specified defence items imported by private entities/vendors, when end-user is the Defence forces.

Applicable rate

Nil

Services

1.

Transport of goods and passengers by ropeways.

18%

5% (with ITC of services)

2

Renting of truck/goods carriage where cost of fuel is included

18%

12%

 C Withdrawal of exemptions [Approval of recommendations made by GoM on rate rationalization]

C1.     Hitherto, GST was exempted on specified food items, grains etc when not branded, or right on the brand has been foregone. It has been recommended to revise the scope of exemption to exclude from it prepackaged and pre-labelled retail pack in terms of Legal Metrology Act, including pre-packed, pre-labelled curd, lassi and butter milk.

 C.2    In case of the following goods, exemption from GST will be withdrawn: 

S. No.

Description of goods

From

To

GST rate changes

  1.  

Cheques, lose or in book form

Nil

18%

  1.  

Maps and hydrographic or similar charts of all kinds, including atlases, wall maps, topographical plans and globes, printed

Nil

12%

  1.  

Parts of goods of heading 8801

Nil

18%

 C.3    In case of the following goods, the exemption in form of a concessional rate of GST is being rationalized: 

S. No.

Description of goods

From

To

GST rate changes

  1.  

Petroleum/ Coal bed methane

5%

12%

  1.  

Scientific and technical instruments supplied to public funded research institutes

5%

Applicable rate

  1.  

E-waste

5%

18%

 C4.   In case of Services, following exemptions are being rationalized: 

S. No.

Description


1.

Exemption on transport of passengers by air to and from NE states & Bagdogra is being restricted to economy class

2

Exemption on following services is being withdrawn.

  1. Transportation by rail or a vessel of railway equipment and material.
  2. storage or warehousing of commodities which attract tax (nuts, spices, copra, jaggery, cotton etc.)
  3. Fumigation in a warehouse of agricultural produce.
  4. Services by RBI,IRDA,SEBI,FSSAI,
  5. GSTN.
  6. Renting of residential dwelling to business entities (registered persons).
  7. Services provided by the cord blood banks by way of preservation of stem cells

3.

Like CETPs, common bio-medical waste treatment facilities for treatment or disposal of biomedical waste shall be taxed at 12% so as to allow them ITC

4.

Hotel accommodation priced upto Rs. 1000/day shall be taxed at 12%

5.

Room rent (excluding ICU) exceeding Rs 5000 per day per patient charged by a hospital shall be taxed to the extent of amount charged for the room at 5% without ITC.

6.

Tax exemption on training or coaching in recreational activities relating to arts or culture, or sports is being restricted to such services when supplied by an individual.

D.  GST on casinos, race course and online gaming

The Council directed that the Group of Ministers on Casino, Race Course and Online Gaming re-examine the issues in its terms of reference based on further inputs from States and submit its report within a short duration.

E.  Clarification on GST rate 

E1.  Goods

  1. Electric vehicles whether or not fitted with a battery pack, are eligible for the concessional GST rate of 5%.
  2. All fly ash bricks attract same concessional rate irrespective of fly ash content
  3. Stones covered in S. No.123 of Schedule-I (such as Napa stones), even if they are ready to use and polished in minor ways [not mirror polished], attract concessional GST rate of 5%.
  4. The GST rate on all forms of mango under CTH 0804, including mango pulp (other than mangoes sliced, dried) attract GST at the 12%. Entry is also being amended to make this amply clear. Raw or fresh mangoes continue to be exempt.
  5. Sewage treated water is exempted from GST and is not the same as purified water provided in S. No. 99 of notification 2/2017-CT(Rate). The word 'purified' is being omitted to make this amply clear.
  6. Nicotine Polarilex Gum attracts a GST rate of 18%.
  7. The condition of 90% fly ash content with respect to fly ash bricks applies only to fly ash aggregate, and not fly ash bricks. As a simplification measure, the condition of 90% content is being omitted.

E2 .Clarification in relation to GST rate on Services 

1. Due to ambiguity in GST rates on supply of ice-cream by ice-cream parlours, GST charged @ 5% without ITC on the same during the period 1.07.2017 to 5.10.2021 shall be regularized to avoid unnecessary litigation.

2. Application fee charged for entrance or for issuance of eligibility certificate for admission or issuance of migration certificate by universities is exempt from GST.

3.  Ginned or baled fibre is covered in entry 24B of notification No. 12/2017- Central Tax (Rate) dated 28.06.2017 in the category of raw vegetable fibres. The exemption under this entry is being rationalized

4. Services associated with transit cargo both to and from Nepal and Bhutan are covered by exemption under entry 9B of notification No. 12/2017-CT(R) dated 28.06.2017.

5. Activity of selling of space for advertisement in souvenirs published in the form of books is eligible for concessional GST at 5%.

7. Renting of vehicle with operator for transportation of goods on time basis is classifiable under Heading 9966 (rental services of transport vehicles with operators) and attracts GST at 18%.GST on such renting where cost of fuel is included in the consideration charged is being prescribed at 12%.

8. Allowing choice of location of a plot is part of supply of long term lease of plot of land. Therefore, location charge or preferential location charges (PLC) are part of consideration charged for long term lease of land and shall get the same treatment under GST.

9. Services provided by the guest anchors to TV channels in lieu of honorarium attract GST.

10. Additional fee collected in the form of higher toll charges from vehicles not having Fastag is essentially payment of toll for allowing access to roads or bridges to such vehicles and shall be given the same tax treatment as given to toll charges.

11. Services in form of Assisted Reproductive Technology (ART)/ In vitro fertilization (IVF) are covered under the definition of health care services for the purpose of exemption under GST.

12. Sale of land after leveling, laying down of drainage lines etc. is sale of land and does not attract GST.

13. Renting of motor vehicles for transport of passengers to a body corporate for a period (time) is taxable in the hands of body corporate under RCM.

14. The expression ‘public transport’ used in the exemption entry at SI No. 17(d) of notification No. 12/2017-CT(R), which exempts transport of passengers by public transport other than predominantly for tourism purpose, in a vessel between places located in India, means that such transport should be open to public for point to point transport [e.g. such transport in Andaman and Nicobar islands].

Other miscellaneous changes 

1. All taxable service of Department of Posts would be subject to forward charge. Hitherto certain taxable services of Department of post were taxed on reverse charge basis.

2. Goods transport agency (GTA) is being given option to pay GST at 5% or 12% under forward charge; option to be exercised at the beginning of Financial Year. RCM option to continue.

3.  Service provided by Indian Tour operator to a foreign resident for a tour partially in India and partially outside India is to be subject to tax proportionate to the tour conducted in India for such foreign tourist subject to conditions that this concession does not exceed half of tour duration.

The rate changes recommended by the 47th GST Council will be made effective from 18th July, 2022.

II. Further, the GST Council has inter-alia made the following recommendations relating to GST law and procedure:

 A.Measures for Trade facilitation: 

  1. In-principal approval for relaxation in the provisions for suppliers making supplies through E-Commerce Operators (ECOs)


  1. Waiver of requirement of mandatory registration under section 24(ix) of CGST Act for person supplying goods through ECOs, subject to certain conditions, such as-
    1.  the aggregate turnover on all India basis does not exceed the turnover specified under sub-section (1) of section 22 of the CGST Act and notifications issued thereunder.
    2.  the person is not making any inter-State taxable supply
  1. Composition taxpayers would be allowed to make intra-State supply through e-commerce operators subject to certain conditions.

 The details of the scheme will be worked out by the Law Committee of the Council. The scheme would be tentatively implemented with effect from 01.01.2023, subject to preparedness on the portal as well as by ECOs.

  1. Amendment in formula prescribed in sub-rule (5) of rule 89 of CGST Rules, 2017 for calculation of refund of unutilized Input Tax Credit on account of inverted rated structure
  1. Change in formula for calculation of refund under rule 89(5) to take into account utilization of ITC on account of inputs and input services for payment of output tax on inverted rated supplies in the same ratio in which ITC has been availed on inputs and input services during the said tax period. This would help those taxpayers who are availing ITC on input services also.
  1. Amendment in CGST Rules for handling of pending IGST refund claims: In some cases where the exporter is identified as risky exporter requiring verification by GST officers, or where there is a violation of provisions of Customs Act, the refund claims in respect of export of goods are suspended/withheld.

Amendment in rule 96 of the CGST Rules has been recommended to provide for transmission of such IGST refund claims on the portal in a system generated FORM GST RFD-01 to the jurisdictional GST authorities for processing. This would result in expeditious disposal of such IGST refund claims, after due verification by GST officers, thus benefitting such exporters.

  1. Re-credit of amount in electronic credit ledger to be provided in those cases where erroneous refund amount sanctioned to a taxpayer on account of accumulated ITC or on account of IGST paid on zero rated supply of goods or services, in contravention of rule 96(10) of the CGST Rules, is deposited by him along with interest and penalty, wherever applicable. A new FORM GST PMT-03Ais introduced for the same.

This will enable the taxpayers to get re-credit of the amount of erroneous refund, paid back by them, in their electronic credit ledger.

  1. Clause (c) of section 110 and section 111 of the Finance Act, 2022 to be notified by Central Government at the earliest. These provisions relate to-
  1. retrospective amendment in section 50(3) of CGST Act, with effect from 01.07.2017,to provide that interest will be payable on the wrongly availed ITC only when the same is utilized;
  2. amendment in sub-section (10) of section 49 of CGST Act to provide for transfer of balance in electronic cash ledger of a registered person to electronic cash ledger of CGST and IGST of a distinct person.

 The rules providing for the manner of calculation of interest under section 50 of CGST Act have also been recommended for more clarity. This will remove ambiguities regarding manner of calculation of interest and will also provide for transfer of balance in CGST and IGST cash ledgers between distinct persons, thereby improving liquidity and cash flows of such taxpayers. 

  1. Waiver of late fee for delay in filing FORM GSTR-4 for FY 2021-22 and extension of due date for filing FORM GST CMP-08 for Q1 of FY 2022-23:
  1. To extend the waiver of late fee under section 47 for delay in filing FORM GSTR-4 for FY 2021-22 by approximately four more weeks, i.e. till 28.07.2022 (The existing waiver is for the period from 01.05.2022 till 30.06.2022)
  2. To extend the due date of filing of FORM GST CMP-08 for the 1st quarter of FY 2022-23 from 18.07.2022 to 31.07.2022.

GSTN has also been asked to expeditiously resolve the issue of negative balance in Electronic Cash Ledger being faced by some of the composition taxpayers. 

  1. Present exemption of IGST on import of goods under AA/EPCG/EOU scheme to be continued and E-wallet scheme not to be pursued further. 
  2. Issuance of the following circulars in order to remove ambiguity and legal disputes on various issues, thus benefiting taxpayers at large:
  3. Clarification on issue of claiming refund under inverted duty structure where the supplier is supplying goods under some concessional notification.
  4. Clarification on various issues relating to applicability of demand and penalty provisions under the CGST Act in respect of transactions involving fake invoices.
  5. Clarification on mandatory furnishing of correct and proper information of inter-State supplies and amount of ineligible/blocked Input Tax Credit and reversal thereof in return in FORM GSTR-3B.
  6. Clarification in respect of certain GST related issues:
    1. Clarification on the issues pertaining to refund claimed by the recipients of supplies regarded as deemed export;
    2. Clarification on various issues relating to interpretation of section 17(5) of the CGST Act;
    3. Clarification on the issue of perquisites provided by employer to the employees as per contractual agreement;
    4. Clarification on utilization of the amounts available in the electronic credit ledger and the electronic cash ledger for payment of tax and other liabilities. 
  7. Exemption from filing annual return in FORM GSTR-9/9A for FY 2021-22 to be provided to taxpayers having AATO upto Rs. 2 crores. 
  8. Explanation 1 after rule 43 of CGST Rules to be amended to provide that there is no requirement of reversal of input tax credit for exempted supply of Duty Credit Scrips by the exporters. 
  9. UPI & IMPS to be provided as an additional mode for payment of Goods and Services Tax to taxpayers under Rule 87(3) of CGST Rules. 
  10. In respect of refunds pertaining to supplies to SEZ Developer/Unit, an Explanation to be inserted in sub-rule (1) of rule 89 of CGST Rules to clarify that “specified officer” under the said sub-rule shall mean the “specified officer” or “authorized officer”, as defined under SEZ Rules, 2006. 
  11. Amendment in CGST Rules to provide for refund of unutilized Input Tax Credit on account of Export of Electricity. This would facilitate the exporters of electricity in claiming refund of utilized ITC on zero rated supplies. 
  12. Supplies from Duty Free Shops (DFS) at international terminal to outgoing international passengers to be treated as exports by DFS and consequential refund benefit to be available to them on such supplies. Rule 95A of the CGST Rules, Circular No. 106/25/2019-GST dated 29.06.2019 and related notifications to be rescinded accordingly. 

B. Measures for streamlining compliances in GST 

  1. Provision for automatic revocation of suspension of registration in cases where suspension of registration was done by the system under Rule 21A(2A) of CGST Rules, for non-compliance in terms of clause (b) or clause (c) of sub-section (2) of section 29[continuous non-filing of specified number of returns], once all the pending returns are filed on the portal by the taxpayer. (Amendment in rule 21A) 
  2. Proposal for comprehensive changes in FORM GSTR-3B to be placed in public domain for seeking inputs/suggestions of the stakeholders. 
  3. Time period from 01.03.2020 to 28.02.2022 to be excluded from calculation of the limitation period for filing refund claim by an applicant under section 54 and 55 of CGST Act, as well as for issuance of demand/ order (by proper officer) in respect of erroneous refunds under section 73 of CGST Act. Further, limitation under section 73 for FY 2017-18 for issuance of order in respect of other demands linked with due date of annual return, to be extended till 30th September, 2023. 

C. The Council has decided to constitute a Group of Ministers to address various concerns raised by the States in relation to constitution of GST Appellate Tribunal and make recommendations for appropriate amendments in CGST Act. 

D. The GST Council approved ad-hoc apportionment of IGST to the extent of Rs. 27,000 crores and release of 50% of this amount, i.e. Rs. 13,500 crore to the States. 

E.   The GoM on IT Reforms, inter alia, recommended that the GSTN should put in place the AI/ML based mechanism to verify the antecedents of the registration applicants and an improved risk-based monitoring of their behavior post registration so that non-compliant tax payers could be identified in their infancy and appropriate action be taken so as to minimize risk to exchequer. 

Note: The recommendations of the GST Council have been presented in this release containing major item of decisions in simple language for information of all stakeholders. The same would be given effect through relevant Circulars/ Notifications/ Law amendments which alone shall have the force of law. 

Topics

Acts Income Tax