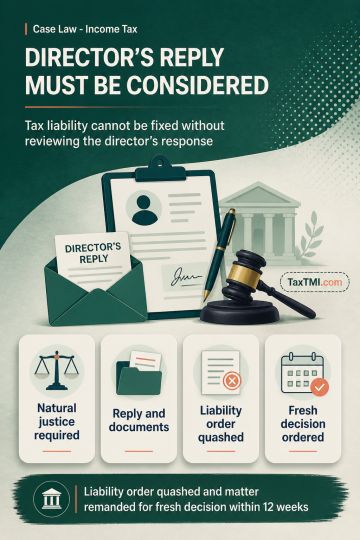
GST payment representations require record-based, reasoned decisions while substantive entitlement remains open for determination by competent authori...
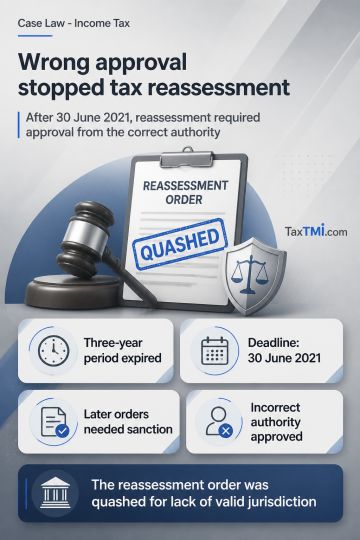
Reassessment sanction under extended limitation required approval from the competent specified authority, invalidating proceedings approved by an inco...
Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment...
Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments...
Dispute Resolution Panel directions bind the Assessing Officer when passing the final assessment order. Retaining a transfer-pricing adjustment despite directed relief is not a clerical error capable of rectification where the Transfer Pricing Officer and Assessing Officer consciously adopted the adjustment contrary to those directions; the final assessment order is consequently bad in law. Under the Other Method, arm's length pricing of intra-group technical and shared services requires comparable uncontrolled transactions or a stated basis for the valuation. The Transfer Pricing Officer cannot test commercial benefit and cannot determine a nil arm's length price on an ad hoc basis where evidence of service receipt and cost allocation remains undiscredited. The consequential transfer-pricing addition is deleted.
Dispute Resolution Panel directions bind the Assessing Officer when passing the final assessment order. Retaining a transfer-pricing adjustment despite directed relief is not a clerical error capable of rectification where the Transfer Pricing Officer and Assessing Officer consciously adopted the adjustment contrary to those directions; the final assessment order is consequently bad in law. Under the Other Method, arm's length pricing of intra-group technical and shared services requires comparable uncontrolled transactions or a stated basis for the valuation. The Transfer Pricing Officer cannot test commercial benefit and cannot determine a nil arm's length price on an ad hoc basis where evidence of service receipt and cost allocation remains undiscredited. The consequential transfer-pricing addition is deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4931