Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
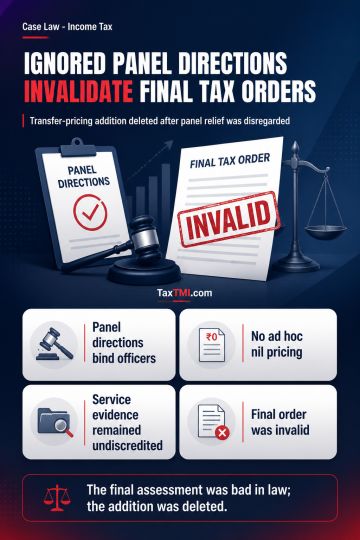
Dispute Resolution Panel directions bind the Assessing Officer when passing the final assessment order. Retaining a transfer-pricing adjustment despite directed relief is not a clerical error capable of rectification where the Transfer Pricing Officer and Assessing Officer consciously adopted the adjustment contrary to those directions; the final assessment order is consequently bad in law. Under the Other Method, arm's length pricing of intra-group technical and shared services requires comparable uncontrolled transactions or a stated basis for the valuation. The Transfer Pricing Officer cannot test commercial benefit and cannot determine a nil arm's length price on an ad hoc basis where evidence of service receipt and cost allocation remains undiscredited. The consequential transfer-pricing addition is deleted.
Dispute Resolution Panel directions bind the Assessing Officer when passing the final assessment order. Retaining a transfer-pricing adjustment despite directed relief is not a clerical error capable of rectification where the Transfer Pricing Officer and Assessing Officer consciously adopted the adjustment contrary to those directions; the final assessment order is consequently bad in law. Under the Other Method, arm's length pricing of intra-group technical and shared services requires comparable uncontrolled transactions or a stated basis for the valuation. The Transfer Pricing Officer cannot test commercial benefit and cannot determine a nil arm's length price on an ad hoc basis where evidence of service receipt and cost allocation remains undiscredited. The consequential transfer-pricing addition is deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI