 TaxTMI
 TaxTMI


 03 Nov 2026

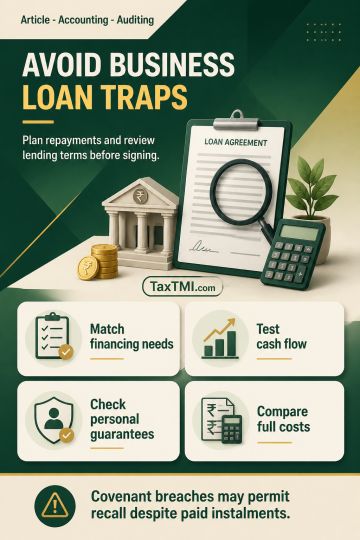
Debt can accelerate a sound business. Taken for the wrong reason, in the wrong form or on unread terms, it can bury one. Here is what advisers should test first.
In April 2019 Jet Airways, once among India's most admired private carriers, grounded its entire fleet. For months it had chased emergency funding while employees, lessors and vendors went unpaid. When lenders declined to advance more interim money, the aircraft stopped flying.
Thousands lost their jobs almost overnight. Aviation has its own pressures, but the lesson travels: a business that needs fresh borrowing just to keep operating has already lost control of its future.
Debt's double reputation
Some promoters treat debt as poison: "We'll never borrow." Others treat it as routine: "Interest is just a cost of doing business." Both attitudes can hurt.
Used well, debt finances productive assets and working capital and lets a firm grow faster than its own cash allows - without diluting ownership. Used badly, it turns a passing difficulty into a permanent one.
The loan itself is rarely what decides the outcome. What decides it is the reason for borrowing, the structure of the facility and the discipline once the money arrives.
An old lesson, frequently misquoted
In Hamlet, the courtier Polonius tells his son: "Neither a borrower nor a lender be; for loan oft loses both itself and friend."
It gets quoted as wisdom, yet Shakespeare gave the line to a partly comic figure, and absolute rules about debt rarely survive real commerce. Railways, factories and ports the world over were built on borrowed money.
The sounder lesson comes from traditions that condemned not borrowing as such but borrowing that enslaves - debt taken on with no means of repayment. The question is never "borrow or not?" but "will this loan serve the business, or will the business end up serving the loan?"
The uncomfortable reality
Many businesses don't borrow to grow. They borrow to get through a problem they haven't yet admitted to.
Losses get funded through the cash-credit limit. Overdue taxes get cleared with a personal loan. Salaries go on a credit card. Supplier dues are settled with costly money from a private financier.
Each loan buys a few weeks. None touches the cause.
Borrowing to cover losses doesn't buy time. It mortgages the future to pay for the past.
Seven of the costliest borrowing mistakes
1. Short money for long assets
A machine that earns for seven years shouldn't sit on a working-capital limit renewed annually; every renewal becomes a crisis.
Remedy: match tenure to the asset's useful life.
2. No identified repayment source
If the honest answer to "how will this be repaid?" is "the next loan," it's a refinancing problem, not a funding solution.
Remedy: model the cash flows that will service the loan, including a realistic downside.
3. Personal guarantees signed blind
A guarantee can make the promoter personally liable for company debt - putting savings, property and family security on the line even where the borrower is a limited company.
Remedy: read every guarantee, negotiate caps on amount and duration, keep a register of guarantees given and seek releases when loans are repaid or restructured.
4. Covenants nobody tracks
Facility agreements often set minimum net worth, maximum gearing or minimum DSCR, and restrict dividends, further borrowing or changes in ownership. A breach can let the lender recall the loan even if every instalment was paid.
Remedy: list all covenants in a tracker and test compliance quarterly.
5. Chasing the lowest headline rate
A low rate can conceal processing fees, prepayment penalties, bundled insurance, extra collateral and restrictive conditions.
Remedy: compare all-in cost and flexibility, not the rate alone.
6. Turning to informal lenders
When banks say no, some owners go to private lenders charging punishing rates with aggressive recovery.
Remedy: treat the refusal as information. Ask why - the reason often points to fixable issues such as weak books, poor cash flow or compliance gaps.
7. Missing payments in silence
Delays happen; silence makes them worse. In India, overdue loan accounts are flagged as SMA-0, SMA-1 and SMA-2 and, generally after 90 days, classified as non-performing - damaging credit records for years.
Remedy: if a delay is coming, speak to the lender early and explore restructuring before the account slips.
In a nutshell
Essence: debt turns into a trap when its purpose is to hide losses, its tenure doesn't fit the asset, its repayment rests on hope and its terms were never read.
The 4-R Borrowing Test
Before any facility, answer four questions. A weak answer to any one means stop.
| Test | Question | Healthy answer |
| Reason | What precisely is the money for? | A productive asset or a genuine timing gap - not recurring losses |
| Repayment | Where will repayment come from, and when? | Normal operating cash flow, even in a weaker year |
| Risk | What if revenue falls 20%? | We can still pay - perhaps with cost cuts, but without new borrowing |
| Rules | What have we agreed to? | Covenants, guarantees, security and fees understood and tracked |
The ratios lenders watch - and clients should too
- Debt service coverage ratio (DSCR): cash available for debt service / principal and interest due; lenders typically want a comfortable margin above 1.
- Debt-to-equity: how much of the business is funded by borrowings versus owners' funds.
- Interest coverage: operating profit / interest; thin cover means a small dip in profit makes interest unaffordable.
- Working-capital cycle: how long cash is locked between paying suppliers and collecting from customers.
Track them monthly. If they deteriorate, the client should know before the bank says so.
For practitioners: the pre-sanction review
- Prepare a CMA-style projection honestly. Base projections on achievable sales and realistic collection days; inflated projections create covenants the client can't meet.
- Build a covenant tracker from the sanction letter and facility agreement, with test dates and current headroom.
- Register charges on time. For companies, ensure charges are created, modified and satisfied with the Registrar within prescribed timelines.
- Check loans from related parties. Director, shareholder and inter-corporate loans need review under deposit and related-party rules, and cash loans of Rs. 20,000 or more must be avoided.
- Explore guaranteed schemes. Where the client qualifies, CGTMSE-backed collateral-free credit may reduce the need for personal guarantees and property mortgages.
Indicators of success
- Interest cover at least two to three times.
- Debt relative to operating cash flow repayable within a few years.
- Matching - short-term borrowing funds short-term needs, term loans fund long-term assets.
- No covenant breaches, with comfortable headroom.
- Purpose tracking - each loan traceable to the asset or need it financed.
Outlook: the coming decade
Credit is getting faster and more data-driven. Account-aggregator data, GST returns and UPI flows let lenders approve within days - and cut limits just as quickly when numbers weaken. Rates will rise and fall, but the near-zero era is unlikely to return soon. Easier access to credit makes discipline more important, not less.
Immediate actions by role
- Owner: list every loan with its rate, purpose, maturity and what it financed.
- CFO: run the 4-R Test on any borrowing planned for the next six months.
- Operations head: find stock or debtors that could be reduced instead of borrowing.
- Board or advisers: set a ceiling on debt relative to cash flow.
Illustration from a smaller enterprise
Take an illustrative furniture maker that buys new machinery on its overdraft because that's quicker than arranging a term loan. Six months later a slow season arrives, the overdraft is fully drawn and suppliers can't be paid. Refinancing the machinery with a five-year term loan frees the overdraft for its real job - working capital - and ends the monthly crisis.
A word on personal guarantees
Many small-business loans in India require the promoter's personal guarantee, which means a business setback can swiftly become a household one - property, savings and personal credit history all exposed. Before signing, read the deed, understand which assets it reaches and negotiate a cap or a release as the loan is paid down. A guarantee isn't a formality. It's the family standing behind a business decision.
The objection we hear most - and our response
The objection: "Debt is cheaper than equity. Every finance textbook says some leverage boosts returns. Fear of debt means growing too slowly."
The answer: True, within limits. Moderate, well-structured debt raises returns and avoids dilution. But leverage magnifies outcomes both ways: the borrowing that doubles return on equity in a good year can erase equity in a bad one. The textbooks also assume borrowers understand their covenants, match tenure to assets and can ride out downturns. Use debt the way the textbooks describe - not as a stand-in for profit.
Practitioners' FAQ
"Is debt better than equity?"
Debt preserves ownership but adds fixed obligations; equity shares ownership but not repayment. Choose based on cash-flow stability and risk appetite.
"What should be checked before signing?"
Rate, fees, covenants, security, personal guarantees and the repayment schedule against realistic cash flows.
"What if repayments can't be met?"
Approach the lender early; restructuring is easier before default than after.
Position as at October 2026: Indian MSMEs can access collateral-free credit under schemes backed by the Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE), subject to eligibility, and the RBI's frameworks govern restructuring of stressed accounts. Cash loans of Rs. 20,000 or more remain restricted under income-tax law (now the Income-tax Act, 2025). Interest rates and scheme terms change - check current conditions.
Pitfalls
- Borrowing simply because credit was offered.
- Treating a working-capital limit as permanent capital.
- Signing bank documents in a hurry.
- Mixing loan proceeds with personal spending.
- Waiting for a crisis before reviewing the debt structure.
Half-hour action exercise
Build a one-page debt register:
1. Every loan, overdraft, card and lease - lender, amount, rate, tenure, security.
2. Every personal guarantee signed.
3. Every covenant and its test date.
4. Last year's DSCR.
5. One scenario: revenue down 20% for six months - can the client still pay?
Any line that surprises is the first agenda item for the next adviser or lender meeting.
Summary for busy professionals
- Debt works when it funds productive assets or genuine timing gaps with a clear repayment source.
- The costliest errors: short money for long assets, no repayment source, careless guarantees, untracked covenants, headline-rate chasing, informal lenders and silent defaults.
- Apply the 4-R Test: Reason, Repayment, Risk, Rules.
- Monitor DSCR, gearing, interest cover and the working-capital cycle monthly.
- Leverage cuts both ways - use it to build, never to hide losses.
Borrow to build. Never borrow to avoid facing the truth.
References
- Public reporting on the suspension of Jet Airways operations (April 2019) and subsequent insolvency proceedings under the Insolvency and Bankruptcy Code.
- William Shakespeare, Hamlet, Act 1, Scene 3 (public domain).
- Reserve Bank of India, Master Circular on Income Recognition, Asset Classification and Provisioning (SMA and NPA norms). rbi.org.in
- Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE). cgtmse.in
- Aswath Damodaran, Applied Corporate Finance (Wiley, 4th edition, 2014) - on optimal leverage.