 TaxTMI
 TaxTMI


 02 Nov 2026

It begins with one school-fee payment from the current account. Years later nobody - not the bank, not the auditor, not the owner - can say what the business really earns.
In 1897 Britain's highest court heard a dispute about a leather merchant called Aron Salomon. His company had collapsed, and its creditors argued that Salomon personally should meet its debts.
The House of Lords refused. A properly incorporated company, it held, is a legal person separate from its owner - even where the owner holds nearly all the shares.
Salomon v Salomon & Co is still a staple of law and accounting courses worldwide, and it carries a warning many clients miss: the law treats the business as separate from you. Behave as if it isn't, and you lose the benefits of that separation.
"It's my business, so it's my money"
Most owners have said it or thought it:
- School fees paid from the business account.
- A family holiday on the company card.
- A supplier settled from a personal UPI ID because it was quicker.
- Cash sales pocketed "to be adjusted later."
Each choice feels minor and convenient. Together they produce a business nobody can read - not the bank, not the auditor, not the tax department and, eventually, not even the owner.
Lesson from history: the entity concept
Accounting rests on the business entity concept: the business is treated as distinct from its owner, and its books record only its own transactions. When Luca Pacioli set out double-entry bookkeeping in Venice in 1494, merchants were already keeping the affairs of a venture apart from their household.
Five centuries on, the principle hasn't changed because the problem hasn't: a business whose money is tangled with its owner's life can't measure itself.
Why mixing money is more dangerous than it looks
1. Profitability disappears from view
Personal costs booked in the business make profit look lower; business costs paid personally and never recorded make it look higher. Either way, decisions on pricing, costs and margins rest on false numbers.
2. Tax exposure climbs
Personal expenses claimed as business expenses get disallowed, with tax, interest and penalties. Unexplained deposits in personal accounts can be taxed as income. Business receipts in personal accounts raise questions under both income tax and GST.
Tax systems now match bank data, GST returns, TDS records and reported high-value transactions automatically. Inconsistencies surface far more easily than most owners believe.
3. Limited liability can wear thin
A key reason to form a company or LLP is to ring-fence personal assets from business liabilities - the protection Salomon confirmed. Courts generally respect it, but when owners treat company money as their own, creditors and courts look harder at whether the separation is genuine, and misuse of company funds can create personal liability.
4. Lenders lose confidence
Banks and NBFCs compare bank statements, financials and tax returns. When business income flows through personal accounts and family expenses run through the business, nothing reconciles - so limits shrink, rates rise, collateral demands grow, or the proposal is declined.
5. Company-law complications
Money taken by a director outside a proper salary, dividend or documented loan creates legal problems. Loans to directors and related parties are regulated under India's Companies Act, among others, and dividends may be paid only out of distributable profits.
6. Business value drops
Buyers and investors want clean, verifiable earnings. Profits that need the owner to explain which costs were "really personal" are heavily discounted - or simply not believed.
In a nutshell
Essence: mixed money hides profit, invites tax disputes, weakens legal protection, unsettles lenders and lowers value - all at once.
The uncomfortable reality
Most owners mix money not out of dishonesty but because they never set up the business as a separate entity in their own minds. It was born from their savings, run from their phone and funded by family; separation feels artificial.
But once there are customers, employees, lenders or tax obligations, it's no longer only the owner's money. Other people depend on it.
Discipline with money isn't distrust of yourself. It's respect for everyone who relies on the business.
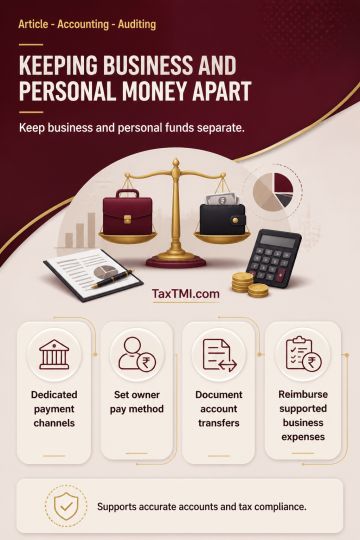
The Three Walls
The simplest way to keep money clean is three walls between owner and business.
Wall 1: Separate channels
Every business - sole proprietorships included - needs its own bank account, payment gateway, UPI handle and card. All business receipts in, all business payments out, nothing personal passing through.
Wall 2: Defined pay
A clear method of paying the owner: salary or remuneration, drawings for proprietors and partners, dividends for shareholders, or documented loans - at a regular amount the business can afford, not whatever happens to be in the account.
Wall 3: Documented crossings
When money does cross the wall, record it properly:
- A personal expense paid by the business goes to drawings or an amount receivable from the owner - never to expenses.
- A business expense paid personally is reimbursed through the business against the bill.
- Loans either way are documented with terms and any approvals the law requires.
Supporting habits
- Bank every cash sale. Cash outside the books is one of the commonest reasons declared income and lifestyle don't match.
- Reconcile monthly. Unexplained entries get harder to explain each month they're left.
- Pay staff and suppliers through banking channels, with records.
For practitioners: cleaning up a mixed client
- Run a two-account review. Lay business and personal statements side by side for twelve months and tag every crossing before finalising accounts.
- Clear the suspense and owner's account. Reclassify to drawings, capital, reimbursements or loans with support; don't carry unexplained balances forward.
- Reconcile to AIS and GST data. Compare reported receipts, TDS credits and high-value transactions with the books before filing, and resolve differences.
- Check director-loan compliance. For companies, review loans and advances to directors and related parties against Companies Act restrictions and approvals.
- Fix a monthly owner-pay figure. Document salary or remuneration in board or partner resolutions so deductibility and drawings are both defensible.
Indicators of success
- The business bank statement contains no personal spending.
- Owner withdrawals happen as salary, dividend or documented loan - not random transfers.
- The monthly close finishes without a suspense or owner's account full of mysteries.
- Lenders and auditors stop asking the same questions every year.
Outlook: the coming decade
Tax authorities already match bank data, GST returns, card spends and property records automatically, and banks assess credit using account-aggregator data. Mixing money will show up in systems long before an auditor notices it. Clients with clean walls will find credit cheaper and scrutiny lighter; those without will find both harder.
Immediate actions by role
- Owner: open a separate personal account for household spending and stop using the business card personally.
- Accountant: reclassify last year's mixed transactions and agree a monthly owner-pay amount.
- Family members on payroll: confirm each has a real role and documented work.
- Banker: ask what clean accounts would do to the limit and the rate.
Illustration from a smaller enterprise
Take an illustrative hardware-shop owner paying school fees, household bills and holidays from the shop's current account. On paper profit looks thin, so the bank declines a higher working-capital limit. Once he separates accounts and draws a fixed monthly salary, the shop's true profit becomes visible. The following year the bank approves the higher limit - at a lower rate.
What the lender actually sees
When a lender reviews a small business, mixed accounts send three signals: profit may be understated, controls may be weak, and the owner may treat the business as a personal wallet. Each raises perceived risk. Separating money isn't only about tax and discipline; it decides how cheaply the world will lend.
The objection we hear most - and our response
The objection: "I'm a sole proprietor. Legally the business is me. Why pretend otherwise?"
The answer: In law, proprietor and business are one person. Financially and practically, separation still matters: the owner still needs to know whether the business makes money, still files returns on business income, still needs loans assessed on business cash flow - and may one day convert to a company, take a partner or sell. For proprietors, separate accounts aren't a legal fiction. They're the only way to see the business clearly.
What the owner gains
Separation increases freedom rather than limiting it:
- The owner knows what the business truly earns.
- They know how much they can safely draw.
- Tax filings become defensible.
- Lenders see a clear picture and offer better terms.
- The business becomes something that can be valued, sold or passed on.
Pitfalls
- "We'll adjust it at year-end" - memory-based adjustments are rarely accurate.
- Routing receipts through a spouse's or relative's account.
- Paying staff or suppliers in cash without records.
- Treating the business account as the family's emergency fund.
- Assuming small amounts don't matter - repeated for years, they aren't small.
Practitioners' FAQ
"How should an owner pay themselves?"
Through a fixed salary, dividends or documented loans - decided in advance and properly recorded.
"Can business assets be used personally?"
Only under clear policies with correct accounting and tax treatment; informal mixing causes problems.
"What if money is already mixed?"
Open separate accounts now, reclassify past transactions with the accountant and follow the new rules from today.
Position as at October 2026: In India, the Income-tax Act, 2025 (in force from 1 April 2026) continues rules on unexplained credits, cash transactions above set limits and disallowance of personal expenses, under new section numbers. Annual information statements show many high-value transactions to tax authorities. Companies Act restrictions on loans to directors and on dividends continue. Check current provisions with your adviser.
Half-hour action exercise
Put last month's business and personal bank statements side by side and mark:
1. Every business receipt that landed in the personal account.
2. Every personal expense paid from the business account.
3. Every business expense paid personally.
Total each column, then ask: could every large deposit in the personal account be explained to a tax officer, with documents? Next, open a separate business account or UPI handle if one doesn't exist, and fix the monthly pay figure.
Summary for busy professionals
- Law and accounting both treat a business as separate from its owner - Salomon v Salomon (1897) and the entity concept.
- Mixing money hides profit, raises tax risk, weakens limited liability, worries lenders and cuts value.
- Build the Three Walls: separate channels, defined pay, documented crossings.
- Bank every cash sale, reconcile monthly, use banking channels.
- Separation is the foundation for growth, credit and a business that outlives its owner.
A business blended into its owner's life can only ever grow as large as the owner's memory.
References
- Salomon v A Salomon & Co Ltd [1897] AC 22 (House of Lords).
- Luca Pacioli, Summa de arithmetica, geometria, proportioni et proportionalita (Venice, 1494) - the treatise on bookkeeping.
- Companies Act, 2013 (India), sections on loans to directors and declaration of dividends.
- Income Tax Department of India - Annual Information Statement (AIS) guidance. incometax.gov.in