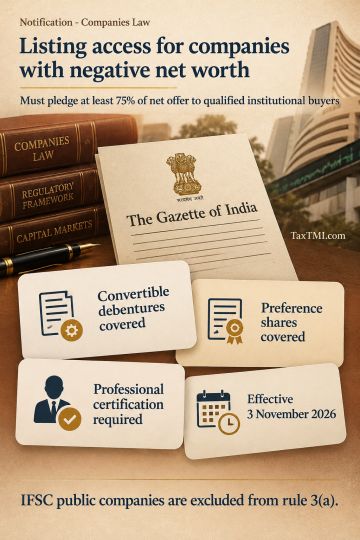
Equity instrument listings in permissible jurisdictions cover convertible debentures and preference shares, with conditional eligibility for negative-...
The India-UK DTAA's make available test requires the recipient...
Make available test excludes IT and standard software charges from technical services taxation where recipients acquire no independent technical capability.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
The India-UK DTAA's make available test requires the recipient to acquire technical knowledge or know-how that can be used independently, without further assistance from the service provider. IT and shared information service charges do not qualify as fees for technical services where the recipient acquires no such capability. Charges for standard third-party software procured for group affiliates on a cost-to-cost basis also fall outside fees for technical services where the test is not met. Managerial services are excluded from fees for technical services under Article 13(4), including managerial group support services.
The India-UK DTAA's make available test requires the recipient to acquire technical knowledge or know-how that can be used independently, without further assistance from the service provider. IT and shared information service charges do not qualify as fees for technical services where the recipient acquires no such capability. Charges for standard third-party software procured for group affiliates on a cost-to-cost basis also fall outside fees for technical services where the test is not met. Managerial services are excluded from fees for technical services under Article 13(4), including managerial group support services.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI







 Get Daily Updates


