Equity instrument listings in permissible jurisdictions cover convertible debentures and preference shares, with conditional eligibility for negative-...
The listing rules define equity instruments to include equity...
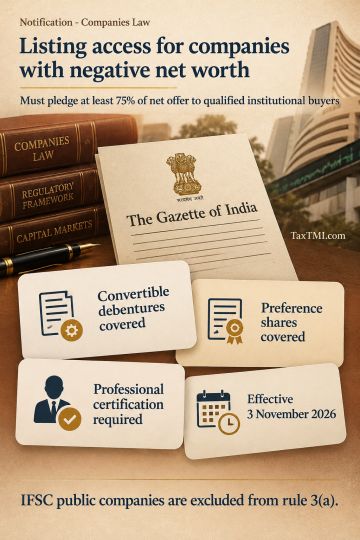
Equity instrument listings in permissible jurisdictions cover convertible debentures and preference shares, with conditional eligibility for negative-net-worth companies.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
The listing rules define equity instruments to include equity shares, convertible debentures and preference shares issued by Indian companies. Unlisted public companies in International Financial Services Centres fall within the rules subject to compliance with applicable IFSC law and regulations, while public companies in that jurisdiction are excluded from rule 3(a). Companies with negative net worth may issue instruments for listing if they undertake to allot at least 75% of the net offer to qualified institutional buyers under the relevant jurisdiction's securities regulations. Rule 5(e) replaces "two years" with "more than six months", and rule 5(g) adds that the specified default must remain unremedied. The replacement Form LEAP-1 requires prospectus-related attachments, disclosure of inspection, investigation or inquiry, and professional certification. The amendments took effect on 3 November 2026.
The listing rules define equity instruments to include equity shares, convertible debentures and preference shares issued by Indian companies. Unlisted public companies in International Financial Services Centres fall within the rules subject to compliance with applicable IFSC law and regulations, while public companies in that jurisdiction are excluded from rule 3(a). Companies with negative net worth may issue instruments for listing if they undertake to allot at least 75% of the net offer to qualified institutional buyers under the relevant jurisdiction's securities regulations. Rule 5(e) replaces "two years" with "more than six months", and rule 5(g) adds that the specified default must remain unremedied. The replacement Form LEAP-1 requires prospectus-related attachments, disclosure of inspection, investigation or inquiry, and professional certification. The amendments took effect on 3 November 2026.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI







 Get Daily Updates


