Inland gold seizures require evidence of smuggling when local purchase records establish procurement, while cash confiscation requires a smuggling lin...
Non-resident rights subscriptions require compliant existing shareholdings, while penalty proportionality depends on the circumstances of the transact...
Construction consultancy meeting competing service descriptions follows the earlier classification entry when specificity and essential character cann...
Digital onboarding for overseas individual investors permits remote KYC from FATF-compliant countries while preserving verification and audit safeguar...
Real estate insolvency compliance requires access to regulatory records, prominent site disclosures and continued adherence to property law during res...
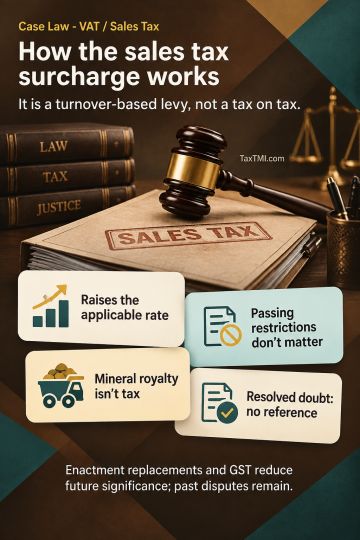
Sales tax surcharge calculated on the tax payable by a dealer enhances the sales tax rate under former Entry 54 of List II; it is not a tax on tax or income. The subject of a tax is distinct from its measure, and liability follows turnover rather than profit. Restrictions on passing the surcharge to purchasers do not change its character. Mineral royalty is not a tax, and a cess on that royalty concerns a different legislative field. A larger-Bench reference requires a continuing unresolved doubt; binding authority resolving it removes its purpose. Replacement of the relevant enactments and the transition to GST reduce prospective significance without extinguishing disputes over past liabilities.
Sales tax surcharge calculated on the tax payable by a dealer enhances the sales tax rate under former Entry 54 of List II; it is not a tax on tax or income. The subject of a tax is distinct from its measure, and liability follows turnover rather than profit. Restrictions on passing the surcharge to purchasers do not change its character. Mineral royalty is not a tax, and a cess on that royalty concerns a different legislative field. A larger-Bench reference requires a continuing unresolved doubt; binding authority resolving it removes its purpose. Replacement of the relevant enactments and the transition to GST reduce prospective significance without extinguishing disputes over past liabilities.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI





 Get Daily Updates


