Inland gold seizures require evidence of smuggling when local purchase records establish procurement, while cash confiscation requires a smuggling lin...
Non-resident rights subscriptions require compliant existing shareholdings, while penalty proportionality depends on the circumstances of the transact...
Construction consultancy meeting competing service descriptions follows the earlier classification entry when specificity and essential character cann...
Digital onboarding for overseas individual investors permits remote KYC from FATF-compliant countries while preserving verification and audit safeguar...
Real estate insolvency compliance requires access to regulatory records, prominent site disclosures and continued adherence to property law during res...
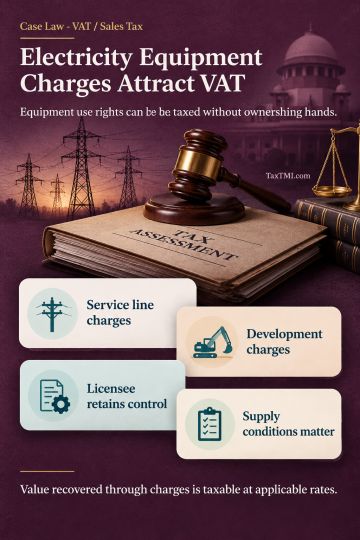
Transfer of the right to use electricity distribution equipment can attract tax under Section 4(8) of the Andhra Pradesh Value Added Tax Act, 2005, without a transfer of ownership. Recovery of equipment costs or installation at a consumer's premises is not conclusive; the statutory framework and supply conditions must also be examined. Service line and development charges recover the value of goods used in activities incidental or ancillary to electricity supply. The transaction as a whole can transfer the right to use those goods for receiving electricity even where the licensee retains operational control and maintenance responsibility. The value recovered through the charges is then taxable at applicable rates.
Transfer of the right to use electricity distribution equipment can attract tax under Section 4(8) of the Andhra Pradesh Value Added Tax Act, 2005, without a transfer of ownership. Recovery of equipment costs or installation at a consumer's premises is not conclusive; the statutory framework and supply conditions must also be examined. Service line and development charges recover the value of goods used in activities incidental or ancillary to electricity supply. The transaction as a whole can transfer the right to use those goods for receiving electricity even where the licensee retains operational control and maintenance responsibility. The value recovered through the charges is then taxable at applicable rates.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI





 Get Daily Updates


