Own-account subcontracted services escape intermediary classification when suppliers perform substantive obligations rather than arrange another perso...
Restaurant business transfers qualify for GST exemption as going concerns when operations can continue independently despite retained past liabilities...
Voluntary customs statements and seizure evidence support penalties for attempted export of red sanders where alleged retractions remain unsubstantiat...
Page of 4960
Press 'Enter' after typing page number.
1 to 20 of 99183 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
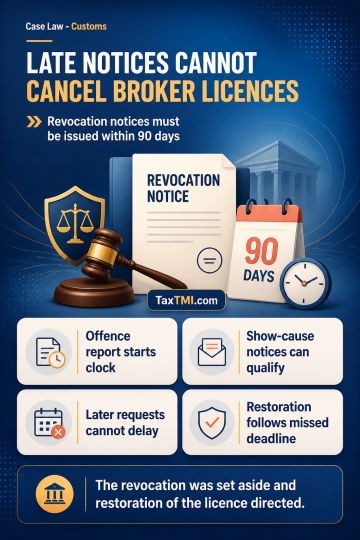
Regulation 17(1) of the CBLR, 2018 requires a notice proposing revocation of a Customs Broker licence to be issued within ninety days of receipt of the offence report. Where no separate investigation report exists, Customs Act show-cause notices containing the investigation summary, allegations and relied-upon documents constitute the offence report. The limitation period cannot be deferred by later requesting documents already received. A notice issued after the mandatory period leaves no statutory authority to revoke the licence; the revocation was set aside and restoration of the licence directed.
Regulation 17(1) of the CBLR, 2018 requires a notice proposing revocation of a Customs Broker licence to be issued within ninety days of receipt of the offence report. Where no separate investigation report exists, Customs Act show-cause notices containing the investigation summary, allegations and relied-upon documents constitute the offence report. The limitation period cannot be deferred by later requesting documents already received. A notice issued after the mandatory period leaves no statutory authority to revoke the licence; the revocation was set aside and restoration of the licence directed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI




 Get Daily Updates