Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Split air conditioner classification depends on capacity and refrigeration characteristics, with the specific tariff entry overriding the general desc...
    Pre-conversion interest on convertible debentures requires transaction-specific pricing; compulsory equity conversion alone cannot establish a nil int...
    Anti-circumvention measures require provisional assessment and guarantees for Malaysian-exported rock breakers, specified components and alloy steel t...
    Tariff rate quotas for vehicle imports under the India-UK trade agreement open for applications across specified vehicle categories.
    Input tax credit apportionment for banks and financial institutions turns on eligible registrations, same-PAN supplies and reporting rules.
    Demo vehicle input tax credit extends to authorised agents despite manufacturers selling vehicles directly to customers.
    Accredited investor eligibility now permits manager-led verification, group-wide recognition and deemed status for persons resident outside India.
    Customs message amendments: The designated officer changes from Import Noting to EDI, while other public notice provisions remain unchanged.
    GST show-cause replies must precede personal hearings, with same-day scheduling irregular in input tax credit adjudication.
    Interim protection in GST investigations involving serious criminal allegations depends on case diary review and hearing the State.
    Self-assessed GST is not excluded from interest waiver in tax proceedings, while approved waivers face revocation limits.
    Service tax appeal pre-deposit refunds escape GST limitation and unjust enrichment despite mistaken payment through Form DRC-03.
    Audit-based GST fraud demands require evidence of deliberate wrongdoing, with fresh determination and limitation affecting recovery across different y...
    GST sales-return demands require notified grounds and a personal hearing before adverse adjudication, not merely at a later stage.
    Wrongly availed input tax credit attracts interest only when utilised, while residual penalty requires an independent statutory basis.
    Wrongly claimed and used input tax credit attracts interest when ledger balances show consumption before reversal, regardless of intent.
    Non-woven fabric bag classification follows the textile intermediate, while GST proceedings require reasons, impartial notices and consistent treatmen...
    Board opinion exclusion from GST appeal monetary limits requires a specific circular, not a petition on an identical issue.
    Concessional employee loan perquisites use SBI's prime lending rate as a valid, uniform benchmark under delegated tax rules.
    Reassessment of second-PAN cash deposits requires relevant material, while factual disputes over declared sales fall outside writ review.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Telegram Get Daily Updates

Section 107 of the CGST Act confines GST appeals to a...

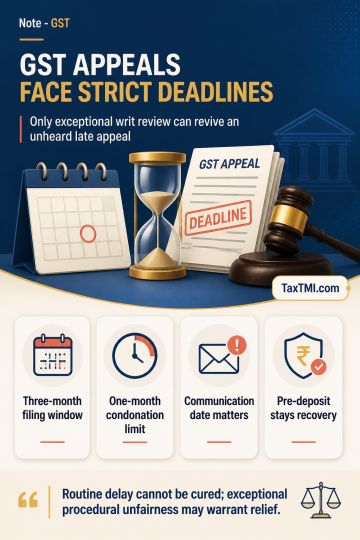
GST appeal limitation: statutory condonation remains capped, while exceptional writ review may restore an unheard appeal.

Contents
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

GST September 25, 2026 Notes
Section 107 of the CGST Act confines GST appeals to a three-month filing period, with condonation by the Appellate Authority limited to one further month upon sufficient cause. Section 5 of the Limitation Act cannot enlarge that statutory ceiling. Limitation runs from communication; portal availability and postal service under Section 169 may require factual scrutiny, while Rule 108 governs electronic or permitted manual filing where an order is unavailable on the portal. Statutory pre-deposit triggers a deemed stay of recovery for the balance demand. Article 226 may exceptionally restore an unheard appeal where defective communication, prompt action after knowledge and material procedural unfairness justify relief, but is not a routine cure for delay or inaction.

Topics

Acts Income Tax