Split air conditioner classification depends on capacity and refrigeration characteristics, with the specific tariff entry overriding the general desc...
Anti-circumvention measures require provisional assessment and guarantees for Malaysian-exported rock breakers, specified components and alloy steel t...
Audit-based GST fraud demands require evidence of deliberate wrongdoing, with fresh determination and limitation affecting recovery across different y...
Non-woven fabric bag classification follows the textile intermediate, while GST proceedings require reasons, impartial notices and consistent treatmen...
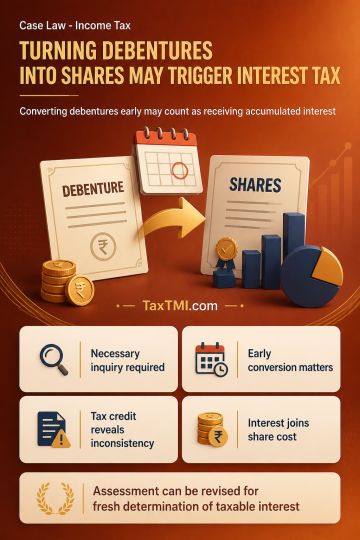
Revisionary jurisdiction applies where a reassessment accepts non-taxability of accumulated interest without necessary inquiry or application of governing provisions, rendering it erroneous and prejudicial to Revenue interests and permitting fresh determination. Premature conversion of zero-coupon debentures into equity shares of ascertainable value can constitute constructive receipt of accumulated interest even under cash-basis accounting. Claiming tax-deducted-at-source credit for that interest is inconsistent with denying the underlying income. The capital-gains exclusion for conversion does not exempt embedded interest from taxation; once taxed, the interest forms part of the shares' cost basis, preventing double taxation on sale.
Revisionary jurisdiction applies where a reassessment accepts non-taxability of accumulated interest without necessary inquiry or application of governing provisions, rendering it erroneous and prejudicial to Revenue interests and permitting fresh determination. Premature conversion of zero-coupon debentures into equity shares of ascertainable value can constitute constructive receipt of accumulated interest even under cash-basis accounting. Claiming tax-deducted-at-source credit for that interest is inconsistent with denying the underlying income. The capital-gains exclusion for conversion does not exempt embedded interest from taxation; once taxed, the interest forms part of the shares' cost basis, preventing double taxation on sale.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI


 Get Daily Updates