Split air conditioner classification depends on capacity and refrigeration characteristics, with the specific tariff entry overriding the general desc...
Anti-circumvention measures require provisional assessment and guarantees for Malaysian-exported rock breakers, specified components and alloy steel t...
Audit-based GST fraud demands require evidence of deliberate wrongdoing, with fresh determination and limitation affecting recovery across different y...
Non-woven fabric bag classification follows the textile intermediate, while GST proceedings require reasons, impartial notices and consistent treatmen...
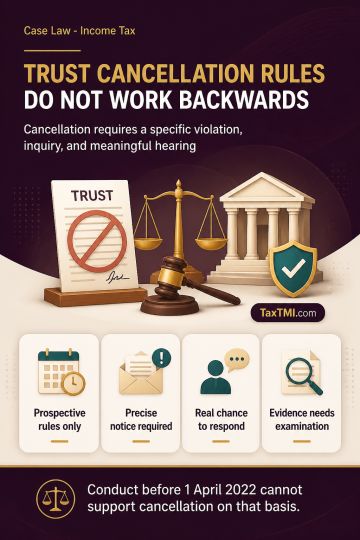
Specified-violation provisions for cancellation of trust registration apply prospectively from 1 April 2022; conduct preceding that date cannot support retrospective cancellation on that basis. Cancellation requires identification of the applicable statutory trigger and precise violation, an inquiry reaching satisfaction, and a meaningful opportunity to respond; a notice broadly combining cancellation and exemption-disallowance provisions is insufficient. Jurisdiction transferred under section 127 extends to all proceedings and permits cancellation by a Principal Commissioner or Commissioner. Alleged benefits to specified persons may affect exemption or tax diverted income but, unless they fall within a specified violation, do not alone justify cancellation. Retracted and uncorroborated evidence requires proper examination and cross-examination.
Specified-violation provisions for cancellation of trust registration apply prospectively from 1 April 2022; conduct preceding that date cannot support retrospective cancellation on that basis. Cancellation requires identification of the applicable statutory trigger and precise violation, an inquiry reaching satisfaction, and a meaningful opportunity to respond; a notice broadly combining cancellation and exemption-disallowance provisions is insufficient. Jurisdiction transferred under section 127 extends to all proceedings and permits cancellation by a Principal Commissioner or Commissioner. Alleged benefits to specified persons may affect exemption or tax diverted income but, unless they fall within a specified violation, do not alone justify cancellation. Retracted and uncorroborated evidence requires proper examination and cross-examination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI


 Get Daily Updates