Split air conditioner classification depends on capacity and refrigeration characteristics, with the specific tariff entry overriding the general desc...
Anti-circumvention measures require provisional assessment and guarantees for Malaysian-exported rock breakers, specified components and alloy steel t...
Audit-based GST fraud demands require evidence of deliberate wrongdoing, with fresh determination and limitation affecting recovery across different y...
Non-woven fabric bag classification follows the textile intermediate, while GST proceedings require reasons, impartial notices and consistent treatmen...
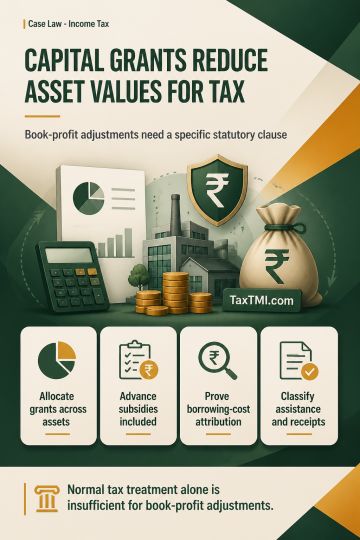
Capital grants, subsidies and consumer contributions reduce the actual cost or written-down value of relevant assets for depreciation. Where not directly attributable to a particular asset, they require allocation among the affected assets at their respective depreciation rates. Book-profit adjustments for such grants, including subsidy grants received in advance, require an identified clause in the Explanation to section 115JB(2); treatment under normal tax provisions alone is insufficient. Borrowing-cost capitalisation depends on direct attribution to qualifying capital projects and cannot rest on an unsupported assumed historical rate or unsubstantiated accounting-method change. Assistance for beneficiary-owned solar systems is revenue in nature, while business-linked staff-loan interest and miscellaneous receipts are business income; residual rental and staff recoveries may be income from other sources.
Capital grants, subsidies and consumer contributions reduce the actual cost or written-down value of relevant assets for depreciation. Where not directly attributable to a particular asset, they require allocation among the affected assets at their respective depreciation rates. Book-profit adjustments for such grants, including subsidy grants received in advance, require an identified clause in the Explanation to section 115JB(2); treatment under normal tax provisions alone is insufficient. Borrowing-cost capitalisation depends on direct attribution to qualifying capital projects and cannot rest on an unsupported assumed historical rate or unsubstantiated accounting-method change. Assistance for beneficiary-owned solar systems is revenue in nature, while business-linked staff-loan interest and miscellaneous receipts are business income; residual rental and staff recoveries may be income from other sources.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI


 Get Daily Updates