Independent manufacturing undertaking eligibility preserves Section 80IA/80IB deductions, while machinery kept ready for use qualifies for depreciatio...
Assessing Officer Satisfaction Requirement Bars Penalty for Cash Receipt in Immovable-Property Sale Cases Where Initiation Lacks Recorded Satisfaction...
Page of 4862
Press 'Enter' after typing page number.
1 to 20 of 97236 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
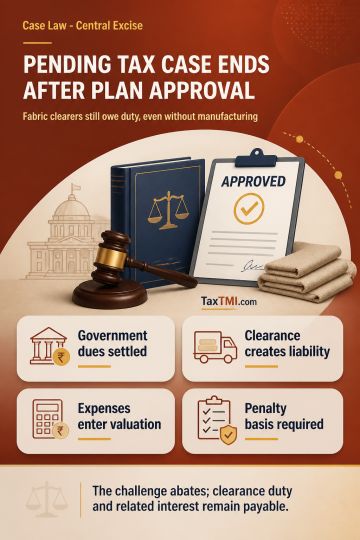
Approval of a resolution plan settling confirmed government dues causes the corporate debtor's pending excise appeal to abate. Excise duty remains payable by persons who clear processed fabrics, even where they are not manufacturers, because liability attaches on clearance; however, the transferee's specific penalty concerning stock was not sustained. Pre-clearance grading, cartage, brokerage and stock-interest expenses form part of assessable value where goods enter wholesale trade only on sale to independent buyers, sustaining the related duty and interest. Penalty for intent to evade duty requires findings of prescribed conduct and cannot rest solely on inadmissible valuation deductions. Penalties relating to confiscable goods likewise require their statutory basis; general penalties may instead apply to proven participation in duty evasion.
Approval of a resolution plan settling confirmed government dues causes the corporate debtor's pending excise appeal to abate. Excise duty remains payable by persons who clear processed fabrics, even where they are not manufacturers, because liability attaches on clearance; however, the transferee's specific penalty concerning stock was not sustained. Pre-clearance grading, cartage, brokerage and stock-interest expenses form part of assessable value where goods enter wholesale trade only on sale to independent buyers, sustaining the related duty and interest. Penalty for intent to evade duty requires findings of prescribed conduct and cannot rest solely on inadmissible valuation deductions. Penalties relating to confiscable goods likewise require their statutory basis; general penalties may instead apply to proven participation in duty evasion.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI