Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
COVID-19 limitation exclusion and destination-specific e-way bills govern revisional timelines and penalties for undocumented third-party plywood deli...
Questions arising from miscellaneous application orders cannot challenge unaltered Tribunal findings, leaving the original order separately challengea...
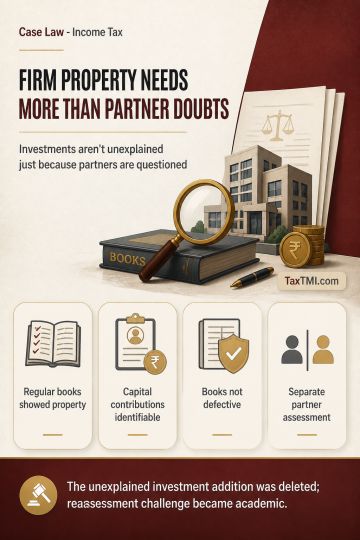
Section 69 applies only to investments not recorded in the assessee's books of account. Immovable properties recorded in the firm's regular books, together with corresponding identifiable partners' capital contributions, cannot be treated as unexplained investments where the books have not been found defective or rejected. Concerns about an individual partner's financial capacity must be examined in that partner's assessment and do not, by themselves, make the firm's recorded investment unexplained. Principles applicable to unexplained cash credits do not govern recorded investments under section 69. The addition for unexplained investment was therefore deleted, while the reassessment challenge was left academic.
Section 69 applies only to investments not recorded in the assessee's books of account. Immovable properties recorded in the firm's regular books, together with corresponding identifiable partners' capital contributions, cannot be treated as unexplained investments where the books have not been found defective or rejected. Concerns about an individual partner's financial capacity must be examined in that partner's assessment and do not, by themselves, make the firm's recorded investment unexplained. Principles applicable to unexplained cash credits do not govern recorded investments under section 69. The addition for unexplained investment was therefore deleted, while the reassessment challenge was left academic.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI