Appellate enhancement limits protect against new income sources, while documented credits and prior-year investments resist unexplained-income additio...
Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
Page of 4868
Press 'Enter' after typing page number.
1 to 20 of 97344 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
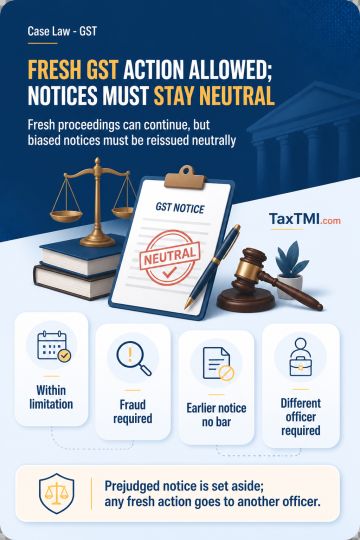
Fresh GST proceedings under Section 74 may be initiated within two years from communication of an earlier writ order that quashed a prior notice while expressly permitting fresh action, provided fraud, wilful misstatement or suppression of facts to evade tax exists. Section 75(3), read with that binding direction, preserves the period for consequential adjudication; an earlier dropped Section 73 notice does not bar the fresh proceedings. However, a show cause notice containing unnecessary accusations that the taxpayer misled the Court demonstrates prejudgment and breaches the requirement of neutral adjudication. Such a notice must be set aside, with any fresh action undertaken by a different officer.
Fresh GST proceedings under Section 74 may be initiated within two years from communication of an earlier writ order that quashed a prior notice while expressly permitting fresh action, provided fraud, wilful misstatement or suppression of facts to evade tax exists. Section 75(3), read with that binding direction, preserves the period for consequential adjudication; an earlier dropped Section 73 notice does not bar the fresh proceedings. However, a show cause notice containing unnecessary accusations that the taxpayer misled the Court demonstrates prejudgment and breaches the requirement of neutral adjudication. Such a notice must be set aside, with any fresh action undertaken by a different officer.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI