Appellate enhancement limits protect against new income sources, while documented credits and prior-year investments resist unexplained-income additio...
Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
Page of 4868
Press 'Enter' after typing page number.
1 to 20 of 97344 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
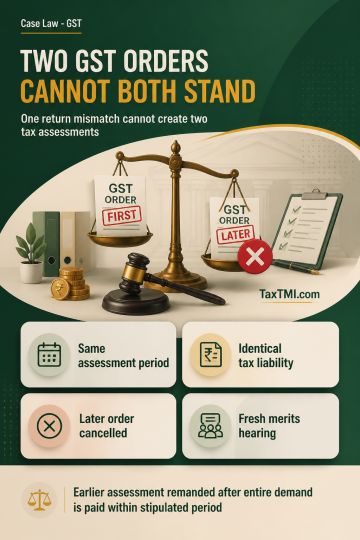
Duplicate assessment orders arising from the same GSTR-3B and GSTR-1 return mismatch cannot coexist where both concern the same assessment period and identical tax liability. The later order was quashed because it duplicated the earlier assessment, notwithstanding the absence of an SGST-CGST bifurcation. The earlier assessment order was set aside and remanded for fresh consideration to provide a reasonable opportunity to contest the tax proposal on merits. That remand was conditional on payment of the entire tax demand within the stipulated period.
Duplicate assessment orders arising from the same GSTR-3B and GSTR-1 return mismatch cannot coexist where both concern the same assessment period and identical tax liability. The later order was quashed because it duplicated the earlier assessment, notwithstanding the absence of an SGST-CGST bifurcation. The earlier assessment order was set aside and remanded for fresh consideration to provide a reasonable opportunity to contest the tax proposal on merits. That remand was conditional on payment of the entire tax demand within the stipulated period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI