Appellate enhancement limits protect against new income sources, while documented credits and prior-year investments resist unexplained-income additio...
Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
Page of 4868
Press 'Enter' after typing page number.
1 to 20 of 97344 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
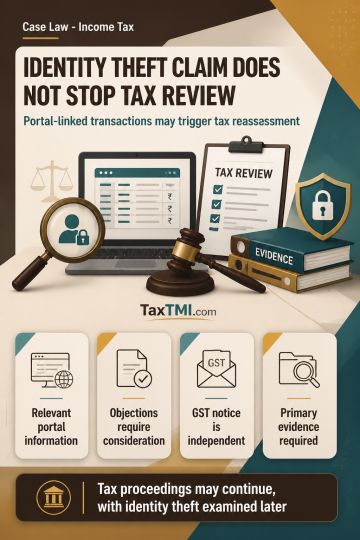
Reassessment under the amended scheme may be initiated where portal information links transactions to an assessee's PAN, provided the material is relevant and the assessing authority applies its mind to objections. Detailed reasons to believe are not required at the initiation stage. A GST communication does not bar an independent income-tax enquiry where identity theft has not been conclusively established. Reassessment may therefore continue, while the identity-theft defence remains open for examination. Although the assessee must substantiate that plea with evidence, the Revenue must first establish through positive primary evidence that the disputed transactions were undertaken by the assessee rather than another person.
Reassessment under the amended scheme may be initiated where portal information links transactions to an assessee's PAN, provided the material is relevant and the assessing authority applies its mind to objections. Detailed reasons to believe are not required at the initiation stage. A GST communication does not bar an independent income-tax enquiry where identity theft has not been conclusively established. Reassessment may therefore continue, while the identity-theft defence remains open for examination. Although the assessee must substantiate that plea with evidence, the Revenue must first establish through positive primary evidence that the disputed transactions were undertaken by the assessee rather than another person.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI