Fake-invoice penalties remain available where taxpayer admissions and records establish unsupported input tax credit claims and false GST documentatio...
Works contract classification applies to permanently installed fire-protection systems, while earthwork and obsolete IGST concessions remain unavailab...
Professional fee recovery for GST refund representation succeeds where direct engagement, fee acknowledgement, and authority are established despite c...
Transfer pricing of intra-group support services requires prescribed benchmarking; unsupported nil valuation and alternate business-expense disallowan...
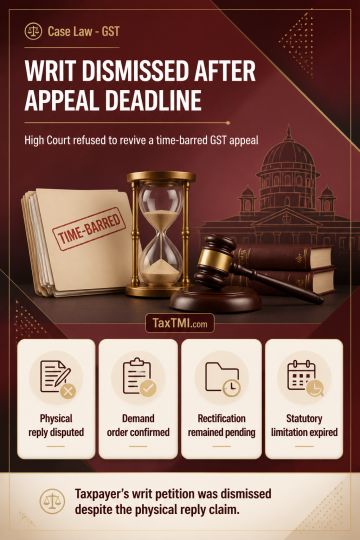
Extraordinary writ jurisdiction was declined where the taxpayer's statutory appeal against a GST demand had become time-barred. The notes state that the taxpayer submitted a physical reply to the show-cause notice because the portal had earlier been handled by a chartered accountant, but the final order recorded no reply and confirmed the demand. A rectification application under the GST Act remained pending but also appeared time-barred. The High Court dismissed the writ petition, stating that expiry of the statutory appellate limitation did not justify exercising jurisdiction under Article 226.
Extraordinary writ jurisdiction was declined where the taxpayer's statutory appeal against a GST demand had become time-barred. The notes state that the taxpayer submitted a physical reply to the show-cause notice because the portal had earlier been handled by a chartered accountant, but the final order recorded no reply and confirmed the demand. A rectification application under the GST Act remained pending but also appeared time-barred. The High Court dismissed the writ petition, stating that expiry of the statutory appellate limitation did not justify exercising jurisdiction under Article 226.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI