Appellate enhancement limits protect against new income sources, while documented credits and prior-year investments resist unexplained-income additio...
Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
Page of 4868
Press 'Enter' after typing page number.
1 to 20 of 97344 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
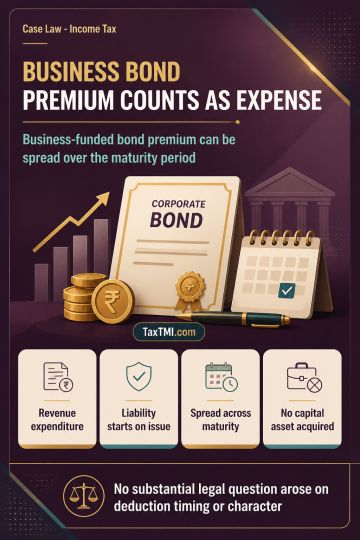
Redemption premium on foreign currency convertible bonds issued to raise and use business funds is characterised as revenue expenditure, because the liability arises on issuance and does not acquire a capital asset or enduring advantage. The notes state that expenditure connected with issuing debentures or obtaining loans is likewise revenue in nature. The premium liability arises in the year of issue and may be proportionately spread over the bonds' prescribed maturity period; it is immaterial whether redemption is at will or only at maturity. The text further records that no substantial question of law arose on either the revenue character or timing of the deduction.
Redemption premium on foreign currency convertible bonds issued to raise and use business funds is characterised as revenue expenditure, because the liability arises on issuance and does not acquire a capital asset or enduring advantage. The notes state that expenditure connected with issuing debentures or obtaining loans is likewise revenue in nature. The premium liability arises in the year of issue and may be proportionately spread over the bonds' prescribed maturity period; it is immaterial whether redemption is at will or only at maturity. The text further records that no substantial question of law arose on either the revenue character or timing of the deduction.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI