Appellate enhancement limits protect against new income sources, while documented credits and prior-year investments resist unexplained-income additio...
Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
Page of 4868
Press 'Enter' after typing page number.
1 to 20 of 97344 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
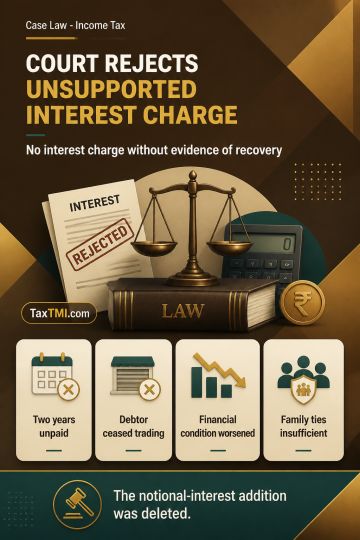
Under the mercantile system of accounting, notional interest on outstanding advances was not justified where evidence showed that no interest had been received for two preceding years and the debtor concerns' financial condition had deteriorated. One concern had ceased business activity, as indicated by cancellation of its sales tax registration and application to cancel excise registration, while material concerning the other concern was not properly considered. Family relationships with the assessee's partners alone did not support imputing interest. The article records that the High Court treated the contrary findings as perverse and deleted the notional-interest addition.
Under the mercantile system of accounting, notional interest on outstanding advances was not justified where evidence showed that no interest had been received for two preceding years and the debtor concerns' financial condition had deteriorated. One concern had ceased business activity, as indicated by cancellation of its sales tax registration and application to cancel excise registration, while material concerning the other concern was not properly considered. Family relationships with the assessee's partners alone did not support imputing interest. The article records that the High Court treated the contrary findings as perverse and deleted the notional-interest addition.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI