Independent manufacturing undertaking eligibility preserves Section 80IA/80IB deductions, while machinery kept ready for use qualifies for depreciatio...
Assessing Officer Satisfaction Requirement Bars Penalty for Cash Receipt in Immovable-Property Sale Cases Where Initiation Lacks Recorded Satisfaction...
Page of 4862
Press 'Enter' after typing page number.
1 to 20 of 97236 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
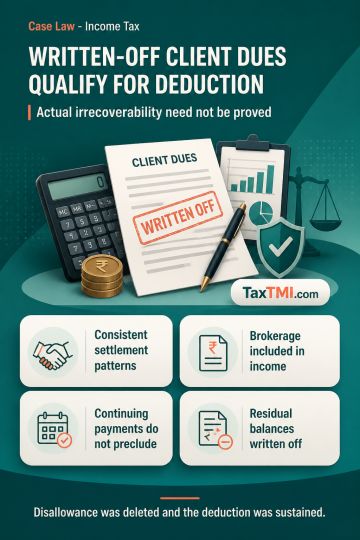
Bad-debt deduction for share-broking client dues may be claimed where outstanding client balances are treated as irrecoverable and written off in the accounts. Under amended section 36(1)(vii), actual irrecoverability need not be established. Continuing transactions or payments by clients do not preclude the claim where the broker follows a consistent settlement pattern under which clients pay agreed amounts and residual balances are written off. Client receivables qualify as debts when brokerage included in those receivables has been taken into account in computing income. The disallowance of the written-off client dues was deleted and the deduction sustained.
Bad-debt deduction for share-broking client dues may be claimed where outstanding client balances are treated as irrecoverable and written off in the accounts. Under amended section 36(1)(vii), actual irrecoverability need not be established. Continuing transactions or payments by clients do not preclude the claim where the broker follows a consistent settlement pattern under which clients pay agreed amounts and residual balances are written off. Client receivables qualify as debts when brokerage included in those receivables has been taken into account in computing income. The disallowance of the written-off client dues was deleted and the deduction sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI