Appellate enhancement limits protect against new income sources, while documented credits and prior-year investments resist unexplained-income additio...
Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
Page of 4868
Press 'Enter' after typing page number.
1 to 20 of 97344 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
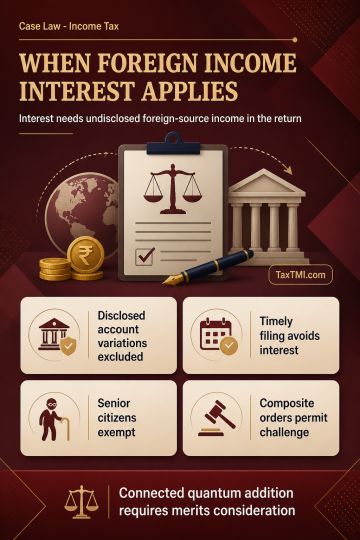
Interest on undisclosed foreign income under the Black Money Act requires non-disclosure of the foreign source in the return; estimation or variation of income from an already disclosed foreign account does not satisfy that condition. Timely filing also prevents interest under the incorporated late-filing computation provisions. Advance-tax interest cannot be imposed without clear statutory language establishing the liability and machinery, and incorporated advance-tax provisions include exemptions for resident senior citizens without business income. Where rectification adds interest linked to the underlying foreign-income addition, the original and rectified orders operate as a composite order, permitting a limited challenge to the connected quantum addition; that issue requires merits consideration.
Interest on undisclosed foreign income under the Black Money Act requires non-disclosure of the foreign source in the return; estimation or variation of income from an already disclosed foreign account does not satisfy that condition. Timely filing also prevents interest under the incorporated late-filing computation provisions. Advance-tax interest cannot be imposed without clear statutory language establishing the liability and machinery, and incorporated advance-tax provisions include exemptions for resident senior citizens without business income. Where rectification adds interest linked to the underlying foreign-income addition, the original and rectified orders operate as a composite order, permitting a limited challenge to the connected quantum addition; that issue requires merits consideration.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI