Faceless assessment and registration procedures are updated through electronic communication, revised recovery rules, extended deadlines, and replacem...
Risk-based selective vessel boarding requires accurate declarations and preserves master and agent liability where physical inspections are not select...
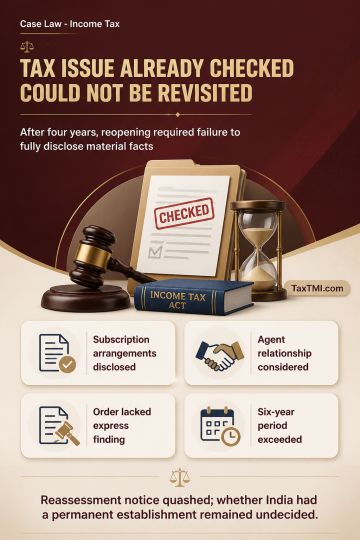
Permanent-establishment reassessment cannot revisit scrutinised disclosures; extended reopening fails without undisclosed material facts and within st...
The case involves a dispute over the valuation of imported goods declared as Bovine Leather Upholster Sofa. The Appellate Tribunal, u/s 14 of the Customs Act and Customs Valuation Rules, held that the transaction value should be accepted unless valid reasons exist for rejection. It criticized the enhancement of value by the Commissioner (Appeals) without notice, citing the principle that decisions should be based on pleadings. The Tribunal emphasized that the burden of proof lies with the Department to show the declared price is inaccurate. Relying on a departmental circular or market survey for valuation was deemed unlawful. Citing precedent, the Tribunal set aside the order and allowed the appeal.
The case involves a dispute over the valuation of imported goods declared as Bovine Leather Upholster Sofa. The Appellate Tribunal, u/s 14 of the Customs Act and Customs Valuation Rules, held that the transaction value should be accepted unless valid reasons exist for rejection. It criticized the enhancement of value by the Commissioner (Appeals) without notice, citing the principle that decisions should be based on pleadings. The Tribunal emphasized that the burden of proof lies with the Department to show the declared price is inaccurate. Relying on a departmental circular or market survey for valuation was deemed unlawful. Citing precedent, the Tribunal set aside the order and allowed the appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI