Section 115BBE classification requires a valid deeming-provision basis before special taxation, while the enhanced rate's temporal application remains...
Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
COVID-19 limitation exclusion and destination-specific e-way bills govern revisional timelines and penalties for undocumented third-party plywood deli...
Page of 4858
Press 'Enter' after typing page number.
1 to 20 of 97155 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
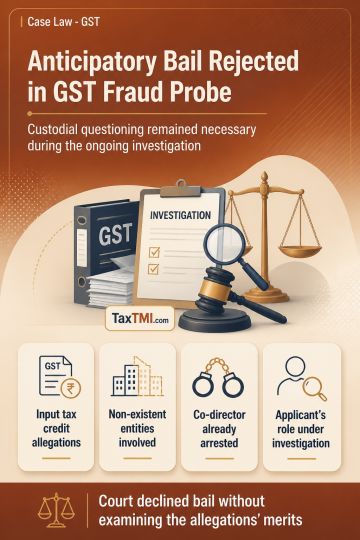
Anticipatory bail was considered in an investigation into alleged wrongful availment and utilisation of input tax credit through invoices issued by non-existent entities. The note states that a co-director had been arrested, the investigation remained ongoing, and the alleged tax evasion required the investigating agency to ascertain the applicant's role and that of other persons involved in the transactions. On that basis, custodial interrogation could not be ruled out, and anticipatory bail was rejected without addressing the merits of the allegations.
Anticipatory bail was considered in an investigation into alleged wrongful availment and utilisation of input tax credit through invoices issued by non-existent entities. The note states that a co-director had been arrested, the investigation remained ongoing, and the alleged tax evasion required the investigating agency to ascertain the applicant's role and that of other persons involved in the transactions. On that basis, custodial interrogation could not be ruled out, and anticipatory bail was rejected without addressing the merits of the allegations.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI