Section 115BBE classification requires a valid deeming-provision basis before special taxation, while the enhanced rate's temporal application remains...
Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
COVID-19 limitation exclusion and destination-specific e-way bills govern revisional timelines and penalties for undocumented third-party plywood deli...
Page of 4858
Press 'Enter' after typing page number.
1 to 20 of 97155 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
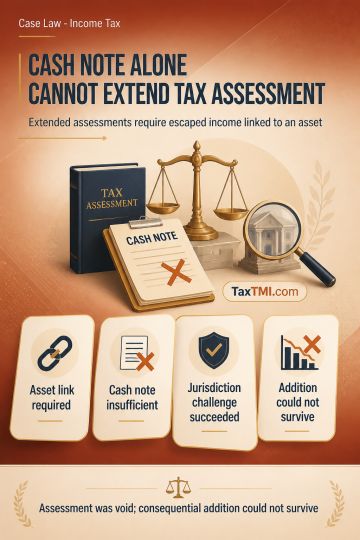
Section 153C jurisdiction for assessment years beyond the six preceding years requires the Assessing Officer to record satisfaction that escaped income is represented by an asset. The six-year period is reckoned from the assessment year relevant to the previous year in which seized material is received by the Assessing Officer having jurisdiction over the other person; on that basis, AY 2015-16 fell within the extended period. However, a satisfaction note referring only to alleged cash transactions did not establish the mandatory asset-representation condition. The assessment was therefore treated as void for lack of valid jurisdiction, and the consequential addition could not survive; issues concerning digital evidence, consolidated satisfaction and merits remained open.
Section 153C jurisdiction for assessment years beyond the six preceding years requires the Assessing Officer to record satisfaction that escaped income is represented by an asset. The six-year period is reckoned from the assessment year relevant to the previous year in which seized material is received by the Assessing Officer having jurisdiction over the other person; on that basis, AY 2015-16 fell within the extended period. However, a satisfaction note referring only to alleged cash transactions did not establish the mandatory asset-representation condition. The assessment was therefore treated as void for lack of valid jurisdiction, and the consequential addition could not survive; issues concerning digital evidence, consolidated satisfaction and merits remained open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI