Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
COVID-19 limitation exclusion and destination-specific e-way bills govern revisional timelines and penalties for undocumented third-party plywood deli...
Questions arising from miscellaneous application orders cannot challenge unaltered Tribunal findings, leaving the original order separately challengea...
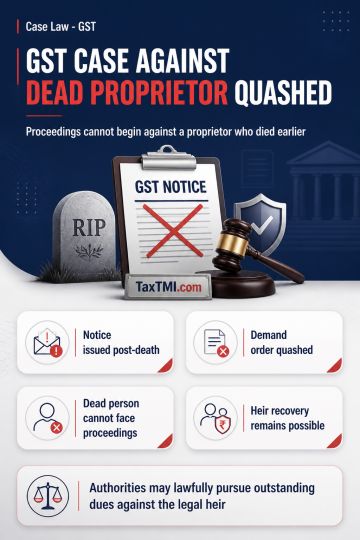
GST proceedings initiated against a deceased taxable person are invalid where the proprietor died before initiation. The notice and demand order issued in the deceased proprietor's name were quashed because they could not be sustained against a dead person. The legal position does not prevent lawful recovery action: proper proceedings may be initiated against the legal heir for any outstanding demand in accordance with law.
GST proceedings initiated against a deceased taxable person are invalid where the proprietor died before initiation. The notice and demand order issued in the deceased proprietor's name were quashed because they could not be sustained against a dead person. The legal position does not prevent lawful recovery action: proper proceedings may be initiated against the legal heir for any outstanding demand in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI