Faceless assessment and registration procedures are updated through electronic communication, revised recovery rules, extended deadlines, and replacem...
Risk-based selective vessel boarding requires accurate declarations and preserves master and agent liability where physical inspections are not select...
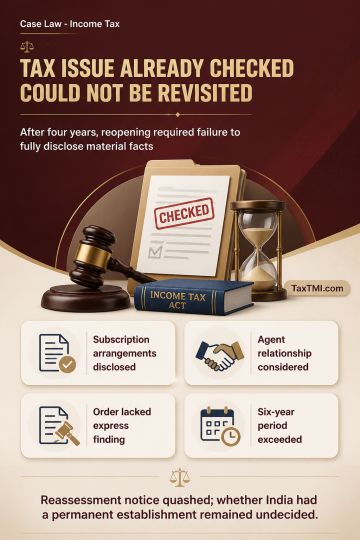
Permanent-establishment reassessment cannot revisit scrutinised disclosures; extended reopening fails without undisclosed material facts and within st...
Recredit of amount already reversed - It is a fact on record that when the appellant filed the refund claim of cenvat credit reversed by them, it was not the issue but with the introduction of CGST Act 2017, the issue of re-credit was arise in terms of Section 142 (3) of the CGST Act 2017 and the appellant was having no occasion to raise the issue of the re-credit before the adjudicating authority - The appellant is entitled to recredit of the amount already reversed before introduction of CGST Act 2017 - AT
Recredit of amount already reversed - It is a fact on record that when the appellant filed the refund claim of cenvat credit reversed by them, it was not the issue but with the introduction of CGST Act 2017, the issue of re-credit was arise in terms of Section 142 (3) of the CGST Act 2017 and the appellant was having no occasion to raise the issue of the re-credit before the adjudicating authority - The appellant is entitled to recredit of the amount already reversed before introduction of CGST Act 2017 - AT
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI