Preferential tariff claims under trade agreements require agreement-consistent origin checks, with safeguards against automatic denial for subsequent ...
Suppressed outward supplies require transaction-wise verification and reasoned findings before diary entries can support tax and penalty determination...
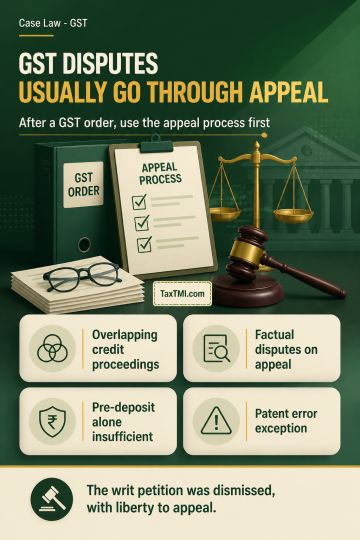
Availability of an efficacious statutory appeal materially constrains Article 226 writ jurisdiction in GST adjudication. Once show-cause proceedings culminate in an Order-in-Original, disputes over overlapping State and Central input tax credit proceedings, factual and evidentiary material, and a multi-year notice should ordinarily be examined on appeal. A statutory pre-deposit obligation and the earlier filing of a writ during pending notice proceedings do not alone justify bypassing that remedy. Absent patent jurisdictional infirmity, appellate review remains available on all permissible grounds; the writ petition was dismissed with liberty to appeal.
Availability of an efficacious statutory appeal materially constrains Article 226 writ jurisdiction in GST adjudication. Once show-cause proceedings culminate in an Order-in-Original, disputes over overlapping State and Central input tax credit proceedings, factual and evidentiary material, and a multi-year notice should ordinarily be examined on appeal. A statutory pre-deposit obligation and the earlier filing of a writ during pending notice proceedings do not alone justify bypassing that remedy. Absent patent jurisdictional infirmity, appellate review remains available on all permissible grounds; the writ petition was dismissed with liberty to appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI


 Get Daily Updates