Cross-border secondment reimbursements require separate employment and knowledge-transfer analysis before taxation as included services under the Indi...
Customs procedure uniformity requires adoption of model clearance practices, subject to specific local requirements and infrastructure or geographical...
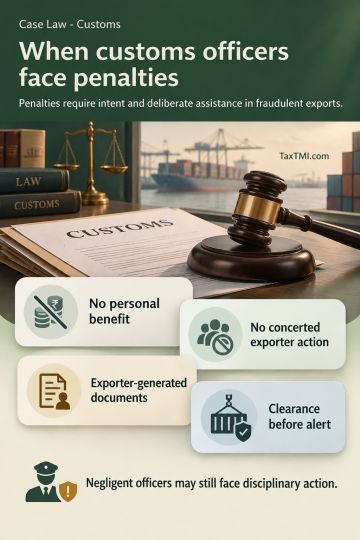
Personal penalties on customs officers under Section 114 of the Customs Act, 1962 require proof of mens rea and a positive, deliberate act of abetment rendering goods liable to confiscation. Mere negligence, administrative oversight or inefficient performance of official duties does not establish penal abetment, although disciplinary action may follow. Relevant circumstances include the absence of personal benefit or concerted action with exporters, ordinary processing of exporter-generated documents, and prompt disclosure of a clearance completed before a cautionary alert. A later alert cannot retrospectively justify penalising an earlier clearance.
Personal penalties on customs officers under Section 114 of the Customs Act, 1962 require proof of mens rea and a positive, deliberate act of abetment rendering goods liable to confiscation. Mere negligence, administrative oversight or inefficient performance of official duties does not establish penal abetment, although disciplinary action may follow. Relevant circumstances include the absence of personal benefit or concerted action with exporters, ordinary processing of exporter-generated documents, and prompt disclosure of a clearance completed before a cautionary alert. A later alert cannot retrospectively justify penalising an earlier clearance.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI


 Get Daily Updates