Cross-border secondment reimbursements require separate employment and knowledge-transfer analysis before taxation as included services under the Indi...
Customs procedure uniformity requires adoption of model clearance practices, subject to specific local requirements and infrastructure or geographical...
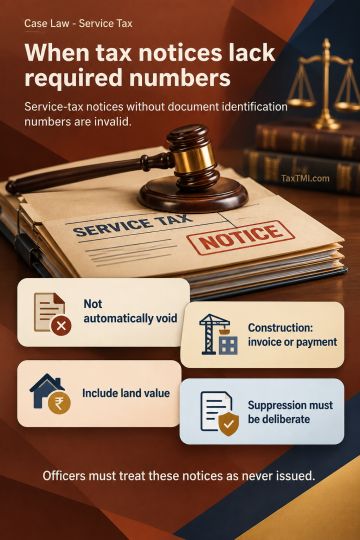
Service-tax notices issued without the prescribed Document Identification Number are invalid, and departmental officers must treat them as never issued under binding instructions, although they do not become void unless set aside by a competent court or authority. Construction-service tax arises on the earlier of invoicing or receipt of payment, rather than accounting revenue recognition; reconciliation must account for amounts already taxed, current invoices and advances, and applicable abatements and exemptions. Construction-service abatement permits input-service credit but requires land value to be included in the amount charged; the department must prove a breach to deny it. Extended limitation requires deliberate suppression, not mere inaction, and cannot be invoked because the department failed to scrutinise facts already known to it. This limitation also applies to recovery of a verified CENVAT credit disallowance.
Service-tax notices issued without the prescribed Document Identification Number are invalid, and departmental officers must treat them as never issued under binding instructions, although they do not become void unless set aside by a competent court or authority. Construction-service tax arises on the earlier of invoicing or receipt of payment, rather than accounting revenue recognition; reconciliation must account for amounts already taxed, current invoices and advances, and applicable abatements and exemptions. Construction-service abatement permits input-service credit but requires land value to be included in the amount charged; the department must prove a breach to deny it. Extended limitation requires deliberate suppression, not mere inaction, and cannot be invoked because the department failed to scrutinise facts already known to it. This limitation also applies to recovery of a verified CENVAT credit disallowance.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI


 Get Daily Updates